FAFSA for U.S. Expats: How Foreign Income and Taxes Affect Financial Aid

- Key Takeaways
- What Is the FAFSA, and Can U.S. Expats Apply?
- How Does FAFSA Treat Foreign Earned Income?
- Reporting Foreign Taxes Paid and the Foreign Tax Credit
- Reporting Foreign Bank Accounts, Property, and Assets
- Using FAFSA to Attend Universities Outside the United States
- What If Your Income Has Changed Significantly?
- FAFSA Deadlines for 2027–2028
- Step-by-Step: Completing the FAFSA from Abroad
- Expat FAFSA Checklist
- Frequently Asked Questions
- Getting Your Expat Taxes in Order
- Related Articles

The Free Application for Federal Student Aid (FAFSA) is the gateway for American students seeking federal grants, direct student loans, and work-study programs. American citizens and eligible noncitizens living outside the United States qualify for this aid just like families living stateside. However, reporting foreign earnings, expat tax write-offs, and overseas assets can introduce unique hurdles.
If your family earns a salary in a foreign currency, claims the Foreign Earned Income Exclusion (FEIE), files tax returns in multiple countries, or holds foreign bank accounts, your federal tax return does not tell the whole story. FAFSA applies distinct calculation rules to international finances, especially regarding excluded earnings and non-U.S. citizen parents.
Here is what American expat families need to know about completing the FAFSA, reporting foreign income accurately, and avoiding costly filing delays.
Key Takeaways
- U.S. citizens abroad can apply. Living overseas doesn’t change your child’s citizenship or disqualify them from federal student aid.
- Foreign income is counted. Wages earned abroad count toward financial aid calculations, even when that money is shielded from U.S. tax.
- The FEIE is included in aid calculations. Excluded foreign earnings generally must be reported separately and are considered in the Student Aid Index (SAI) and certain Pell Grant eligibility calculations.
- Parents do not need U.S. citizenship or an SSN. A non-U.S. citizen parent can verify their identity and submit their section of the form through StudentAid.gov.
- Primary home equity remains protected. While foreign investment properties and international bank balances count as reportable assets, FAFSA excludes the equity in your family’s primary home worldwide.
- Federal student loans work at select foreign universities. Certain foreign universities participate in the U.S. Direct Loan program, though federal grants generally remain restricted to domestic colleges.

Unsure How Expat Tax Exclusions Impact Your Aid?
What Is the FAFSA, and Can U.S. Expats Apply?
Administered by the U.S. Department of Education, the FAFSA determines a student’s eligibility for need-based and non-need-based federal assistance:
- Federal Pell Grants: Direct grants for undergraduate students with exceptional financial need that do not require repayment.
- Federal Direct Loans: Student loans funded directly by the federal government (subsidized and unsubsidized).
- Federal Work-Study: Campus-based employment programs helping eligible students earn money for education expenses.
Many states and domestic colleges also use your FAFSA submission to award their own state scholarships and institutional grants.
Your physical location does not affect your child’s right to apply. If your child holds a U.S. passport or green card, they can submit the FAFSA from anywhere in the world. As long as they enroll in an eligible degree program at an approved institution, their overseas background will not prevent them from receiving federal aid.
FAFSA vs. CSS Profile: Do You Need Both?
Many families applying to selective colleges encounter both the FAFSA and the College Board’s CSS Profile. They serve different purposes and calculate need differently:
| Feature | FAFSA | CSS Profile |
| Main Purpose | Federal grants, Direct Loans, and work-study | University-funded grants and institutional endowments |
| Application Cost | Free | $25 for the first school; $16 per additional school |
| Foreign Income | Uses IRS data and separately reported FEIE amounts | Evaluates global earnings, employer benefits, and untaxed stipends |
| Primary Home Equity | Excluded worldwide | May be collected; treatment varies by school |
| Foreign Tax Returns | Converted manually to USD if no U.S. return is filed | Evaluates dual filings and local notices of assessment |
| Currency | U.S. dollars only | Supports home-country currency selection |
If your child wants access to federal loans or federal grants, always file the FAFSA. If a private or selective public university on their list also asks for the CSS Profile, you must submit both forms separately.
Learn how colleges evaluate global home equity and overseas tax returns in our complete guide to the CSS Profile for U.S. Expats.
How Does FAFSA Treat Foreign Earned Income?
FAFSA evaluates income from the student and their parent contributors. For families abroad, reportable income includes:
- Wages or salaries from foreign employers
- Net income from international self-employment or consulting
- Foreign rental property earnings and business distributions
- Dividends, interest, and capital gains from overseas accounts
- Untaxed foreign allowances and stipends
As a U.S. expat, you report worldwide income on your federal Form 1040 regardless of where you live. However, IRS expat tax provisions can make your Adjusted Gross Income (AGI) appear minimal. The Department of Education uses specific formulas to evaluate families based on their actual financial capacity rather than their taxable baseline.
Related Reading: What’s the difference between AGI and MAGI?
Does FAFSA Count the Foreign Earned Income Exclusion (FEIE)?
The Foreign Earned Income Exclusion lets qualifying Americans abroad exclude foreign wages from U.S. taxation using IRS Form 2555. For the 2025 tax year (which populates the 2027–2028 FAFSA), the maximum exclusion was $130,000 per qualifying worker, rising to $132,900 for the 2026 tax year.
On federal returns, this exclusion appears on Schedule 1 (Form 1040), line 8d, and reduces your adjusted gross income. FAFSA treats the excluded earnings differently from the IRS, and the FEIE amount generally must be reported separately rather than relying on the automatic IRS data transfer.
- Student Aid Index (SAI) Formula: The excluded amount is included as untaxed income when calculating your family’s SAI.
- Pell Grant Eligibility: Beginning with the 2026–2027 award year, excluded foreign earnings are added to AGI when determining eligibility for maximum and minimum Pell Grants.
Example: You earned the local equivalent of $140,000 working in France during 2025 and claimed the maximum $130,000 FEIE on your U.S. tax return. Your AGI could be much lower than your actual earnings, but FAFSA doesn’t simply ignore the excluded $130,000. That income is considered under the applicable financial aid formulas alongside other financial information. The result depends on your family’s complete circumstances, not just the FEIE amount.
Does Claiming the FEIE Hurt Your Financial Aid?
Not necessarily. Financial aid formulas weigh your total earnings baseline against household size and family college costs. The FEIE is an IRS tax mechanism, not a financial aid discount. Having a low U.S. AGI on Form 1040 will not artificially lower your Student Aid Index.
Never alter your expat tax filing strategy simply to influence financial aid. Giving up the FEIE without analyzing your host country’s tax treaty can lead to significant U.S. tax liabilities without changing how financial aid formulas treat your overall earnings.
Reporting Foreign Taxes Paid and the Foreign Tax Credit
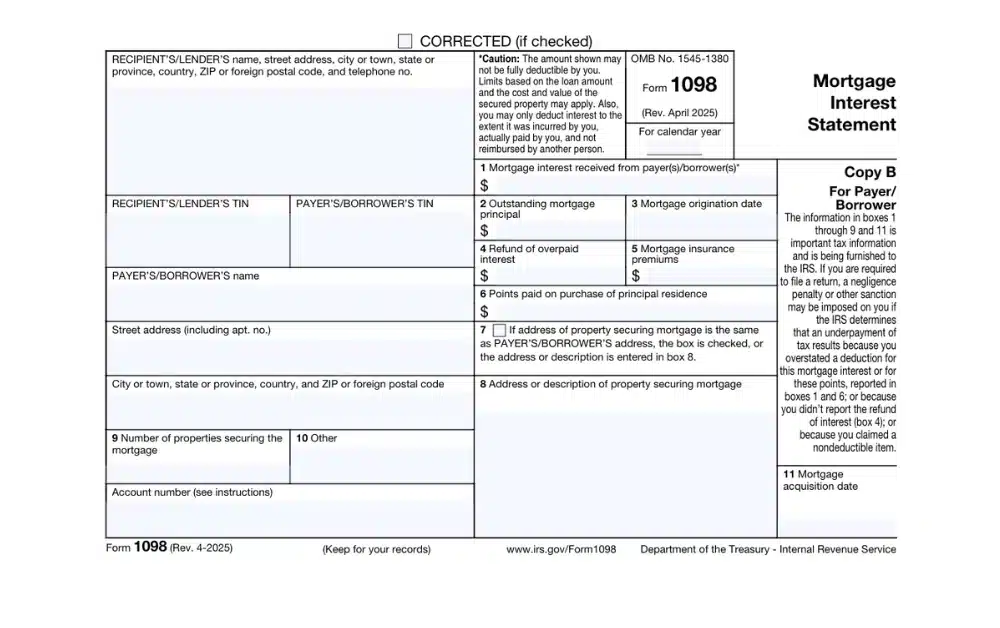
Many American expats pay income taxes directly to their host country and claim the Foreign Tax Credit (FTC) on IRS Form 1116 to offset double taxation.
When completing the FAFSA, keep these distinct tax figures clear:
- Foreign income taxes paid to another government
- Foreign Tax Credits claimed on IRS Form 1116
- U.S. federal income tax liability (Form 1040)
FAFSA includes an income tax allowance when calculating a family’s Student Aid Index, but the amount depends on how the taxpayer reports their income. If you file a U.S. federal return and claim the Foreign Tax Credit, don’t assume the amount shown on Form 1116 is the same as the income tax paid figure used by FAFSA.
If you file only a foreign tax return, FAFSA requires you to enter comparable income and tax information in U.S. dollars. For families paying substantial foreign income taxes, the financial aid calculation may not fully reflect their current take-home pay. If you believe your family’s circumstances warrant additional consideration, contact your university’s financial aid office about a special-circumstances review.

Take the Guesswork Out of Expat Tax Prep
What If You File Both U.S. and Foreign Tax Returns?
When a U.S. citizen parent completes the FAFSA, the application uses the FA-DDX (Future Act Direct Data Exchange) to import federal tax data directly from the IRS.
Even with automated IRS transfers, excluded foreign earned income generally must be entered separately when requested. Never overwrite imported U.S. figures with amounts from your local foreign tax return. Your U.S. Form 1040 remains your baseline tax document for federal aid.
What If a Parent Files Only a Foreign Tax Return?
If a parent is a non-resident alien or has no legal requirement to file with the IRS, they will report their finances manually:
- Select the option indicating they filed a foreign tax return when answering the tax questions.
- Convert all foreign income and local tax figures into U.S. dollars using the published exchange rate on the date the form is completed.
- Provide consent and approval to retrieve federal tax data (which will confirm their non-filer status with the IRS).
- Report total earnings from work if their local income fell below the foreign government’s mandatory tax filing threshold.
What If a Parent Is Not a U.S. Citizen or Lacks an SSN?
Many American children living abroad have one parent who is not a U.S. citizen. A parent’s citizenship status does not affect their child’s eligibility for federal student aid.
FAFSA doesn’t evaluate parental citizenship, and parents without a Social Security number can create StudentAid.gov accounts and follow the identity verification process:
- When adding the parent as a contributor, indicate that they do not have an SSN.
- Do not enter an Individual Taxpayer Identification Number (ITIN) into the SSN field. ITINs are entered into a dedicated ITIN field if the parent has one.
- The non-SSN parent creates a StudentAid.gov account and follows any identity verification instructions provided. Depending on their account status, they may be able to complete and sign their section even if verification has not been fully resolved.
- The parent logs in to complete their section and provide the required consent and signature.
Reporting Foreign Bank Accounts, Property, and Assets
FAFSA evaluates household net worth as of the date the application is submitted. For expat families, international assets are treated under standard federal rules:
- Foreign Bank Accounts: Convert checking, savings, and cash deposits in overseas banks to U.S. dollars and report them.
- Foreign Investments: Overseas brokerage accounts, mutual funds, stocks, and secondary real estate holdings (such as rental apartments or vacation homes) are reportable investments.
- Your Primary Residence Abroad: Excluded. FAFSA explicitly excludes equity in your family’s principal residence, whether that home is in Seattle or Madrid.
- Foreign Retirement Accounts: Standard government-recognized retirement plans are excluded from reportable investments. However, because foreign pensions (such as UK SIPPs or Canadian RRSPs) lack specific IRS statutory definitions, consult the financial aid office if you are unsure whether an overseas retirement vehicle is protected.
Note: FAFSA reporting is completely independent of the Treasury’s Foreign Bank Account Report. Filing an FBAR does not satisfy FAFSA requirements, and vice versa.
Using FAFSA to Attend Universities Outside the United States
American students do not have to study in the United States to use federal financial aid. Certain foreign universities across Europe, Canada, Australia, and the UK participate in the Federal Direct Loan program.
However, federal aid at international universities carries important restrictions:
- Federal Loans Only: Eligible foreign schools can process Direct Subsidized, Direct Unsubsidized, and Direct PLUS loans.
- No Federal Pell Grants: Federal grants cannot be used for regular degree programs at foreign institutions.
- Program Restrictions: Many foreign medical, nursing, and distance-learning programs are statutorily barred from participating in U.S. loan programs even if the university itself is approved.
Search the federal school code database on StudentAid.gov to confirm that your target overseas institution and specific degree program are certified to disburse federal loans.
Related reading: Review our guides to U.S. taxes for students studying abroad and education tax benefits for children attending foreign universities.
What If Your Income Has Changed Significantly?
FAFSA relies on “prior-prior year” tax data. The 2027–2028 FAFSA evaluates 2025 tax year information.
For expat families, two years is a long time. Currency swings, international relocations, changing expat corporate compensation packages, or sudden job losses can make historical tax numbers misleading.
You cannot alter historical tax figures on the FAFSA form itself. Instead:
- Submit the FAFSA using the required prior-prior tax year records.
- Contact the financial aid office at each college and request a Special Circumstances Review (also known as a Professional Judgment review).
- Provide documentation showing the change in your financial reality—such as termination letters, new employment contracts, foreign severance records, or exchange rate calculations showing reduced purchasing power.
Following a special-circumstances review, financial aid administrators may make permitted adjustments to the underlying FAFSA information that affects your Student Aid Index.
FAFSA Deadlines for 2027–2028
The 2027–2028 FAFSA covers the academic year running from July 1, 2027, through June 30, 2028.
Keep three distinct deadlines in mind:
- College Deadlines: Often the earliest and most critical. Priority institutional deadlines frequently arrive between November and February. Missing these dates can forfeit access to campus-based funds.
- State Deadlines: State-administered aid programs set individual filing cutoffs, many of which operate on a first-come, first-served basis.
- Federal Deadline: The final federal cutoff is June 30, 2028.
Because gathering foreign tax records, converting currencies, and verifying non-SSN accounts takes extra time, submit your form as early in the application cycle as possible.
Step-by-Step: Completing the FAFSA from Abroad
- Create StudentAid.gov accounts
The student and all required parent contributors must set up an FSA ID. Parents without an SSN should follow the account and identity verification instructions provided.
- Gather tax records
Pull your U.S. Form 1040, Form 2555, Form 1116, and any relevant foreign tax assessments or employer wage summaries.
- Initiate the student section
The student starts the application, enters personal and academic plans, and lists preferred universities.
- Invite parent contributors
The student sends email invites through the portal to their parents.
- Approve IRS data transfers
Parents log in, complete contributor identity prompts, and consent to direct tax data retrieval via the FA-DDX.
- Report overseas figures
Enter any required excluded foreign income figures, convert foreign assets to U.S. dollars, and review the summary.
- Sign and submit
Once all contributors provide digital signatures, submit the application and save the FAFSA Submission Summary for your records.
Expat FAFSA Checklist
- Confirm the student’s U.S. citizenship or eligible noncitizen status.
- Verify that target domestic or foreign colleges have active Federal School Codes.
- Create StudentAid.gov accounts for the student and all required parent contributors.
- Gather Form 1040, Schedule 1 (Line 8d for FEIE), and foreign wage records from the required tax year.
- Convert non-U.S. bank balances and reportable foreign investments to USD using current exchange rates.
- Confirm that your primary foreign residence is excluded from reportable real estate.
- Review state, university, and federal submission deadlines.
- File the CSS Profile separately if required by institutional aid programs.
- Contact financial aid administrators if your current income has dropped significantly since the reported tax year.

Ready to Get Your Expat Taxes Filed?
Frequently Asked Questions
Yes. U.S. citizens living overseas qualify for federal student aid programs on the same terms as domestic residents. Awards depend on household financial need, program eligibility, and university participation.
Yes. Excluded foreign earned income generally must be reported separately and is included in the Student Aid Index calculation and certain Pell Grant eligibility calculations.
Parents without an SSN can establish a StudentAid.gov account and follow the identity verification instructions. In some circumstances, they can complete and sign their FAFSA section while verification remains unresolved. Their lack of an SSN does not by itself affect their child’s aid eligibility.
No. The FAFSA formula excludes the net equity of your primary residence, regardless of whether the home is in the U.S. or abroad. Secondary properties and foreign rental units remain reportable.
No. Unlike the CSS Profile, the FAFSA requires all financial data to be entered in U.S. dollars. Any foreign earnings or asset figures must be converted using current exchange rates before entry.
Neither form holds procedural priority. Check the institutional deadlines for every university on your list and ensure each application is submitted by its respective cutoff date.
Log in to your StudentAid.gov dashboard, select your submitted application, and click “Make Corrections.” Update the relevant fields and resubmit. If the error significantly changes your income or family structure, notify your college financial aid offices directly.
Getting Your Expat Taxes in Order
Completing the FAFSA highlights how closely your U.S. tax compliance connects to your family’s higher education opportunities. Accurate federal tax returns, foreign wage reporting, and Form 2555 exclusions provide a clean, verifiable foundation for financial aid review.
Greenback Expat Tax Services helps Americans worldwide navigate U.S. filing obligations smoothly and accurately. Whether you need to file your upcoming return or catch up on past years, our team of CPAs and Enrolled Agents is here to assist.
Disclaimer: Greenback provides U.S. expat tax preparation services. We do not complete FAFSA applications or determine financial aid awards. For specific questions regarding federal aid eligibility, contact Federal Student Aid or your university’s financial aid office.
Related Articles

Featured In