FATCA Reporting and Filing Requirements: What the Law Means for You

- What Is FATCA?
- What Are the FATCA Filing Requirements?
- How Does FATCA Work With Foreign Banks?
- Which Countries Have FATCA Agreements?
- Why Is Your Foreign Bank Asking About Your U.S. Status?
- What Are the Penalties for FATCA Non-Compliance?
- Frequently Asked Questions about FATCA
- Your Own Foreign Assets Decide Whether You File Form 8938
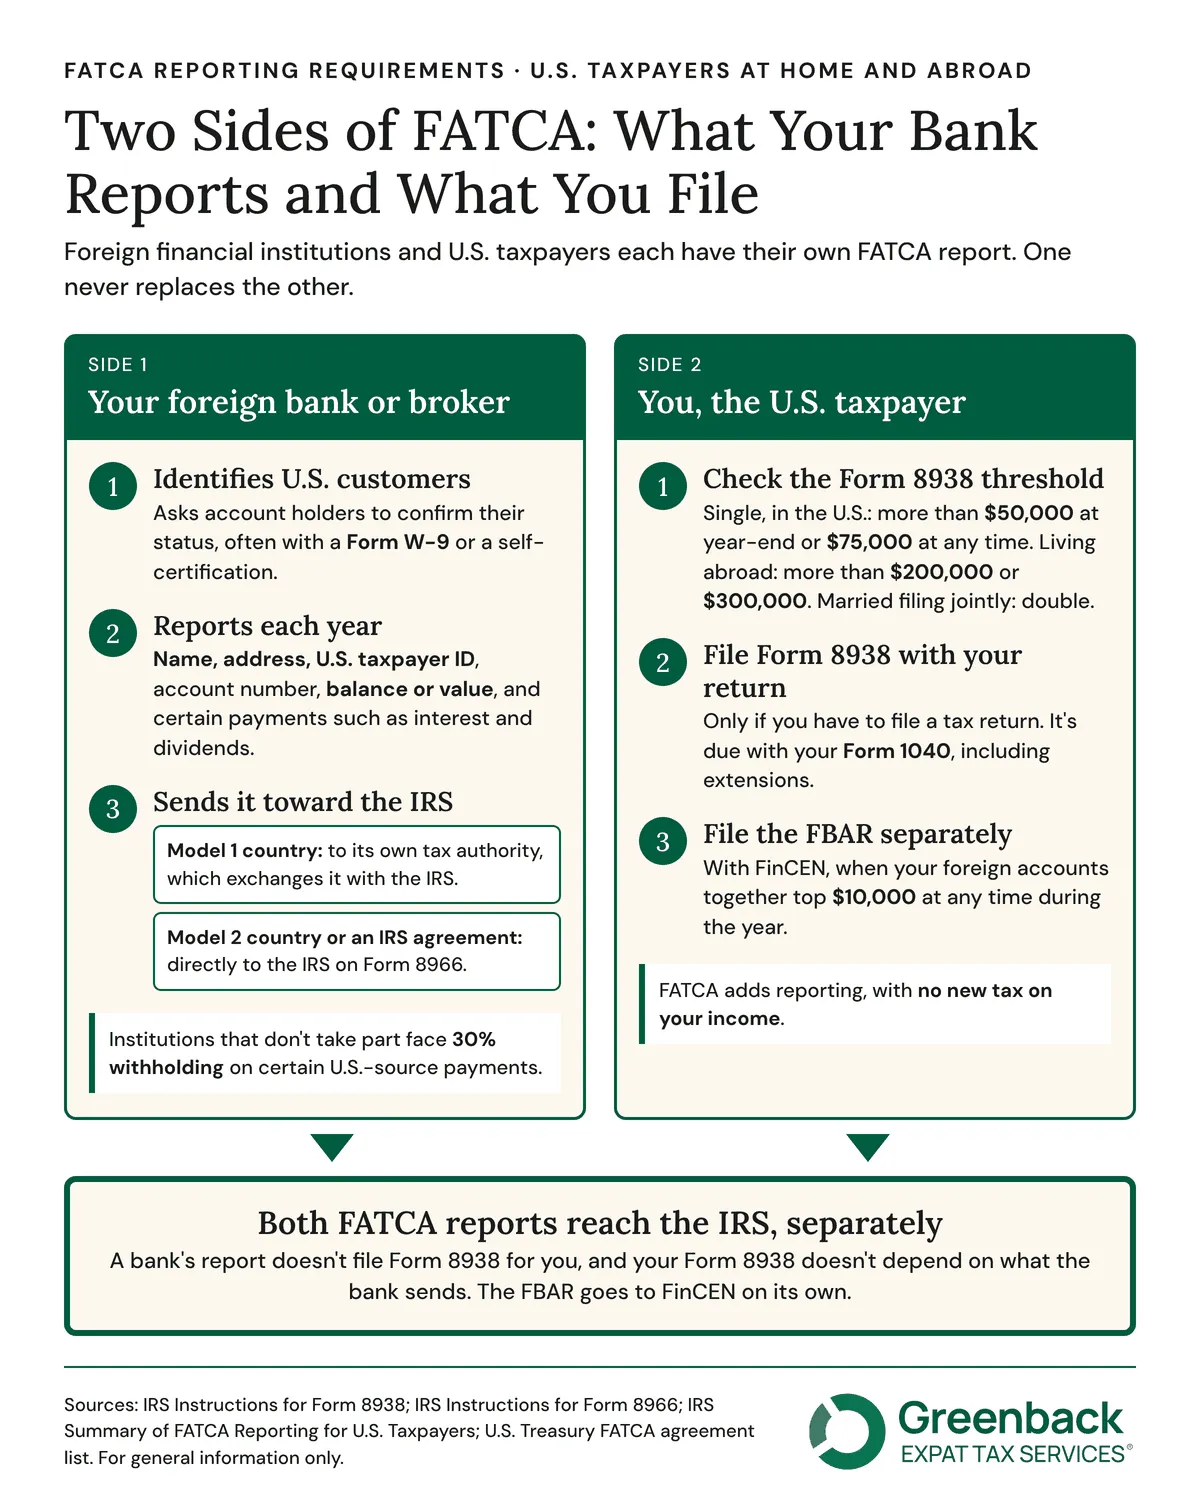
FATCA reporting requirements come from the Foreign Account Tax Compliance Act, a 2010 U.S. law that operates on two fronts: foreign banks report the accounts of their U.S. customers, and U.S. taxpayers with sufficient foreign assets report them on Form 8938 with their tax return. Your FATCA filing requirement starts when your specified foreign financial assets are worth more than $50,000 on the last day of the year, or more than $75,000 at any time during it, if you’re single and live in the U.S. If you live abroad, the line is more than $200,000 at year-end or $300,000 at any time, and married couples filing jointly use double those amounts.
FATCA adds no tax on your income, and if you don’t have to file a tax return, you don’t file Form 8938 at all, whatever your balances. Form 8938 is filed with your return, so for your 2026 tax return, filed in 2027, it’s due on April 15, 2027, or on June 15, 2027, with the automatic extension for Americans abroad; interest runs from April 15 on any tax not paid by then. Foreign banks share U.S. account details under agreements with 114 jurisdictions, and if you missed past years, the usual fix is an amended return with Form 8938 attached.
What Is FATCA?
FATCA, the Foreign Account Tax Compliance Act, is a U.S. law passed in 2010 as part of the HIRE Act. It requires foreign financial institutions to identify and report their U.S. account holders, and it requires U.S. taxpayers whose foreign financial assets pass set thresholds to report those assets to the IRS each year.
The goal was better reporting on money held offshore. Before FATCA, the IRS relied mostly on taxpayers to disclose foreign accounts; now the information also comes from banks. For individuals, FATCA usually means one extra form with the return in years when their assets are above the line, and some paperwork when a bank asks about their citizenship.
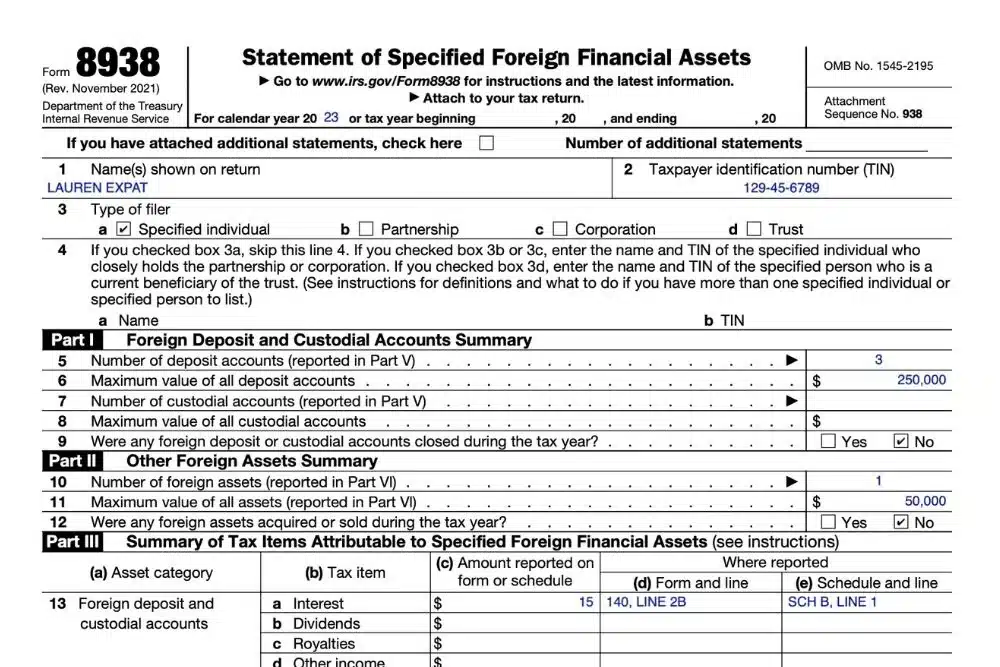
There’s no single “FATCA form.” Individuals file Form 8938, Statement of Specified Foreign Financial Assets, with their Form 1040. Foreign financial institutions file their own report, Form 8966, or send the same information to their local tax authority.
FATCA Works From Two Sides
On one side, your bank reports you: it confirms whether you’re a U.S. person and, if you are, sends your account details each year. On the other side, you report your assets on Form 8938 when they’re over the threshold. The two reports are separate, so a bank’s report doesn’t file anything for you, and your Form 8938 doesn’t depend on whether your bank has reported. The questions Americans abroad most often raise are collected in our look at what Americans abroad ask about FATCA online.
What Are the FATCA Filing Requirements?
The FATCA filing requirement is to report your specified foreign financial assets on Form 8938, attached to your tax return, when their value is over the threshold for your filing status and where you live. For individuals, FATCA requirements apply to U.S. citizens, resident aliens and certain others, and only in a year you have to file a return.
Who Counts as a Specified Individual
The IRS instructions for Form 8938 list four groups:
- U.S. citizens: wherever you live, including dual citizens and Accidental Americans who have U.S. citizenship from birth but have lived abroad most or all of their lives.
- Resident aliens: green card holders and people who meet the substantial presence test, for any part of the tax year. Our guide for new resident aliens covers the first-year return.
- Nonresident aliens who elect resident treatment: usually to file jointly with a U.S. spouse.
- Certain nonresident aliens in U.S. territories: bona fide residents of Puerto Rico or American Samoa.
Certain domestic entities file too. Closely held domestic corporations and partnerships with mostly passive income, and certain domestic trusts, file Form 8938 when they hold specified foreign financial assets over the entity threshold.
A FATCA box checked on a form from a U.S. payer doesn’t, on its own, create a filing requirement. Our article on the FATCA box on a 1099 explains what that checkbox means. Your return also asks about foreign accounts on Schedule B, and our FAQ on answering the Schedule B foreign account question covers what to do if you checked the wrong box.
Form 8938 Thresholds by Filing Status and Residence
| Filing status | Where you live | Last day of the year | Any time during the year |
|---|---|---|---|
| Single or married filing separately | U.S. | More than $50,000 | More than $75,000 |
| Married filing jointly | U.S. | More than $100,000 | More than $150,000 |
| Single or married filing separately | Abroad | More than $200,000 | More than $300,000 |
| Married filing jointly | Abroad | More than $400,000 | More than $600,000 |
You file if you’re over either amount in your row. “Abroad” has a specific meaning: your tax home is in a foreign country, and you meet the bona fide residence test or are present abroad 330 full days in 12 consecutive months. The joint thresholds for living abroad apply even if only one spouse lives abroad, as our FAQ on the threshold for married couples filing jointly abroad explains. Joint filers count a jointly owned asset once; spouses filing separately each count half, and if your spouse isn’t a specified individual, you count the full value.
If you’re over the line, a Greenback accountant can handle your Form 8938 preparation as part of your return.
What Foreign Assets Must I Report Under FATCA?
You report your specified foreign financial assets, which include accounts at foreign financial institutions, foreign stocks and securities you hold directly, interests in foreign
companies, partnerships and trusts, your interest in a foreign pension, and foreign life insurance with a cash value. Our FAQ on which foreign accounts to declare walks through common account types.
For a foreign pension, you report your interest in the pension, not each investment within it, and plans such as a U.K. SIPP can raise more than one reporting question.
Our FAQs on custodial accounts and Form 8938 and Form 3520 cover two more common cases.
Once you have to file, you list every specified foreign financial asset, even small ones. Assets you already report on Forms 3520, 5471, 8621, or 8865 still count toward the threshold, and the Form 8938 guide shows how to list them. Some people and assets fall outside the rules altogether; our guide to FATCA exemptions covers them.
Assets Not Reportable on Form 8938
Some foreign assets stay off Form 8938 and don’t count toward the threshold:
- Foreign real estate you own directly: a home or rental abroad in your own name. If you own it through a foreign company, the company interest is reportable.
- Foreign currency: cash held as currency.
- Foreign social security: government social security benefits from another country.
- Accounts at U.S. financial institutions: IRAs, 401(k)s, U.S. mutual funds and other accounts maintained by a U.S. financial institution, even if they hold foreign investments.
When Is FATCA Due?
The FATCA due date is the due date of your tax return, because Form 8938 is attached to it. For your 2026 tax return, filed in 2027, that’s April 15, 2027. Americans living abroad get an automatic extension to June 15, 2027, by attaching a statement to the return; interest still runs from April 15 on any tax not paid by then. Filing Form 4868 by April 15, or by June 15 if you use the automatic extension, extends the filing deadline to October 15, 2027. Our expat tax deadlines guide lists every date.
Is FATCA the Same as FBAR?
No. The FBAR is a separate report filed with FinCEN, not the IRS, when your foreign accounts together top $10,000 at any time during the year. Many people file both, and our guide to FBAR vs Form 8938 and our FBAR guide explain how each one works.
How Does FATCA Work With Foreign Banks?
Under FATCA, foreign financial institutions identify their U.S. account holders and report them annually, either directly to the IRS or to their own country’s tax authority, which then passes the information to the IRS. Banks, brokerages, investment funds and certain insurance companies all count as foreign financial institutions.
What Banks Send
For each U.S. account, the institution reports the account holder’s name, address, and U.S. taxpayer identification number; the account number; the balance or value; and certain payments, such as interest, dividends, and sale proceeds, according to the IRS instructions for Form 8966. That’s why your bank may ask you for a Form W-9, the form U.S. persons use to certify their status and taxpayer identification number.
Why Banks Take Part
Institutions that don’t take part in FATCA face a 30% withholding tax on certain U.S.-source payments, according to the IRS. Reporting their U.S. account holders is how institutions avoid that withholding. If you recently became a green card holder, our FAQ on when to switch from Form W-8BEN to Form W-9 explains what to give your bank.
Which Countries Have FATCA Agreements?
Countries with a FATCA agreement include the U.K., Canada, Germany, Australia, Japan, and Hong Kong, among 114 jurisdictions that have signed an agreement with the United States or reached one in substance, according to the Treasury. These intergovernmental agreements (IGAs) set how banks in each country send U.S. account information.
Model 1 and Model 2 Agreements
| Agreement | Where the bank reports | How the IRS receives it | Examples |
|---|---|---|---|
| Model 1 | The country’s own tax authority | Government-to-government exchange | The U.K., Germany, Canada, Australia |
| Model 2 | Directly to the IRS | From the institution | Japan, Bermuda, Hong Kong, Austria |
Most partner countries use Model 1. Either way, the same account details reach the IRS.
Institutions in Places Without an Agreement
A foreign institution in a country without an agreement can still take part by signing its own agreement with the IRS and reporting directly; one that doesn’t faces the 30% withholding. FATCA data sharing has also been challenged in court, and our coverage of the European privacy case on FATCA follows its status.
Why Is Your Foreign Bank Asking About Your U.S. Status?
Your bank is asking because FATCA requires it to identify U.S. account holders. A request for a W-9 or a self-certification is routine due diligence, and answering it accurately is the right step. The request itself doesn’t change what you owe; your own Form 8938 and FBAR rules stay the same.
Many countries also share account data with each other under the Common Reporting Standard, a separate international system for exchanging account information. Our FAQ on how the IRS learns about foreign bank accounts explains what information the IRS receives.
What to Do With a FATCA Letter
Confirm your status and send the form the bank asks for. If you’re a U.S. person, that’s usually a W-9 with your Social Security number. If you were born a U.S. citizen abroad and never received a Social Security number, you’ll need to apply for one first. Our FAQ on responding to a FATCA letter goes through each step.
Some Banks Limit Accounts for U.S. Customers
Some foreign banks and brokers decline to serve U.S. customers or limit the products they offer them, often due to the cost of FATCA reporting. Our FAQ on why some foreign banks turn Americans away explains the reasons and what you can do about it.
Recent examples include a European broker that doesn’t accept U.S. clients and Citi account closures for some overseas addresses.
If you’re opening an account abroad, our guides to opening a foreign bank account and opening a Swiss bank account cover what to expect.
What Are the Penalties for FATCA Non-Compliance?
The FATCA penalty for a missed Form 8938 is $10,000, plus $10,000 for each 30-day period you don’t file starting 90 days after an IRS notice, up to $50,000 more. A separate 40% penalty can apply to tax underpaid on income from undisclosed assets. Reasonable cause relief may be available, and you can still catch up on missed years.
Reasonable Cause and the Assessment Period
No penalty applies if the failure was due to reasonable cause and not willful neglect, which the IRS determines on a case-by-case basis. Missing Form 8938 also keeps the assessment period for that return open until three years after you provide the information, and leaving out more than $5,000 of income from a specified foreign financial asset extends it to six years, according to the IRS. A 2026 federal audit of FATCA enforcement looked at how the IRS follows up on missed filings.
How to Catch Up on Missed Years
The fix for a missed Form 8938 is usually an amended return with Form 8938 attached. Which route fits depends on your situation:
- You reported all your income: you can file the missing forms through the IRS delinquent international information return procedures, if you’re not under examination or investigation and the IRS hasn’t contacted you about the missing returns. You can attach a reasonable cause statement, and the IRS may still assess penalties under its usual procedures.
- You also missed income and the failure wasn’t willful: the Streamlined Filing Compliance Procedures allow you to file three years of returns and six years of FBARs, as long as you have no open IRS examination or criminal investigation. Our FAQ on the foreign and domestic versions explains which one applies to you.
- You’re not sure the failure was non-willful: speak with a tax attorney before you file.
Frequently Asked Questions about FATCA
Under FATCA, a foreign bank account worth less than $10,000 goes on Form 8938 only if your total specified foreign financial assets are over your Form 8938 threshold. That threshold starts at more than $50,000 at year-end for single filers living in the U.S. and more than $200,000 for single filers living abroad. Once you’re over it, Form 8938 lists every specified foreign financial asset, including small accounts. The FBAR is a separate report that applies when all your foreign accounts together top $10,000.
FATCA adds no U.S. tax. Form 8938 reports your foreign assets, and any U.S. tax comes from the income those assets earn, such as interest, dividends, and gains, which is generally taxable on your U.S. return. Foreign mutual funds can fall under separate PFIC rules. The Foreign Tax Credit (FTC) can offset U.S. tax with foreign tax paid on that income, while the Foreign Earned Income Exclusion (FEIE) applies only to earned income, such as wages.
No, FATCA and the Common Reporting Standard (CRS) are separate systems. FATCA is a U.S. law that requires foreign financial institutions to report U.S. account holders to the IRS. CRS is a framework developed by the OECD that many other countries use to exchange account information with each other. A foreign bank may ask about your tax residence for both.
A checked FATCA filing requirement box on a Form 1099 indicates the payer is using that Form 1099 to satisfy its own FATCA reporting requirements for the account. The box doesn’t, on its own, mean you have to file Form 8938. Your FATCA filing requirement depends on your specified foreign financial assets and the Form 8938 thresholds for your filing status and where you live.
No, closing a foreign account doesn’t remove FATCA reporting for past years. If your specified foreign financial assets were over the Form 8938 threshold in a year you didn’t file, that year still needs Form 8938, usually through an amended return on Form 1040-X with Form 8938 attached. Closing an account affects FATCA reporting only for years after it’s closed.
Your Own Foreign Assets Decide Whether You File Form 8938
FATCA puts two reports side by side: one from your bank and one from you. Whether you file Form 8938 depends on your balances, your filing status, and where you live; for Americans living abroad, the threshold starts at more than $200,000 at year-end.
If you’re a U.S. citizen living abroad with accounts where you live, Form 8938 and the FBAR can be prepared together with your return. Learn more about how we help U.S. citizens living abroad. If you’re a dual citizen, a retiree with a foreign pension, a green card holder with accounts back home, or a late filer catching up, you can have a Greenback accountant prepare your Form 8938 along with the rest of your return.

Ready to Get Your Foreign Reporting Current?
This article is for general informational purposes only and does not constitute legal, tax, or financial advice. Tax laws, thresholds, and IRS guidance change, and the rules that apply to you depend on your specific facts and circumstances. Greenback Expat Tax Services has deep expertise in U.S. tax filing for Americans at home and abroad.
Featured In