Filing U.S. Taxes If Your Foreign Spouse Lacks an SSN or ITIN

- What Are Your Filing Options When Your Spouse Has No SSN or ITIN?
- Can You File Jointly If Your Spouse Has No SSN or ITIN?
- How Do You Get an ITIN for Your Spouse?
- How Does Married Filing Separately Work Without a Spouse's ITIN?
- Can You File as Head of Household Instead?
- How Do You Choose the Right Filing Status?
- Does Your Filing Status Change FBAR and Form 8938?
- Frequently Asked Questions about Filing With a Foreign Spouse
- A Spouse Without an SSN or ITIN Doesn't Stop You From Filing
If you’re a U.S. citizen or resident married to a foreign spouse who does not have an SSN or ITIN, you can still file your U.S. tax return. You have three options: You can file married filing separately, report only your own income, and write “NRA” (short for nonresident alien) where your spouse’s SSN would go. You can file jointly by applying for your spouse’s ITIN with Form W-7 and attaching a statement, signed by both of you, that treats your spouse as a U.S. resident for income tax. Or you can file as head of household if you support a qualifying child or relative. For a joint return, the IRS assigns your spouse an ITIN before it processes the return.
For your 2026 tax return, filed in 2027, filing jointly with a spouse who has no SSN or ITIN brings a $32,200 standard deduction and your spouse’s worldwide income onto your return, while a separate return keeps your spouse’s income off it with a $16,100 deduction. Which way works better depends on both of your incomes and where you live.
What Are Your Filing Options When Your Spouse Has No SSN or ITIN?
When your spouse is a nonresident alien with no SSN or ITIN, you can file married filing jointly with the election, married filing separately, or head of household if you have a qualifying child or dependent relative.
| Filing status | Spouse’s ID number | How you file | 2026 standard deduction |
|---|---|---|---|
| Married filing jointly (with the election) | ITIN, applied for with Form W-7 attached to the return | Paper return when Form W-7 is attached | $32,200 |
| Married filing separately | None; enter “NRA” | E-file or paper | $16,100 |
| Head of household (if you qualify) | None needed for your spouse | E-file or paper | $24,150 |
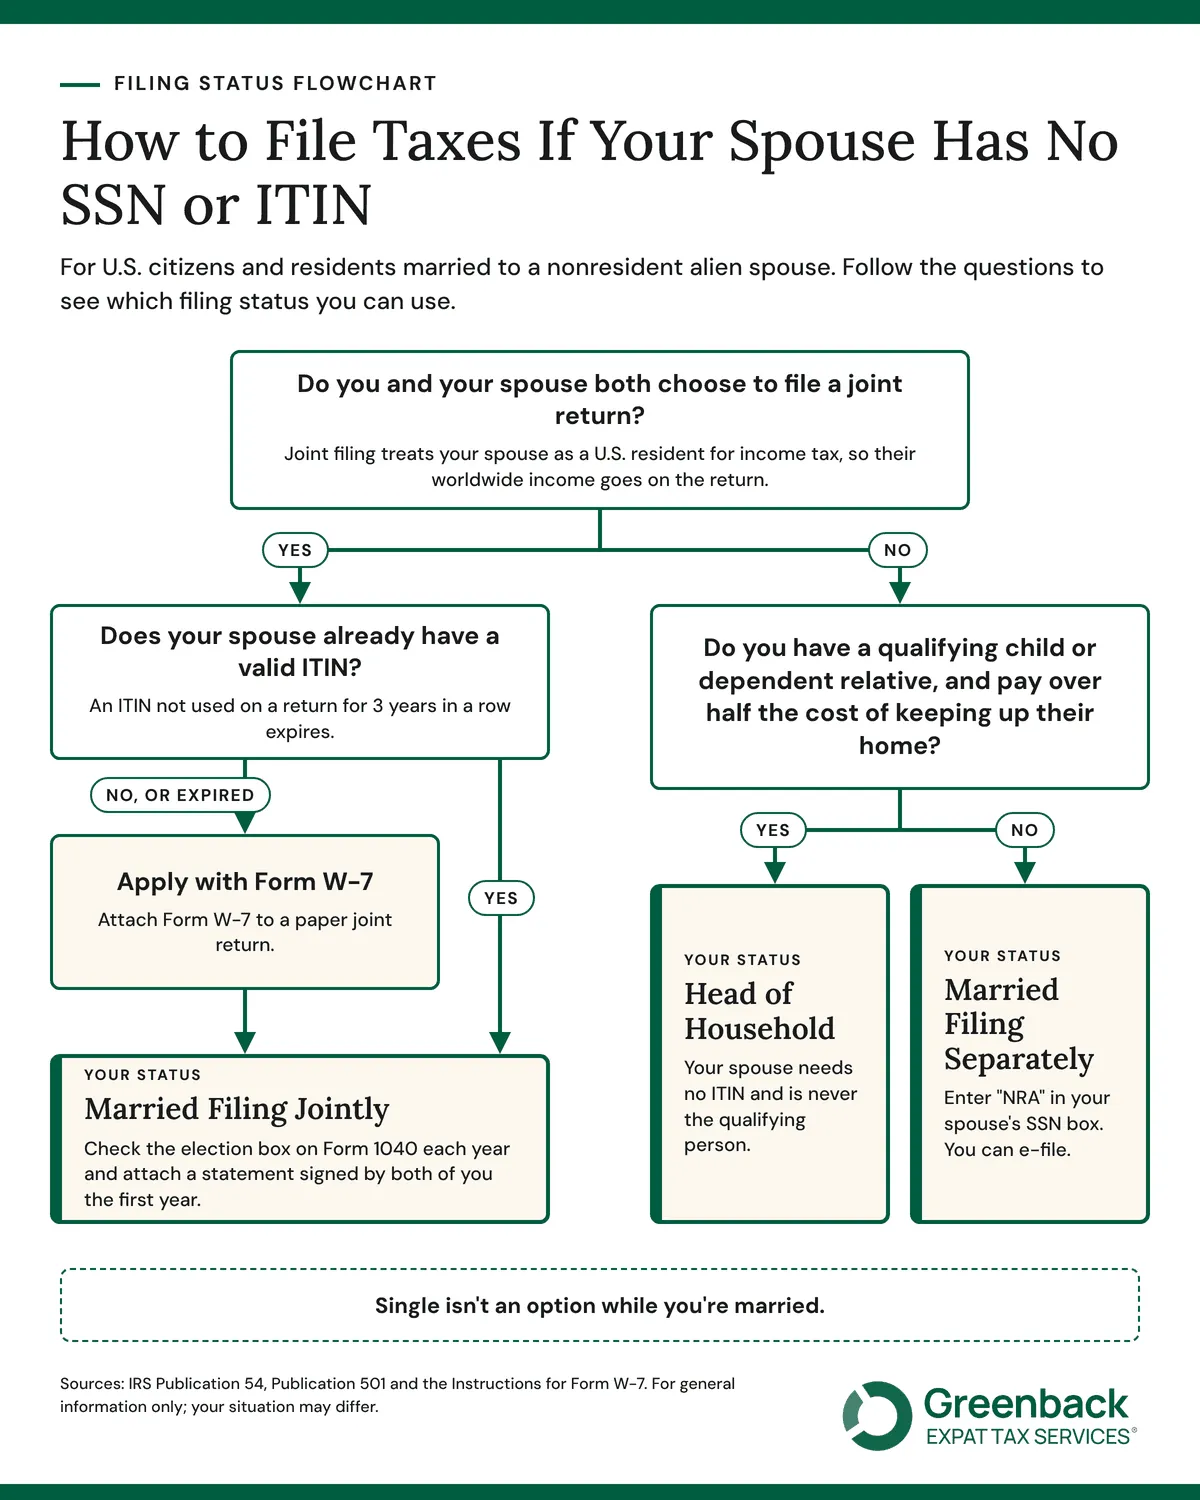
Our FAQs on whether your non-citizen spouse goes on your U.S. return, filing without a Social Security number and the differences between a TIN, SSN and ITIN answer the narrower questions.
Can You File Jointly If Your Spouse Has No SSN or ITIN?
Yes, you can file jointly with a spouse who has no SSN or ITIN if you both choose to treat your spouse as a U.S. resident for the whole year, and you apply for your spouse’s ITIN with the return. The choice is often called the 6013(g) election, after the section of the tax code that allows it.
You Both Choose to Treat Your Spouse as a U.S. Resident
You make the choice by checking the box for it in the filing status section of Form 1040, each year it applies, and attaching a statement signed by both of you to the first joint return. The statement declares your status at year-end and your choice of resident treatment for the whole year, as the IRS explains.
The election treats your spouse as a U.S. resident for income tax only. It doesn’t change your spouse’s immigration status. It carries over into every later year until one of you revokes it or it ends another way. Once it ends, the two of you can’t make it again, so it’s worth deciding together with a preparer. Our FAQ on how the Section 6013(g) election works covers revoking and ending it.
Your Spouse’s Income Is Reported and Can Be Offset
On a joint return, your spouse’s worldwide income goes on your U.S. return, and the same foreign income relief open to you is open to your spouse. If your spouse works abroad, they can claim the Foreign Earned Income Exclusion (FEIE) of up to $132,900 for 2026 under the physical presence test, or under the bona fide residence test if they’re a citizen or national of a country with a U.S. income tax treaty. Our FAQ on whether both spouses can claim the full FEIE explains how the two exclusions combine. Foreign income tax your spouse pays can count toward the Foreign Tax Credit (FTC).
By default, only your own investment income counts for the Net Investment Income Tax, at the $125,000 separate-filer threshold, unless you make a second election.
How Do You Get an ITIN for Your Spouse?
To get an ITIN for your spouse, complete Form W-7, attach it to the front of your paper joint return with your spouse’s identity documents, and mail the package to the IRS, or submit it through a Certifying Acceptance Agent. There is no separate online application.
1. Complete Form W-7 and Gather Documents
On Form W-7, your spouse checks the reason for a spouse of a U.S. citizen or resident. A valid passport is the only document that proves both identity and foreign status on its own. Without one, your spouse needs other documents from the IRS list, such as a national ID card and a birth certificate. Documents must be originals or copies certified by the issuing agency; notarized copies aren’t accepted, according to the IRS instructions for Form W-7.
2. Submit It With Your Return or Through a Certifying Acceptance Agent
You can mail the package to the Internal Revenue Service, ITIN Operation, P.O. Box 149342, Austin, TX 78714-9342, and your spouse’s original documents will be returned by mail. A Certifying Acceptance Agent verifies the documents and submits the application, so the passport stays with your spouse. Our guide to what an ITIN costs compares applying yourself with using an agent.
What Happens While the ITIN Is Processed
The IRS usually issues an ITIN in about 7 weeks, or 9 to 11 weeks if you apply between January 15 and April 30 or from outside the U.S., and then processes your return, so any refund waits until then. Because the joint return goes by mail, allow time: Americans abroad get an automatic extension to June 15 to file and pay, and interest runs from April 15 on any tax not paid by then. Form 4868 extends filing to October 15.
If the IRS needs more information, it sends a CP566 notice, and you have 45 days to reply. If it rejects the application, it sends a CP567 notice and processes your return without the ITIN. Your spouse can then send a new, complete Form W-7 with the required documents and a copy of the return. Children who need an ITIN use the same Form W-7 process. An ITIN qualifies a child for the Credit for Other Dependents, while the Child Tax Credit needs an SSN, as our FAQ on the Child Tax Credit with an ITIN vs. an SSN explains. If your spouse already has an ITIN, check that it hasn’t expired before you file.
How Does Married Filing Separately Work Without a Spouse’s ITIN?
When filing separately without an ITIN for your spouse, enter “NRA” (nonresident alien) in your spouse’s SSN box, and report only your own income. Your spouse doesn’t file a U.S. return unless they have U.S. income of their own, following the rules for how nonresident aliens are taxed, in which case they may need Form 1040-NR.
You can e-file a separate return with “NRA” in the spouse box. Your standard deduction is $16,100 for 2026, and the brackets are narrower: the 24% rate starts at $105,700 of taxable income on a separate return, compared with $211,400 on a joint return. Separate filers also can’t take education credits or the student loan interest deduction, and they can claim the Earned Income Tax Credit only in narrow cases.
You can switch to a joint return later by filing an amended joint return, Form 1040-X, with Form W-7 and the election statement attached, on paper, within 3 years of the original due date, not counting extensions. You also amend any later years either of you has already filed.
Can You File as Head of Household Instead?
You may be able to file as head of household if your spouse is a nonresident alien and you don’t choose joint filing, because the IRS then considers you unmarried for this status. Your spouse can’t be the person who qualifies you, and a spouse is never a dependent.
You need a qualifying child or a dependent relative, such as a parent, and you must pay more than half the cost of keeping up a home that was your qualifying child’s main home for more than half the year, or your dependent parent’s main home for the whole year. A dependent parent doesn’t have to live with you, and the home can be outside the U.S. A qualifying child generally must be a U.S. citizen, U.S. national, or U.S. resident, so a non-citizen stepchild living abroad usually won’t qualify. A legally adopted child who lives with you as a member of your household for the whole year can.
Filing as single isn’t an option while you’re married. If you don’t qualify for head of household and don’t choose joint filing, your status is married filing separately.
How Do You Choose the Right Filing Status?
The right filing status depends on how much your spouse earns, where they pay tax, and what they own. Run your return both ways before you elect, because the election carries forward.
| Your situation | What goes on your U.S. return | What can offset it | Extra forms to expect |
|---|---|---|---|
| Spouse has no income | Your income only, either way | Standard deduction of $32,200 joint, $24,150 head of household or $16,100 separate | Form W-7 if filing jointly |
| Both of you earn in a country with high income tax | Both incomes if joint; yours if separate | FEIE for each working spouse, Foreign Tax Credit | Form 2555 for each spouse claiming the FEIE, Form 1116 for the credit |
| Spouse earns a large income in a lower-tax country | Both incomes if joint; yours if separate | FEIE for your spouse’s earned income; little foreign tax to credit | Form 2555 for your spouse |
| Spouse owns foreign funds or a company | Your spouse’s investment income if joint; none if separate | Foreign Tax Credit on any foreign tax paid | Possibly Form 8621 or Form 5471 |
| You have a qualifying child and don’t elect | Your income only | Head of household deduction of $24,150 | None for your spouse |
Our guides to the FEIE vs. the Foreign Tax Credit and avoiding double taxation explain the offsets. A spouse who moved to the U.S. during the year has a dual-status year, and the primary taxpayer on a joint return is a separate choice. Marriage to a non-citizen also shapes gifts, estates, and benefits, covered in our guides to estate planning with a nonresident alien spouse and Social Security for a non-U.S. spouse.
Does Your Filing Status Change FBAR and Form 8938?
Your FBAR depends only on the accounts you own or can sign on to, so your filing status doesn’t affect it. You report every foreign account you own or have signature authority over, including joint accounts with your spouse, at the full balance, once the total tops $10,000 at any time in the year. The election alone doesn’t make your spouse a U.S. person for the FBAR, so your spouse generally doesn’t file one. Our guide to FBAR filing for a joint account with a non-U.S. citizen covers how to list your spouse.
Form 8938 does follow your filing status. Americans abroad file it when foreign financial assets top $400,000 at year-end or $600,000 at any time on a joint return, or $200,000 and $300,000 on any other return, including married filing separately and head of household. An electing spouse counts for Form 8938, so your spouse’s foreign assets count toward the joint threshold. Our FAQ on the FATCA threshold for married couples filing jointly abroad walks through examples.
Frequently Asked Questions about Filing With a Foreign Spouse
A foreign spouse who is a nonresident alien pays U.S. tax only on U.S.-source income, unless the couple chooses to file jointly. With the joint filing election, the spouse’s worldwide income is reported on the U.S. return, and the Foreign Earned Income Exclusion and Foreign Tax Credit can offset the tax on it.
No. A spouse is never a dependent on a U.S. tax return, whether she lives in the U.S. or overseas. A U.S. citizen married to a nonresident alien wife can file jointly by treating her as a U.S. resident and obtaining an ITIN for her, or file separately with “NRA” in the spouse box. Head of household is also possible with a qualifying child or relative.
A U.S. citizen whose husband lives in another country and isn’t a U.S. citizen or resident can e-file a separate return with “NRA” in the spouse box, or mail a joint return with Form W-7 for the husband’s ITIN and a signed election statement. The return is due on April 15, or on June 15 if the U.S. citizen also lives abroad, with interest accruing from April 15 on any unpaid tax.
Yes, a married filing separately return can be e-filed with “NRA” entered for a spouse who has no SSN or ITIN. A joint return that includes a Form W-7 application for the spouse’s ITIN must be mailed to the IRS on paper.
A Spouse Without an SSN or ITIN Doesn’t Stop You From Filing
Every couple in this situation has a clear way to file: jointly with Form W-7 and the election statement on a paper return; separately by e-file with “NRA”; or as head of household with a qualifying child or relative. Your spouse’s income, the foreign tax you both pay, and what your spouse owns determine which filing method applies, and the joint election stays in effect until it’s revoked or ends.
Greenback is an IRS Certifying Acceptance Agent, so our U.S. accountants can run your return both ways, handle your spouse’s Form W-7 with it, and help you file with confidence.
If you’re a U.S. citizen living abroad with a non-citizen spouse, Greenback can prepare your return and your spouse’s ITIN application together. Learn more about tax help for U.S. citizens living abroad. If your spouse is moving to the U.S. on a visa or green card, Greenback can help with the year of arrival and beyond. Learn more about tax help for visa and green card holders and dual-status filers.

File With Your Foreign Spouse With Confidence
This article provides general information about U.S. tax filing for Americans married to a nonresident alien spouse for the 2026 tax year, filed in 2027. It is not tax or legal advice. Your situation may differ, so speak with a qualified tax professional before making the joint filing election.

Featured In


