Do Expats Get Social Security Benefits? What Changes When You Move Abroad

- Do You Lose Social Security Benefits If You Move to Another Country?
- How Long Can You Stay Abroad and Keep Your Benefits?
- What Can Pause Your Payments While You Live Abroad?
- How Do You Apply for Social Security and Get Paid From Abroad?
- Is Social Security Taxed If You Live Abroad?
- Can You Collect Social Security From Two Countries?
- What Should You Set Up Before and After You Move Abroad?
- Frequently Asked Questions about Social Security for Expats
- Greenback Reports Your Social Security Correctly, Wherever You Retire
Yes, expats get Social Security. U.S. citizens continue to receive Social Security retirement, survivor, and disability benefits in nearly every country, and moving abroad does not reduce or stop these payments. The only places the Social Security Administration (SSA) cannot pay are Cuba and North Korea. The six-month cutoff you may have read about applies to non-citizens, not to U.S. citizens.
What changes when you live abroad is the tax on your benefits. Up to 85% of your benefits can be taxable on your U.S. return, and the Foreign Earned Income Exclusion (FEIE) cannot exclude them, because Social Security is not earned income. If you are 65 or older, you can file that return on Form 1040-SR, the senior version of Form 1040 with larger print and a built-in standard deduction chart. U.S. citizens living in seven treaty countries, including the UK, Canada, and Germany, owe no U.S. tax on their benefits, and Italy joins that list for dual citizens. SSA has also announced a 3.6% cost-of-living adjustment for benefits paid from January 2027. For the full picture of how filing works from overseas, see our guides to U.S. expat taxes and taxes for U.S. citizens abroad.
Do You Lose Social Security Benefits If You Move to Another Country?
No. A U.S. citizen does not lose Social Security benefits by moving to another country. Your retirement, survivor, or disability payments continue for as long as you stay eligible, wherever you live, with two exceptions: SSA cannot send money at all, and seven countries impose conditions. Your benefit amount does not change because you moved, and it still rises each January with the same cost-of-living adjustment paid at home.
SSA Cannot Pay in Cuba or North Korea
Treasury rules bar payments to people living in Cuba and North Korea. If you live in either country, SSA holds the payments. If you are a U.S. citizen and later move to a country where SSA can pay, you receive the withheld months, as long as you were eligible during that time. Non-citizens do not.
Seven Countries Carry Payment Restrictions
SSA restricts payments to residents of Azerbaijan, Belarus, Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan, and Uzbekistan. Payments there are possible only when you meet extra conditions, which SSA explains country by country. Before you commit to a move, run your destination through SSA’s Payments Abroad Screening Tool, which tells you whether payments continue, stop, or need extra steps.
How Long Can You Stay Abroad and Keep Your Benefits?
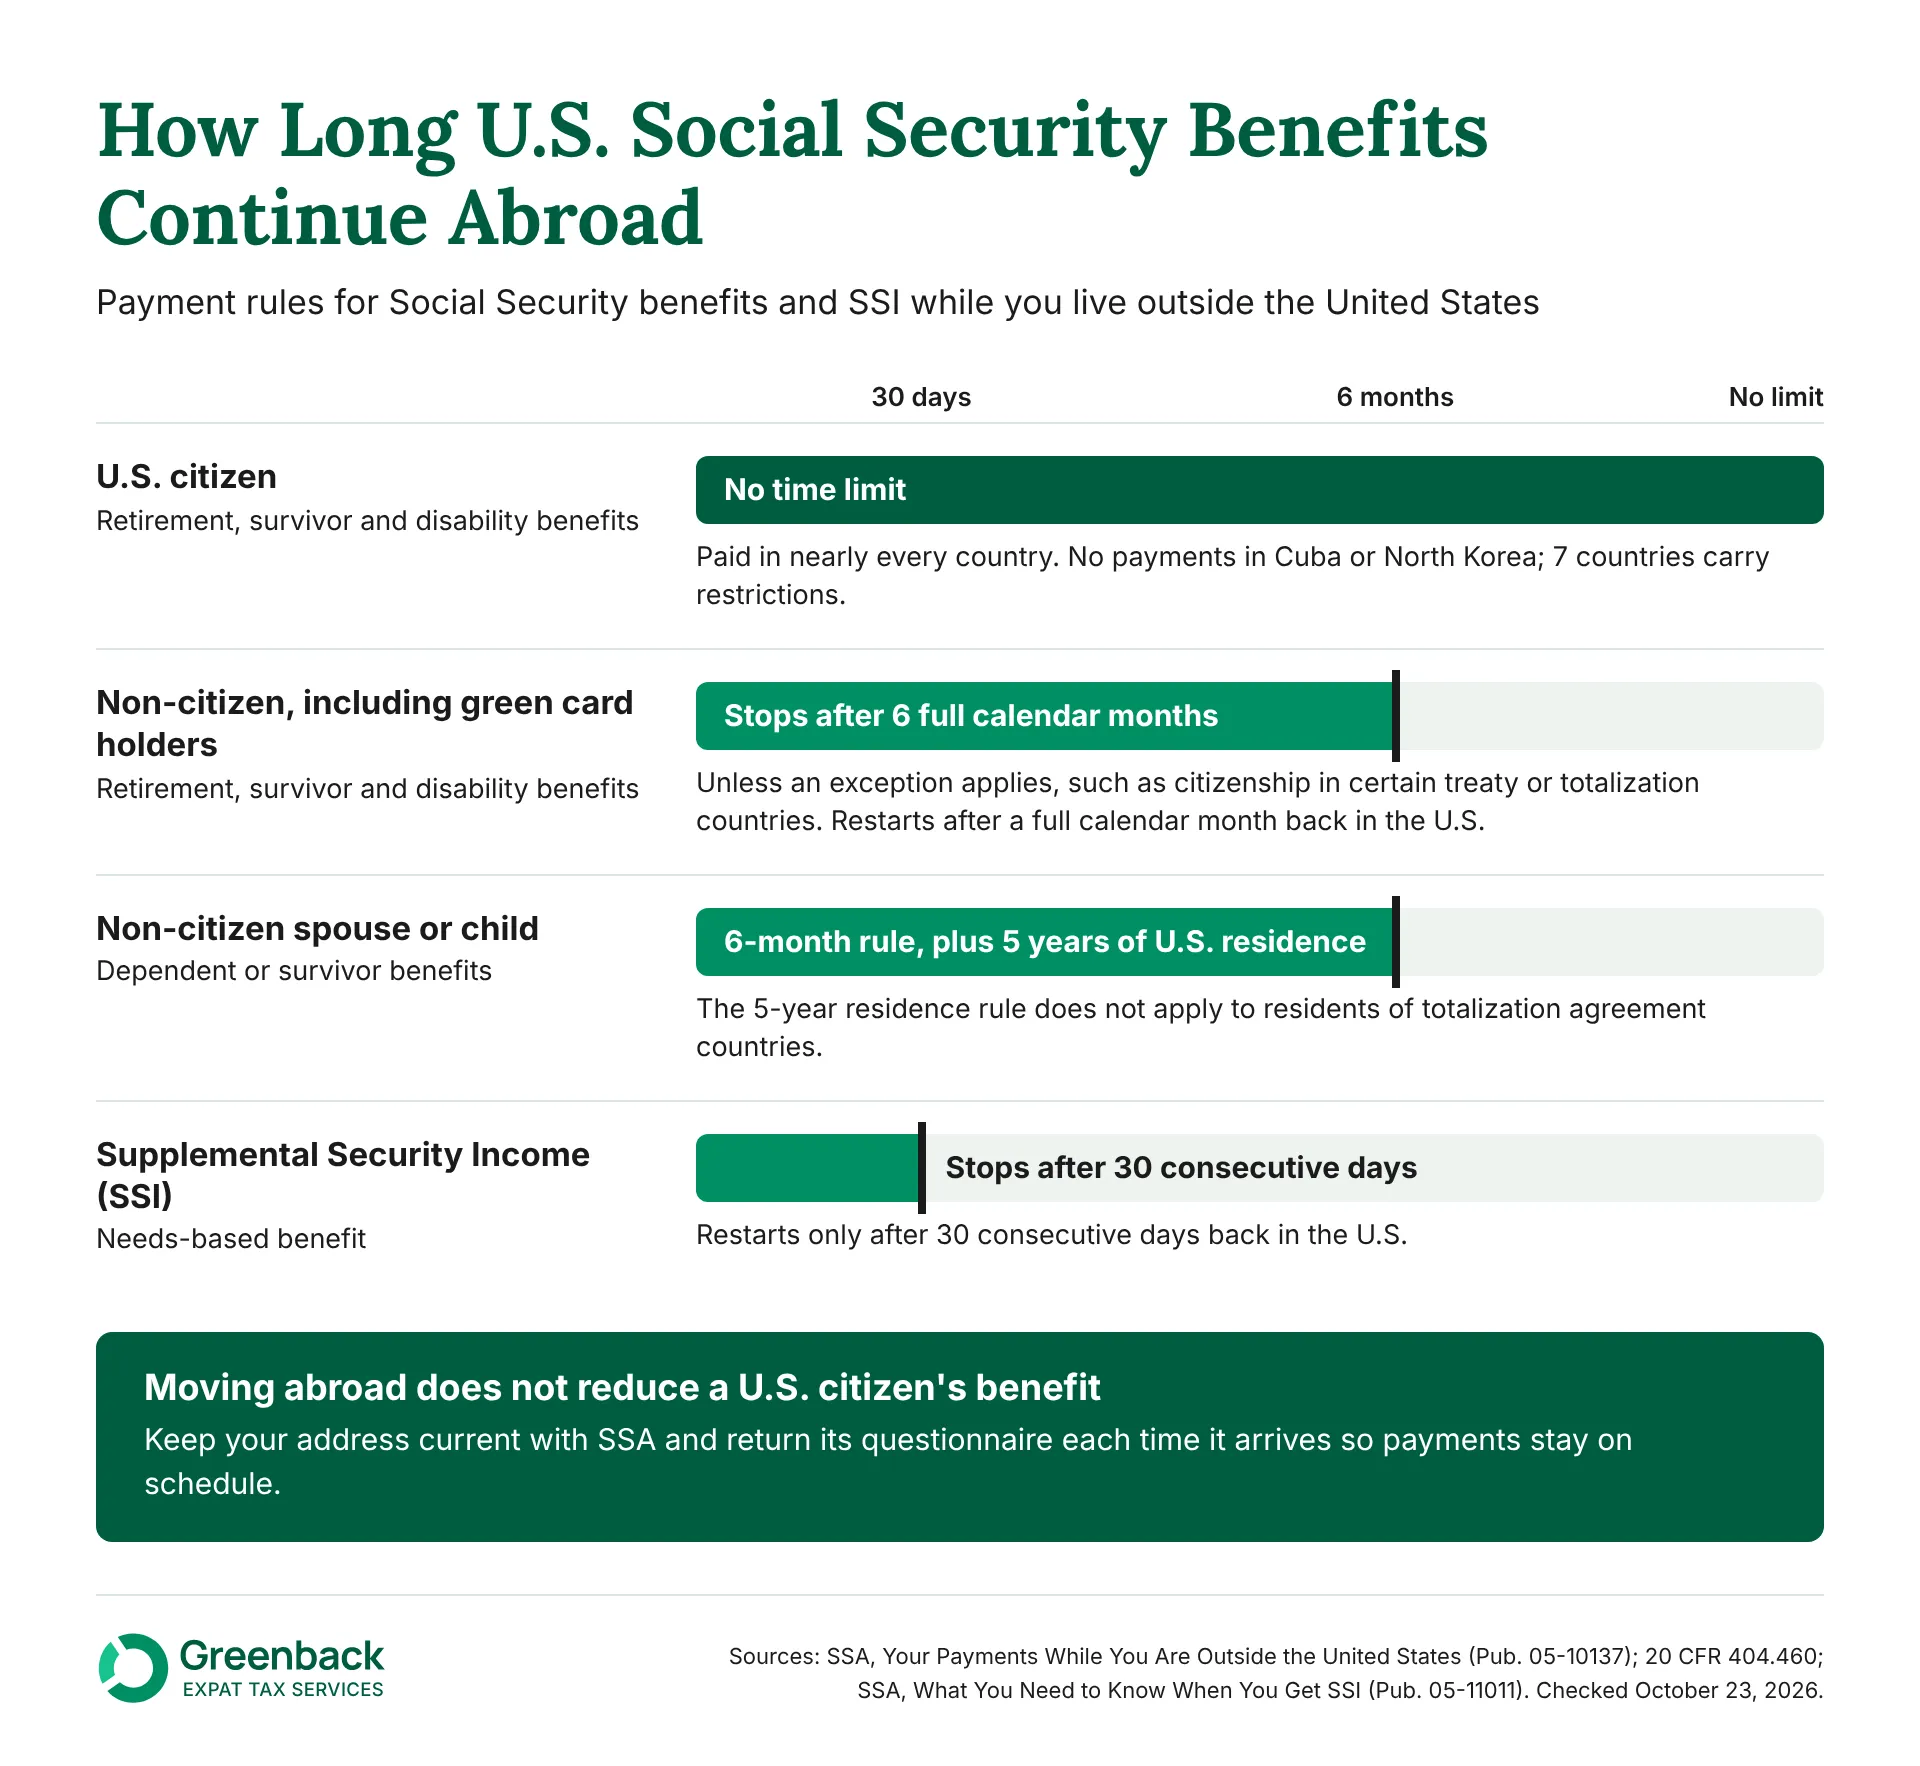
U.S. citizens can stay abroad indefinitely and keep their Social Security benefits. Non-citizens, including green card holders, generally lose payments after six full calendar months outside the U.S. unless an exception applies. Supplemental Security Income (SSI) has the shortest limit of all: it stops after 30 consecutive days abroad. How long you can stay depends on your citizenship and the type of benefit you receive.
U.S. Citizens Have No Time Limit
As a U.S. citizen, your retirement, survivor, and disability benefits continue no matter how many years you live outside the U.S., subject only to the country rules above. You can visit, move between countries, or settle permanently abroad without a cutoff date.
Non-Citizens Face a Six-Month Rule
If you are not a U.S. citizen, payments stop after you have been outside the U.S. for six full calendar months in a row under SSA rules, unless an exception applies. Common exceptions include citizenship in a country that has a totalization agreement or a qualifying social insurance arrangement with the U.S., and active U.S. military service. Payments restart once you return to the U.S. and stay for a full calendar month. SSA’s Payments Abroad Screening Tool checks the exceptions for your citizenship and country.
Spouses and Children Who Are Not Citizens Need U.S. Residence
A non-citizen spouse, child, or survivor collecting on your record faces one more test. They generally need to have lived in the U.S. for at least five years while in the family relationship to keep dependent or survivor benefits abroad. Residents of countries with totalization agreements are exempt from this rule. The exceptions are listed in our guide on Social Security for a non-U.S. spouse.
Disability Benefits Continue Abroad, but SSI Does Not
Social Security Disability Insurance (SSDI) is a work-based benefit, so U.S. citizens can collect SSDI while living abroad under the same country rules as retirement benefits. SSI is a needs-based program, and SSI stops after 30 consecutive days outside the U.S. It restarts only after you spend 30 consecutive days back in the country.
What Can Pause Your Payments While You Live Abroad?
Social Security payments can pause while you live abroad if you work before full retirement age, leave an SSA questionnaire unanswered, or move to a restricted country. An unreported life change can also leave you repaying an overpayment later. Your underlying benefit amount stays the same in every case.
1. Working Before Full Retirement Age Can Withhold Payments
If you are under full retirement age (67 for anyone born in 1960 or later) and work abroad in a job not covered by U.S. Social Security, the foreign work test applies. SSA withholds your benefit for any month in which you work more than 45 hours, regardless of how much you earn. Self-employment abroad counts toward those hours even if the business shows no profit that month.
Work covered by U.S. Social Security follows the annual earnings test instead. In 2026, SSA withholds $1 for every $2 you earn above $24,480, or $1 for every $3 above $65,160 in the year you reach full retirement age. The test ends the month you reach full retirement age.
2. Unanswered SSA Questionnaires Can Suspend Payments
SSA mails a questionnaire to beneficiaries abroad to confirm you are alive, still eligible, and living at the address on file. Returning it on time keeps your payments on schedule, and keeping your address current with the SSA ensures it reaches you.
3. Unreported Changes Can Lead to Overpayments
Tell SSA promptly if you marry, divorce, start working, move to another country, or if a beneficiary on your record dies. Unreported changes can lead to overpayments that SSA later asks you to repay.
4. Moving to a Restricted Country Pauses Payments
A move to Cuba, North Korea, or one of the seven restricted countries listed above changes what SSA can pay, so check the SSA Payments Abroad Screening Tool before any move between countries, not only before your first one.
How Do You Apply for Social Security and Get Paid From Abroad?
You can apply for Social Security retirement benefits online from anywhere in the world, up to four months before you want payments to start. Once approved, you receive payments by direct deposit to a U.S. bank account or, in many countries, to a local bank account. SSA’s Federal Benefits Units at U.S. embassies handle in-person questions abroad.
1. Set Up Your my Social Security Account
Your my Social Security account lets you check your earnings record, download benefit letters, and change your payment details. With a foreign address, SSA routes sign-in through ID.me, so set up or update the account before you move, while your U.S. details are still current. Our guide on getting a Social Security card while living abroad covers the card side.
2. Apply Online Up to Four Months Before Benefits Start
Apply through your my Social Security account or SSA’s online application, as early as four months before the month you want payments to begin. Have your proof of age, proof of U.S. citizenship or lawful status, your most recent W-2 or self-employment tax return, and your bank details ready. If you cannot complete the application online, the Federal Benefits Unit serving your country can complete it.
3. Choose How You Get Paid
Treasury is phasing out paper checks under Executive Order 14247, so plan for electronic payments from the start. You have two options:
- A U.S. bank account: Payments arrive on the same schedule as they would at home, and you move money abroad yourself.
- International direct deposit: Available in countries with an SSA direct deposit arrangement, set up with Form SSA-1199. Our FAQ on receiving Social Security in a foreign bank account covers how it works.
Benefits are calculated and paid in U.S. dollars, so the amount that lands in your local currency rises and falls with exchange rates. If your benefits go into a foreign account and your foreign accounts together top $10,000 at any point in the year, you also file an FBAR.
Is Social Security Taxed If You Live Abroad?
Yes, for most U.S. citizens. Up to 85% of your Social Security benefits can be taxable on your U.S. Form 1040, wherever you live, and the FEIE does not apply because benefits are not earned income. Some tax treaties shift the tax to your country of residence instead, and where both countries can tax, the treaty’s double-tax relief rules decide how the overlap is handled.
Combined income is your adjusted gross income, plus nontaxable interest, plus half of your Social Security benefits. Benefits become taxable once combined income exceeds $25,000 for single filers or $32,000 for married couples filing jointly. Married people who file separately and lived with their spouse during the year have a base amount of $0.
Federal tax is only part of it. If you keep ties to a U.S. state, that state may still treat you as a resident and tax your income, as our guide to state taxes for expats explains.
If you are 65 or older, a new senior deduction can lower the tax further, according to the IRS: an extra $6,000 per eligible person for 2025 through 2028, phasing out above $75,000 of modified adjusted gross income ($150,000 for joint filers), and requiring a valid Social Security number on the return. Our guide on the new tax law and Social Security for expats explains who qualifies.
Tax Treaties Decide Which Country Taxes Your Benefits
Most U.S. tax treaties allow the U.S. to continue taxing its own citizens, but several carve out Social Security. IRS Publication 915 lists seven countries, plus Italy for dual citizens, where U.S. citizens living there owe no U.S. tax on their benefits.
| Where you live | Who taxes U.S. Social Security paid to a U.S. citizen | What it means for you |
|---|---|---|
| Canada, Egypt, Germany, Ireland, Israel, Romania, United Kingdom | Your country of residence only | No U.S. tax on your benefits |
| Italy | Italy only, if you are also an Italian citizen | Without Italian citizenship, U.S. tax applies |
| France, Mexico | The U.S. only | Your country of residence does not tax them under the treaty |
| Spain, Portugal | Both countries may tax | The treaty’s double-tax relief rules help keep you from paying twice |
| Countries without a U.S. income tax treaty | Both countries may tax | Relief usually comes from your country of residence, because U.S. Social Security is U.S.-source income |
The Foreign Tax Credit (FTC) generally applies only to foreign-source income, so it rarely offsets U.S. tax on U.S. Social Security. Our FAQ on tax treaties, Social Security, and Medicare covers more treaty detail. For the residence-country side, our guides to double taxation, and the best countries for tax-friendly retirement cover how each country treats your income.
Non-Citizen Recipients Have Tax Withheld at the Source
If you are a nonresident alien, the U.S. taxes 85% of your benefits at a flat 30% rate, which works out to 25.5% withheld from each payment, unless a treaty lowers or removes it. You receive Form SSA-1042S each year instead of the SSA-1099 that U.S. citizens and residents get, and if you have other U.S. income, you may need to file Form 1040-NR.
Can You Collect Social Security From Two Countries?
Yes. If you have work history in the U.S. and in a country with a U.S. totalization agreement, you may qualify for benefits from both, and each country pays its own share based on your work there. When you lack enough credits in one system, the agreement lets you combine work periods to qualify, as long as you generally have at least six U.S. credits.
The U.S. has 31 totalization agreements in force, with Romania the newest as of September 1, 2026, according to SSA. Our FAQ on receiving Social Security from two countries explains how the two payments interact. Our guide to totalization agreements lists every country, and our FAQ on combining foreign and U.S. work credits covers how the math works.
A Foreign Pension No Longer Reduces Your U.S. Benefit
The Social Security Fairness Act, signed on January 5, 2025, repealed the Windfall Elimination Provision (WEP) and the Government Pension Offset (GPO) for benefits payable after December 2023, as SSA explains. A pension from foreign work that did not pay into U.S. Social Security no longer reduces your U.S. benefit. See our article on the Social Security Fairness Act for what changed and how back payments were handled, and our guide to foreign pensions and U.S. taxes for how that pension is reported.
What Should You Set Up Before and After You Move Abroad?
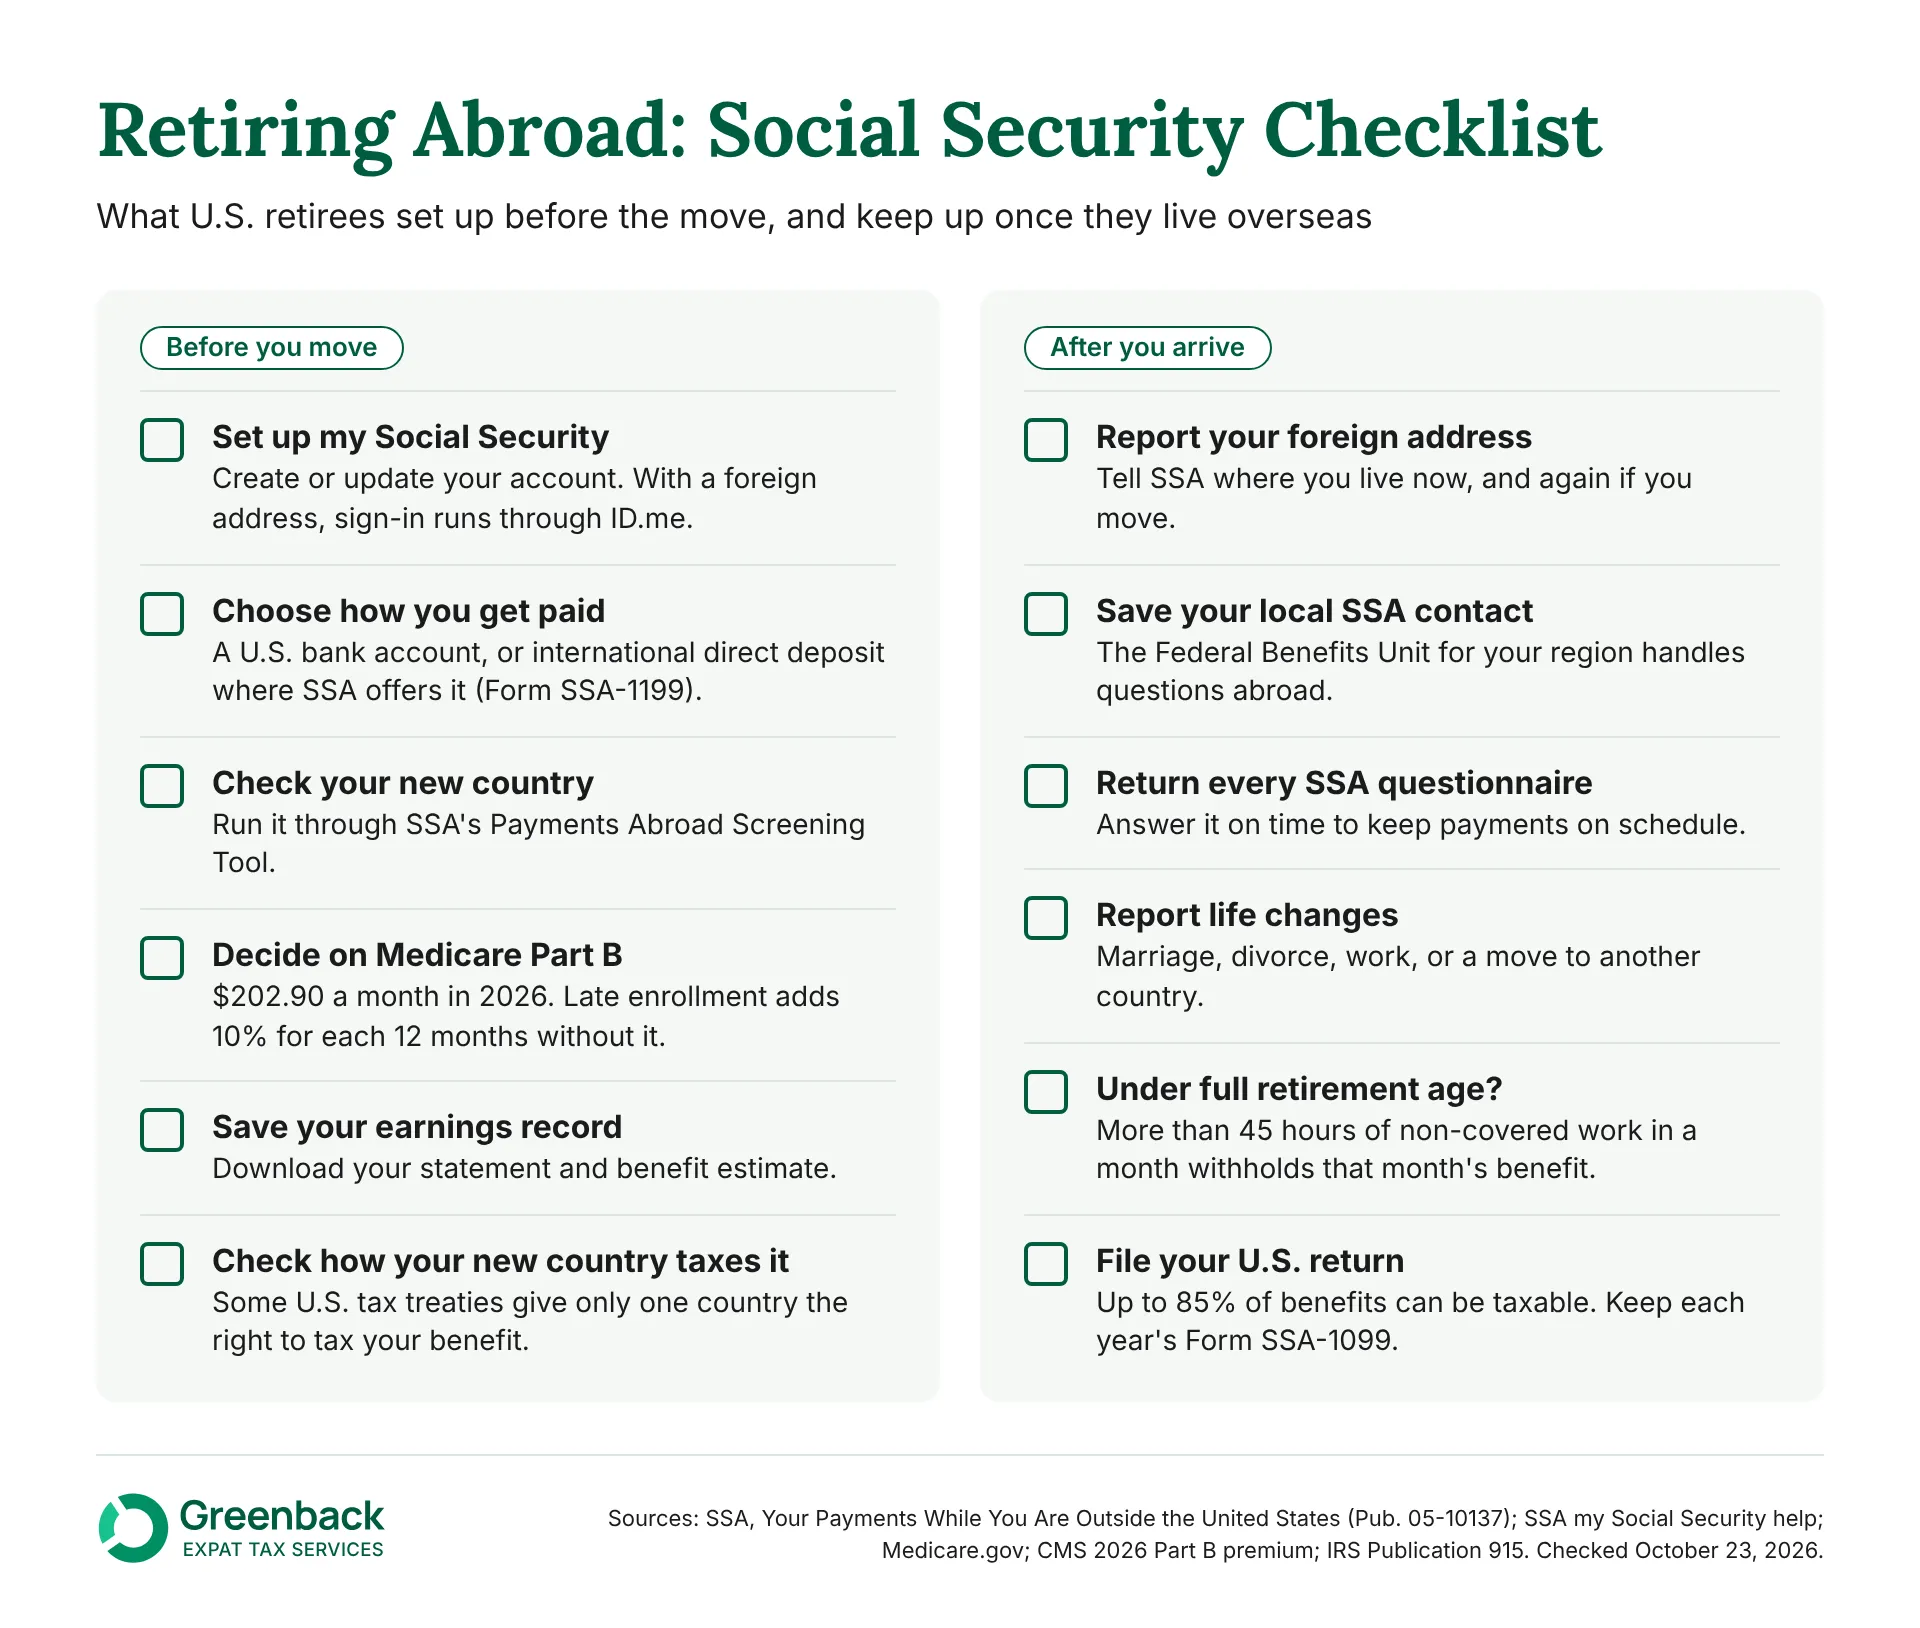
Before you leave, set up your account access, decide how you get paid, and settle Medicare. After you arrive, staying in touch with SSA and filing your U.S. return each year keeps payments steady and your taxes in order.
Before You Move
Set up my Social Security while you still have a U.S. address, since sign-in changes once your address is foreign. Choose your payment route and confirm your new country with the screening tool. Download your earnings record and benefit estimate so you have them on hand, and check how your new country’s treaty treats your benefits, since that decides where you will owe tax. Our guides to moving abroad and tax planning for retiring abroad cover the rest of the move.
Medicare Does Not Follow You Abroad
Medicare generally does not pay for care outside the U.S. That makes Part B a real decision for retirees moving abroad: the standard premium is $202.90 a month in 2026, but if you drop it and enroll later, a late enrollment penalty adds 10% to your premium for each full 12-month period you went without it, for as long as you have Part B. Our guide to Medicare for U.S. expats walks through the trade-off.
After You Arrive
Report your foreign address to SSA, save the contact details for the Federal Benefits Unit that serves your region, and return every SSA questionnaire on time. Report life changes as they happen. Each year, file your U.S. return with your Form SSA-1099, and keep up with expat retirement planning as your income sources change.
Frequently Asked Questions about Social Security for Expats
Yes. U.S. citizens can collect Social Security retirement benefits in Mexico, Portugal, and nearly every other country, with no time limit. For tax purposes, the U.S.-Mexico treaty gives the U.S. the exclusive right to tax U.S. Social Security. Under the U.S.-Portugal treaty, both countries may tax the benefits, with treaty relief that helps prevent double taxation.
Green card holders and other non-citizens generally lose Social Security payments after six full calendar months outside the U.S., unless an exception applies, such as citizenship in a country with a U.S. totalization agreement. Payments restart after a full calendar month has passed back in the U.S. SSA’s Payments Abroad Screening Tool checks exceptions by country.
Yes. U.S. citizens can collect Social Security Disability Insurance (SSDI) while living abroad, under the same country rules that apply to retirement benefits. Supplemental Security Income (SSI) is different: it stops after 30 consecutive days outside the U.S.
Renouncing U.S. citizenship does not cancel Social Security benefits you earned through work, but you then follow the non-citizen rules: payments generally stop after six full calendar months outside the U.S. unless an exception applies, and, as a nonresident alien, 25.5% is withheld from each payment unless a treaty lowers it. Our guide to renouncing citizenship and retiring abroad covers how Social Security is affected.
It depends on the tax treaty. U.S. citizens living in Canada, Germany, Ireland, Israel, Egypt, Romania, or the UK are taxed on U.S. Social Security only by that country. In France and Mexico, only the U.S. taxes it. In Spain and Portugal, both countries may tax it, with treaty relief that helps prevent double taxation.
Greenback Reports Your Social Security Correctly, Wherever You Retire
Moving abroad does not take away the Social Security you earned, and the questions that remain are mostly about your tax return: how much of your benefit is taxable, whether a treaty moves the tax to your new country, and how the Foreign Tax Credit fits with your other income. Greenback’s accountants prepare U.S. federal tax returns like these for retirees abroad every year, so your benefits are reported correctly, and you keep as much of them as the rules allow.
If you’re a retiree living abroad, Greenback helps you keep your Social Security, pensions, and U.S. filing in step. Learn more about how we help retirees abroad.

Retiring Abroad With Social Security?
This article is for informational purposes only and does not constitute tax, legal, or financial advice. Social Security and tax rules change, and your situation may differ. For guidance on your circumstances, consult a qualified tax professional or contact the Social Security Administration.
Featured In