What Is a U.S. Person for Tax Purposes?

A U.S. person for tax purposes is a U.S. citizen, a green card holder, a foreign national who meets the substantial presence test, or a domestic partnership, corporation, estate, or trust. According to the IRS, U.S. persons are taxed on their worldwide income, and the status applies wherever you live.
As a U.S. person, you file a U.S. return that reports your worldwide income and, in many cases, report foreign bank accounts and assets too, even while living abroad. Whether you owe any tax is settled on the return itself, where the Foreign Earned Income Exclusion and the Foreign Tax Credit can reduce or remove the U.S. tax.
Who Is a U.S. Person for Tax Purposes?
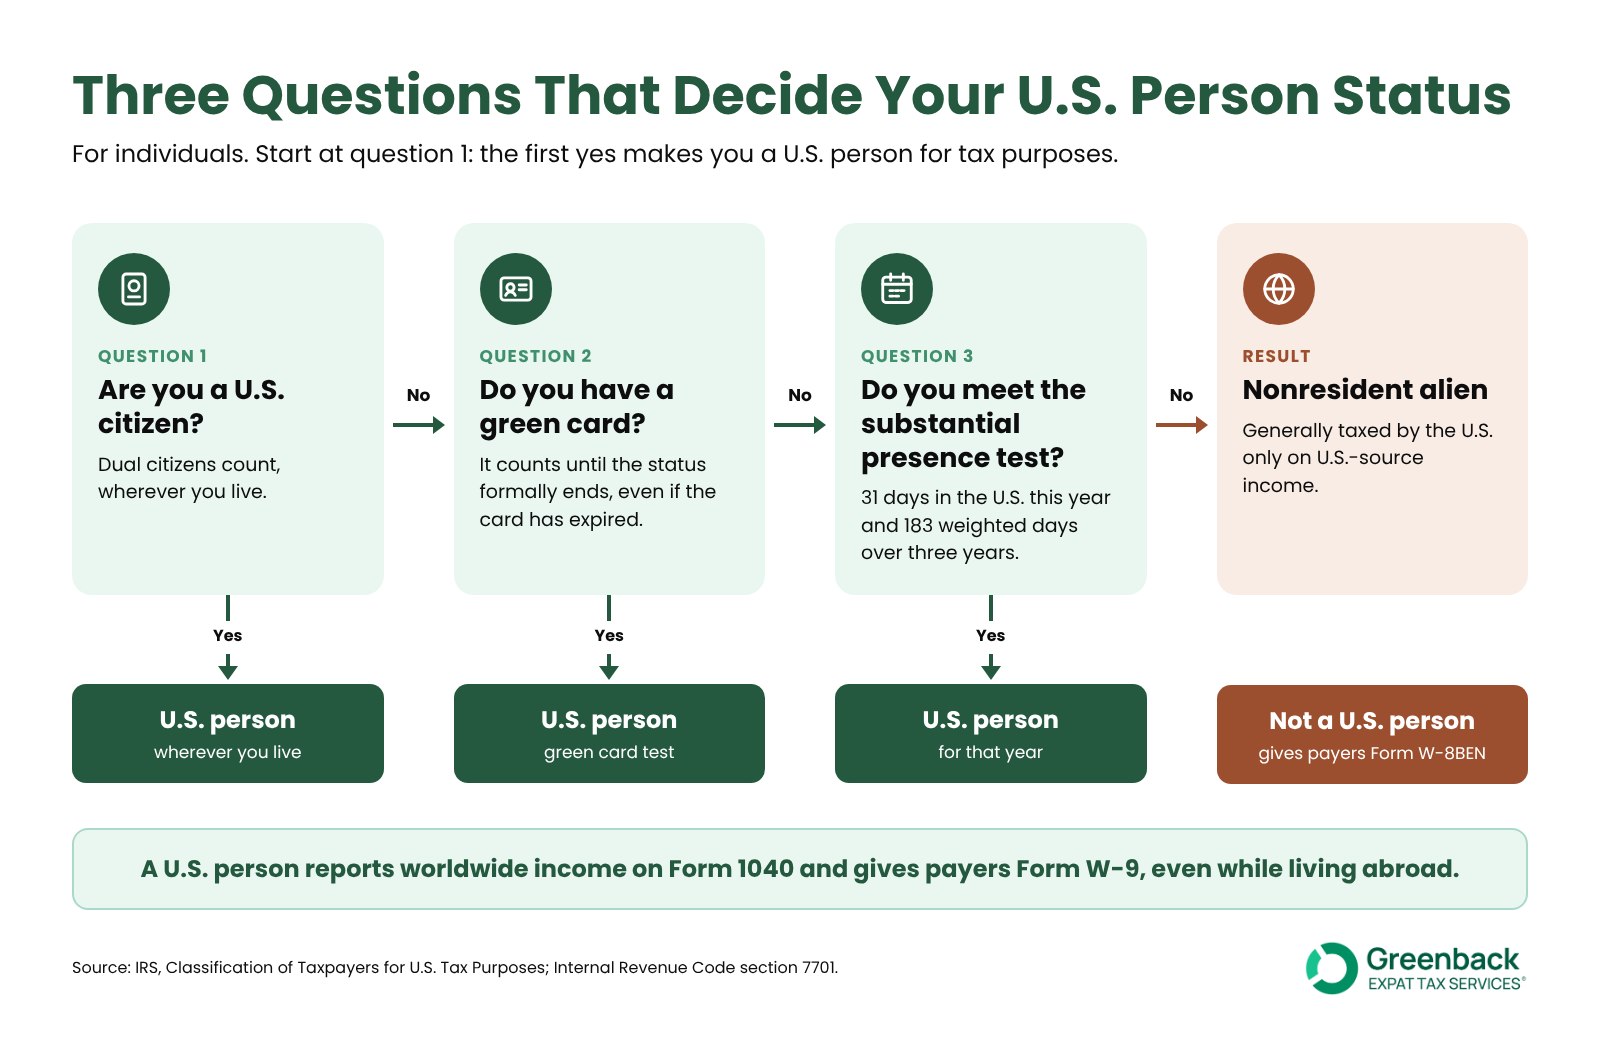
Individuals become U.S. persons in one of three ways: U.S. citizenship, the green card test, or the substantial presence test, and meeting any one of them is enough. Partnerships, corporations, estates, and trusts qualify under U.S. law based on how they are formed or supervised, as set out in Internal Revenue Code section 7701(a)(30).
1. U.S. Citizens Are U.S. Persons Wherever They Live
Every U.S. citizen is a U.S. person, including citizens who have lived abroad for decades. That covers people born in the U.S., naturalized citizens, and children born abroad who acquired citizenship from a U.S. parent. A second passport does not change it, as our guide to taxes for dual citizens explains. People who learn about their citizenship late, often called accidental Americans, are U.S. persons too.
2. Green Card Holders Meet the Green Card Test
A lawful permanent resident is a U.S. resident for tax purposes under the green card test, even while living outside the U.S. The status lasts until it formally ends, so an expired card leaves it in place. If you also count as a resident of a treaty country, a tie-breaker rule can treat you as a nonresident, which has its own consequences for long-term residents. Our guide to filing taxes abroad as a green card holder covers the return itself.
3. The Substantial Presence Test Covers Other Foreign Nationals
A foreign national without a green card becomes a U.S. person for the year by spending at least 31 days in the U.S. that year and 183 days over three years. The 183 counts every day this year, one-third of last year’s days, and one-sixth of the days from the year before. Days as an exempt individual, such as a student on an F or J visa, generally do not count. Our substantial presence test guide walks through the count. If you pass the test with fewer than 183 days this year, the closer connection exception on Form 8840 may keep you a nonresident.
4. U.S. Partnerships, Corporations, Estates and Trusts
Domestic partnerships and corporations are U.S. persons, along with any estate other than a foreign estate. A trust is one when a U.S. court can supervise it, and U.S. persons control its substantial decisions. FinCEN explicitly names limited liability companies in its U.S. person definition for the FBAR.
What Is the Difference Between a U.S. Person and a U.S. Citizen?
U.S. citizenship is a nationality, while “U.S. person” is a tax classification, so every citizen is a U.S. person, but many U.S. persons are not citizens. Green card holders and substantial presence residents are U.S. persons for tax purposes without holding a U.S. passport. A nonresident alien is neither, and is generally taxed only on U.S.-source income, as our guide to the taxation of nonresident aliens explains.
| Your status | U.S. person? | Income the U.S. taxes | Form you give a payer |
|---|---|---|---|
| U.S. citizen, living anywhere | Yes | Worldwide | W-9 |
| Green card holder | Yes, until the status formally ends | Worldwide | W-9 |
| Substantial presence resident | Yes, for that year | Worldwide | W-9 |
| Nonresident alien | No | Generally U.S.-source only | W-8BEN |
The year you arrive or leave can be split between resident and nonresident status, which our guide to dual-status aliens covers. Export control and sanctions rules, such as ITAR, define a U.S. person separately, so a compliance course at work may describe a different test.
What Does “Other U.S. Person” Mean on Form W-9?
On Form W-9, “other U.S. person” generally means a U.S. person who is not a U.S. citizen: a U.S. resident alien, or a partnership, corporation, company, association, estate or trust that is domestic under U.S. law. Part II of the IRS form (Rev. March 2024) asks you to certify “I am a U.S. citizen or other U.S. person.” A green card holder or a substantial presence resident signs that line, and a nonresident alien uses Form W-8BEN instead. Our guide to Form W-8 vs. Form W-9 explains which one fits your situation, and this Tax Q&A covers switching forms after you get a green card.
Foreign Banks Ask Whether You Are a Specified U.S. Person
Banks outside the U.S. ask about your status because FATCA requires them to report the accounts of specified U.S. persons to the IRS, directly or through their own government. Every U.S. citizen and resident individual is a specified U.S. person; the exclusions in Internal Revenue Code section 1473(3) cover only certain entities, such as publicly traded corporations, banks, and tax-exempt organizations. If you are a U.S. citizen or resident, answer “yes” on the bank’s self-certification form and provide your U.S. taxpayer identification number. Our guide to FATCA covers the rules, and our Tax Q&A on a FATCA letter from a foreign bank explains what happens next.
Payment Platforms Ask About a “U.S. Resident Entity”
Some payment and payout platforms ask, “Are you a U.S. resident entity?” during tax setup to determine whether to collect a Form W-9 or a Form W-8. For an individual, the question generally asks whether you are a U.S. person. A U.S. citizen or resident alien answers yes and completes a W-9, and a nonresident alien generally answers no and completes a W-8BEN. Check the platform’s help page if its wording differs.
What Do You Have to File as a U.S. Person?
As a U.S. person, you file Form 1040 once your income reaches the filing threshold, attach Form 8938 to that return when your foreign assets pass its limits, and file an FBAR whenever your foreign accounts top $10,000 combined, wherever you live.
| Filing | When it applies | Due date |
|---|---|---|
| Form 1040 | Generally once gross income reaches the standard deduction ($16,100 single for tax year 2026), $400 of net self-employment income, or $5 if married filing separately | April 15, or June 15 automatically if you live and work abroad (interest runs from April 15) |
| FBAR | Foreign accounts total more than $10,000 at any time in the year | April 15, automatic extension to October 15 |
| Form 8938 | Living abroad: foreign financial assets over $200,000 at year-end or $300,000 at any time ($400,000 and $600,000 joint). Lower thresholds apply in the U.S. | Filed with your Form 1040 |
The $5 threshold for married filing separately often applies to Americans married to a nonresident spouse.
The filing threshold is the same abroad, and two tools reduce the tax on a return filed from overseas. The Foreign Earned Income Exclusion removes up to $132,900 of foreign earned income from U.S. tax for tax year 2026 if you qualify. The Foreign Tax Credit offsets U.S. tax with income tax you already paid abroad, and in a country with higher rates it typically covers the U.S. liability in full.
Can You Stop Being a U.S. Person?
You stop being a U.S. person only when the status that made you one ends: citizens by renouncing, green card holders by abandoning or losing permanent residence, and substantial presence residents by no longer meeting the day count. Each works differently:
- Citizens: Renounce before a U.S. consular officer. Your tax status generally ends on that date once the Certificate of Loss of Nationality is approved, and you report the expatriation on Form 8854. Neither years abroad nor a second citizenship ends it. Our guide to renouncing U.S. citizenship covers the process.
- Green card holders: Abandon the status in writing with USCIS Form I-407, or have it terminated by USCIS or a federal court. Long-term residents also file Form 8854.
- Substantial presence residents: Your residency ends once you no longer meet the test, usually with a dual-status year at departure.
Ending the status generally ends U.S. tax on your worldwide income, though U.S. filing may continue depending on your situation, for example, a nonresident return for U.S.-source income. Some people who give up citizenship or a long-held green card may also owe the exit tax, so it is worth checking before you act.
Frequently Asked Questions
Nonresident aliens are not U.S. persons, and neither are foreign corporations, foreign partnerships, or foreign estates and trusts. According to the IRS, the U.S. branch of a foreign corporation or partnership is generally treated as a foreign person too. A foreign national who visits the U.S. without meeting the substantial presence test stays a nonresident.
Generally not at first. An F-1 student is usually an exempt individual, so days in the U.S. do not count toward the substantial presence test, and the student files Form 8843 to claim it. That exemption generally stops after five calendar years as a student, after which the student can become a U.S. person under the test.
Yes, when the child acquires U.S. citizenship at birth through a U.S. citizen parent. When only one parent is a citizen, that parent generally needs 5 years of physical presence in the U.S. before the birth, at least 2 of them after the parent turned 14.
A bill pending in Congress would tighten that test, as covered in our article on the citizenship presence test bill.
Your U.S. Person Status Moves With You When You Live Abroad
For U.S. citizens and green card holders, moving abroad leaves your U.S. person status unchanged, so the same U.S. return and foreign-account reporting continue from your new country. Our guide to taxes for U.S. citizens abroad covers how that return works from overseas.

Not Sure How the IRS Classifies You?
The information in this article is for general informational purposes only and does not constitute tax, legal, or financial advice. Tax rules are complex and change frequently. Consult a qualified tax professional regarding your specific situation before taking any action.
Featured In


