Bona Fide Residence Test for U.S. Expats: How to Qualify for the FEIE

- What Is the Bona Fide Residence Test?
- What Are the Bona Fide Residence Test Requirements?
- What Counts as an Uninterrupted Period?
- How Does the IRS Decide If You Pass the Bona Fide Residence Test?
- Which Situations Qualify for Bona Fide Residence?
- What If You Do Not Qualify for the Bona Fide Residence Test?
- Frequently Asked Questions
- The First Year Is the One That Decides the Rest
The bona fide residence test qualifies you for the Foreign Earned Income Exclusion (FEIE) if you have genuinely settled in a foreign country for an uninterrupted period that includes an entire tax year, 1 January to 31 December. There is no day count.
You can travel back to the U.S. as often as you need, provided you return to your foreign home without unreasonable delay. The period must cover a full calendar year, though not necessarily your first year abroad. A fixed end date works against you. Either way, the exclusion is the same, up to $130,000 on a 2025 return and $132,900 on a 2026 return.
What determines whether a claim is real is the set of questions the IRS asks on Form 2555, Part II. One of them ends a claim outright, and the records that address the rest are covered later.
What Is the Bona Fide Residence Test?
The bona fide residence test is one of two ways to qualify for the Foreign Earned Income Exclusion. It confirms whether you have genuinely made a foreign country your home, and the IRS settles that on the facts of your situation, not on your stated intention alone. The other route, the physical presence test, ignores intent entirely and counts days instead.
The test comes from Section 911 of the tax code, and it has no formula. There is no minimum number of days, no maximum number of trips home, and no checklist that guarantees a pass. What there is instead is a period requirement, a set of conditions, and a body of facts the IRS weighs.
Bona Fide Resident Has a Specific Legal Meaning
A bona fide resident is someone who has settled in a foreign country and lives there as a resident, with no fixed period after which they return home. The meaning is a legal one. The definition is decided by how long you stayed, the nature of your work there, the ties you built, and whether you paid income tax to that country, and bona fide residents are the people whose facts line up on each one.
One point of confusion worth clearing early. The phrase “bona fide resident” also appears in a separate part of the tax code covering Puerto Rico, Guam, the U.S. Virgin Islands, and other U.S. territories, under Section 937. That is a different test with different rules, and nothing on this page applies to it.
What Are the Bona Fide Residence Test Requirements?
Two sets of conditions apply, and they sit at different levels. One governs the exclusion itself, the other governs bona fide residence.
- To claim the FEIE at all, you need foreign earned income from work performed abroad, and a tax home in a foreign country for the period you are claiming. Passive income does not qualify: dividends, interest, rental income, pensions, and capital gains all sit outside the exclusion, however long you live abroad.
- To qualify under bona fide residence specifically, you need to be a U.S. citizen, or a resident alien who is a citizen or national of a country with a U.S. income tax treaty in force, and you need to be a bona fide resident of a foreign country for an uninterrupted period that includes an entire tax year.
A green card holder living abroad can qualify. A student visa or another visa with a fixed expiry usually cannot, because the form asks whether your visa is limited to how long you can stay.
Telling the Foreign Authorities You Are Not a Resident Ends the Claim
You are not considered a bona fide resident of a foreign country if you make a statement to the authorities of that country that you are not a resident, and those authorities hold that you are not subject to their income tax laws as a resident. Form 2555 asks this directly on Line 13a, and the answer overrides everything else in your file.
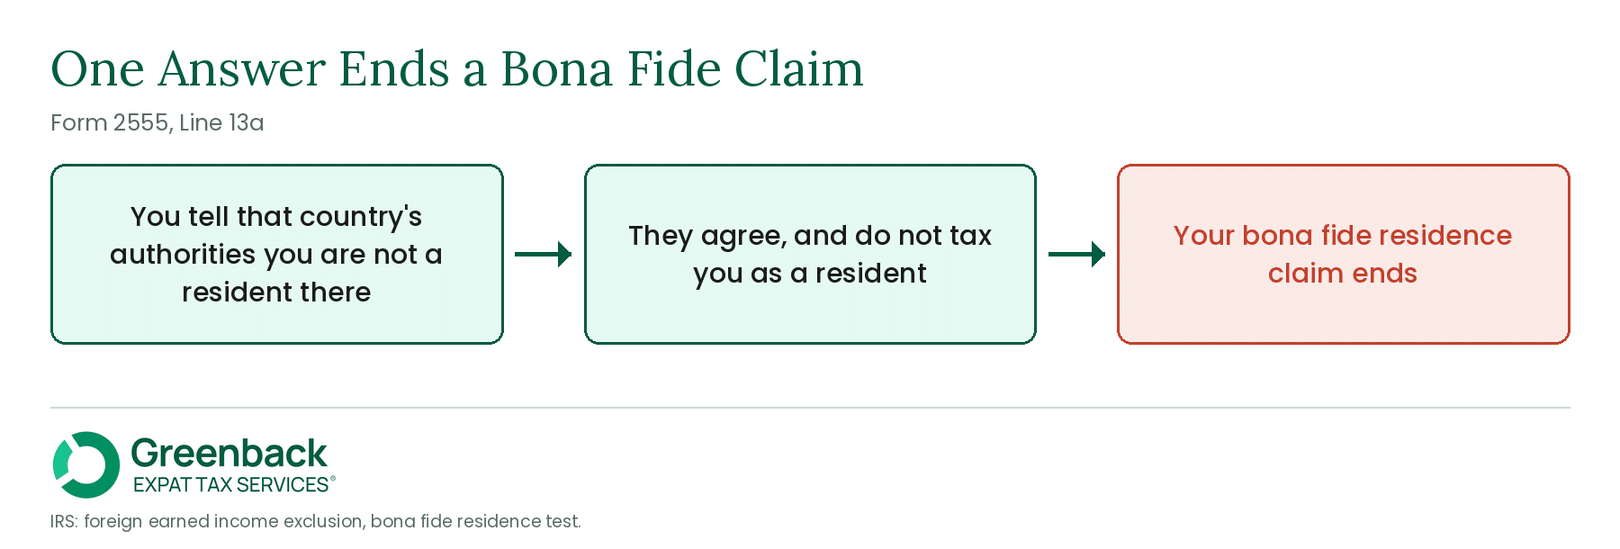
This catches people who filed a non-residency declaration to reduce a local tax bill, then claimed U.S. bona fide residence for the same year. The two positions cannot both be true.
The IRS says that if you go to a foreign country to work for a specified period of time, you ordinarily will not be regarded as a bona fide resident of that country, even if you work there for a tax year or longer.
That word carries the whole exception. A fixed term is not an automatic bar, because the determination is decided by the length of your stay, the nature of your work, your activities in the country, and whether you paid tax there. What it does mean is that a three-year contract with a return date already set is a weak claim, and the form asks you to write that contract term down. Most people on a defined assignment qualify instead through the physical presence test.
What Counts as an Uninterrupted Period?
The period must include an entire tax year, from 1 January through 31 December. Twelve months is not the same thing: someone who moves abroad in July and leaves the following July has lived there a year without ever covering a calendar year, and does not qualify.
Uninterrupted does not mean you never leave. Brief trips back to the U.S. are fine, for vacation or for business, as long as you return to your foreign residence, or to a new one in another country, without unreasonable delay. There is no cap on how many. The period breaks only if you abandon the foreign residence.
Your Residence Period Starts Before the Qualifying Year
Once you complete an uninterrupted period covering a full tax year, you qualify as a bona fide resident for the period starting with the date you began your residency and ending with the date you abandon your foreign residence. The full tax year is what qualifies you. The period you can claim runs wider than that year at both ends.
So someone who arrives on 1 November 2025 and completes the 2026 calendar year is a bona fide resident as of that date. Their 2025 return can claim a prorated exclusion for those weeks, and every year after 2026 is covered until they leave.
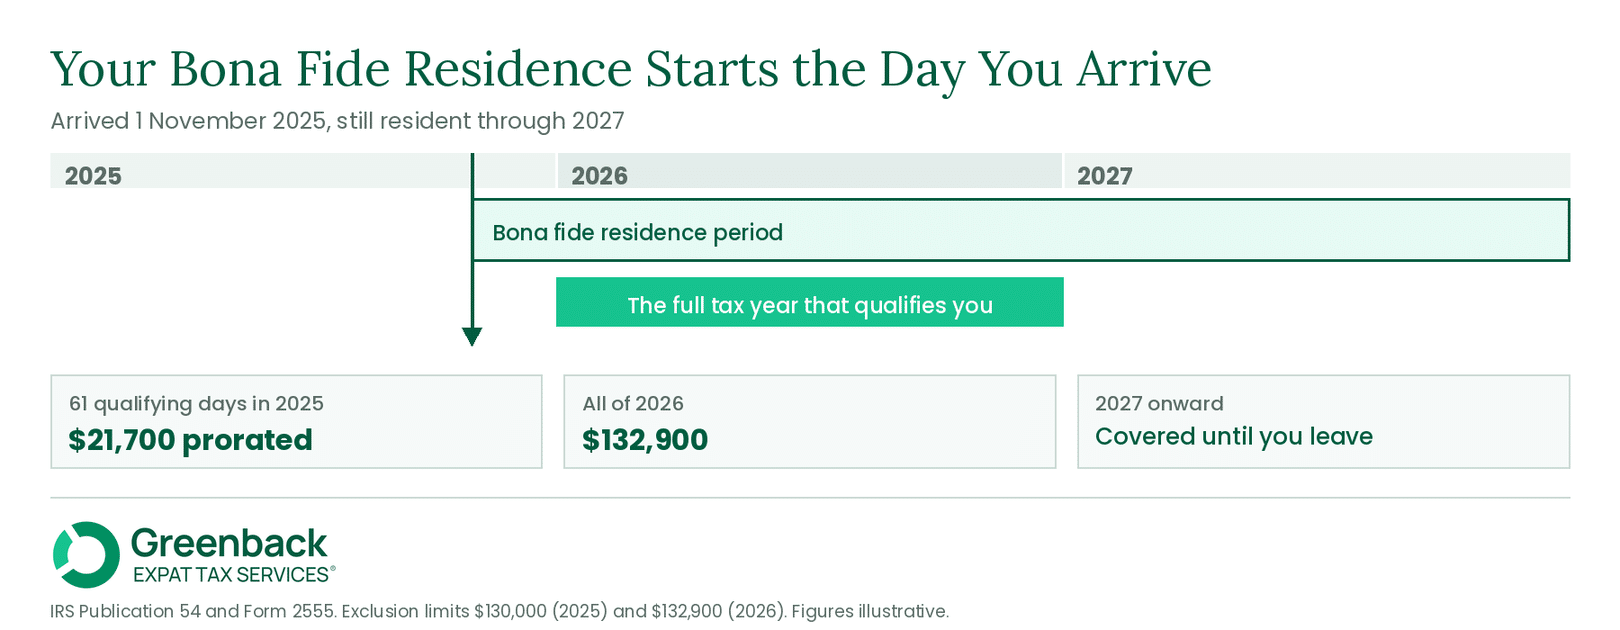
The prorated figure for a part-year is the maximum exclusion multiplied by your qualifying days for that year, divided by 365. Sixty-one qualifying days in 2025 at the $130,000 limit is about $21,700.
This is why the first year matters more than any year after it. Line 10 of Form 2555 asks for the dates your bona fide residence began and ended, and those two dates set everything downstream.
How Does the IRS Decide If You Pass the Bona Fide Residence Test?
Everything the IRS knows about your year comes from Part II of Form 2555, and everything it would ask for in a review is the records sitting behind those answers.
Form 2555, Part II, Is Where the Claim Is Decided
Part II of Form 2555 is the IRS’s own questionnaire for this claim. Knowing what each question tests and which record answers it is the difference between a claim that holds and one that does not.
| Form 2555 asks | What it is testing | The record that answers it |
|---|---|---|
| Line 11. Kind of living quarters in the foreign country | Whether you established a home or only a base | Your lease or purchase documents |
| Line 12a. Did any of your family live with you abroad? | Whether your life moved, or only you did | School enrolment, dependants’ residence permits |
| Line 13a. Have you submitted a statement to the foreign authorities that you are not a resident? | Whether you have already told another government the opposite | Any non-residency filing you made locally |
| Line 13b. Are you required to pay income tax to that country? | Whether the country itself treats you as resident | Local tax filings and assessments |
| Line 14. Your travel to the U.S. during the year | Whether your trips home stayed brief | Arrival and departure dates for every trip |
| Line 15a and 15c. Contractual terms limiting your employment, and whether your visa limited your stay | Whether your stay has a built-in end date | Employment contracts and your residence permit |
| Line 15d and 15e. Whether you kept a home in the United States, and who lives in it | Whether you kept a life to come back to | Tenancy agreement, or the sale |
None of these decides the claim on its own, apart from Line 13a. A strong file answers them in the same direction, and the strongest single piece of evidence is the local tax filing behind Line 13b, because it is the foreign government agreeing with you.
Build Your Bona Fide Residence File From the Day You Arrive
The IRS can ask about a bona fide residence claim years after the return is filed, and a lease or a utility account is far easier to maintain at the time than to reconstruct later. A U.S. home rented out supports the claim; one kept empty and waiting works against it.
Workers whose employers use Form 673 to stop U.S. withholding sign a statement saying they expect to qualify for the foreign earned income exclusion under either the bona fide residence or physical presence test. That certification states what you expect, and it does not settle anything on your return.
Which Situations Qualify for Bona Fide Residence?
The line is easiest to see in real situations. Each of these turns on a single fact, and in every one of them, that fact is either a date already set or a calendar year left incomplete.
1. A Fixed-Term Assignment With a Set Return Date Does Not Qualify
Chris moves to Turkey on a three-year assignment. He lives there continuously and does not return to the U.S., but his contract ends in 2028, and he will go home then.
He has the full tax years. Every document in his file carries the same end date, so the facts point to a temporary stay. What would change it: a contract renewed with no new end date, a local permanent residence permit, or a move to local terms.
2. Twelve Months Abroad That Misses a Calendar Year Does Not Qualify
Adriana relocates from the U.S. to Germany in July 2025, intending to stay. By July 2026, her plans had changed, and she moved back.
She lived in Germany for a full twelve months, but no single calendar year ran start to finish, and the test needs an entire tax year. What would change it: staying through 31 December 2026.
3. Arriving Mid-Year and Completing the Next One Qualifies
Jack accepts a job in China and moves to Beijing in November 2025. He is still living there through 2026 with no plans to return.
All of 2026 is an uninterrupted period covering a full tax year; he earns foreign income, and nothing in his file points to an end date. His residence runs from his arrival, so the exclusion covers his partial 2025 as well.
4. A Short Trip Home Does Not Break the Claim
Abby moved to India with her family on 1 January 2025. Her aunt in the U.S. falls ill, so she returns for three weeks to care for her, then goes back to India, takes a job, and stays through 2026.
Her trip home does not break bona fide residence, because she returned without unreasonable delay. So, her family moving with her strengthens the claim.
What If You Do Not Qualify for the Bona Fide Residence Test?
Failing the bona fide residence test for a year does not leave you paying U.S. tax on income you have already been taxed on abroad. Other routes reach the same place, and one of them has no residence test at all.
1. The Physical Presence Test Counts Days Instead
The physical presence test reaches the same exclusion by counting 330 full days in foreign countries within any 12 consecutive months, and it asks nothing about your intent. Our guide to choosing between the two tests walks through which one fits your year.
2. The Foreign Tax Credit Has No Residence Test
If neither works, the Foreign Tax Credit gives you a dollar-for-dollar credit against your U.S. tax for income tax you paid abroad, with no residence or day-count test at all. In a high-tax country, it often yields better results than exclusion.
2. War or Unrest Can Waive the Time Requirement
If war, civil unrest, or similar conditions forced you out of a country before you completed the year, the IRS can waive the minimum time requirement, and it publishes the qualifying countries and dates each year. Our guide to the FEIE time requirement waiver covers how to claim it.
Frequently Asked Questions
You pass the bona fide residence test by living in a foreign country for an uninterrupted period that includes a full tax year, 1 January to 31 December, with no fixed date set for your return. There is no day count. The IRS decides it on the facts you report on Form 2555, Part II: your living quarters, whether your family moved with you, whether you pay income tax locally, and whether anything in your visa or contract limits how long you can stay.
A bona fide resident is someone who has genuinely made a foreign country their home instead of staying there temporarily. The meaning is a legal one, and the IRS settles it on the facts: how long you stayed, the nature of your work there, the ties you built, and whether you paid income tax to that country. Telling that country’s authorities you are not a resident ends the claim.
Yes, and there is no limit on how many. The condition is that you return to your foreign residence, or to a new one in another country, without unreasonable delay. A few weeks caring for family does not break the claim. Moving your household back does. Form 2555 asks you to list every trip, including its dates, on Line 14.
A green card holder can qualify, but only if they are a citizen or national of a country that has an income tax treaty in force with the United States. A U.S. citizen has no such condition. Everything else about the test applies the same way to both.
Yes. You choose a test for each tax year, and a year claimed under one does not commit you to it the next. Switching tests is not the same as revoking the exclusion itself. Formally revoking the FEIE triggers the five-year rule, and re-electing within that window requires IRS approval.
The First Year Is the One That Decides the Rest
The date your bona fide residence begins sets the shape of every return after it, and the file you build in that first year is what the claim rests on years later. Greenback’s accountants review the facts behind a bona fide claim, put them on Form 2555 the way the IRS reads them, and tell you plainly when the physical presence test is the safer route for your year.

Get your bona fide residence claim right the first year.
This article is for informational purposes only. The content does not constitute tax, legal, or financial advice. Tax rules and regulations change frequently, and your individual circumstances may affect how they apply to you. For personalized guidance, consult a qualified tax professional with expertise in U.S. expat taxes.
Featured In


