Child Tax Credit for Expats: How to Claim Up to $2,200 Per Child

- Can U.S. Expats Claim the Child Tax Credit?
- How Much Is the Child Tax Credit Worth?
- Does the FEIE Disqualify You From the Additional Child Tax Credit?
- Should You Use the FEIE or the Foreign Tax Credit?
- Can You Claim the Credit If Your Child Lives Abroad?
- How Do You Claim the Child Tax Credit From Abroad?
- Can You Claim the Child Tax Credit for Past Years?
- What Did the One Big Beautiful Bill Act Change?
- Frequently Asked Questions about Child Tax Credit
- Greenback Helps Americans Families Living Abroad File with Confidence
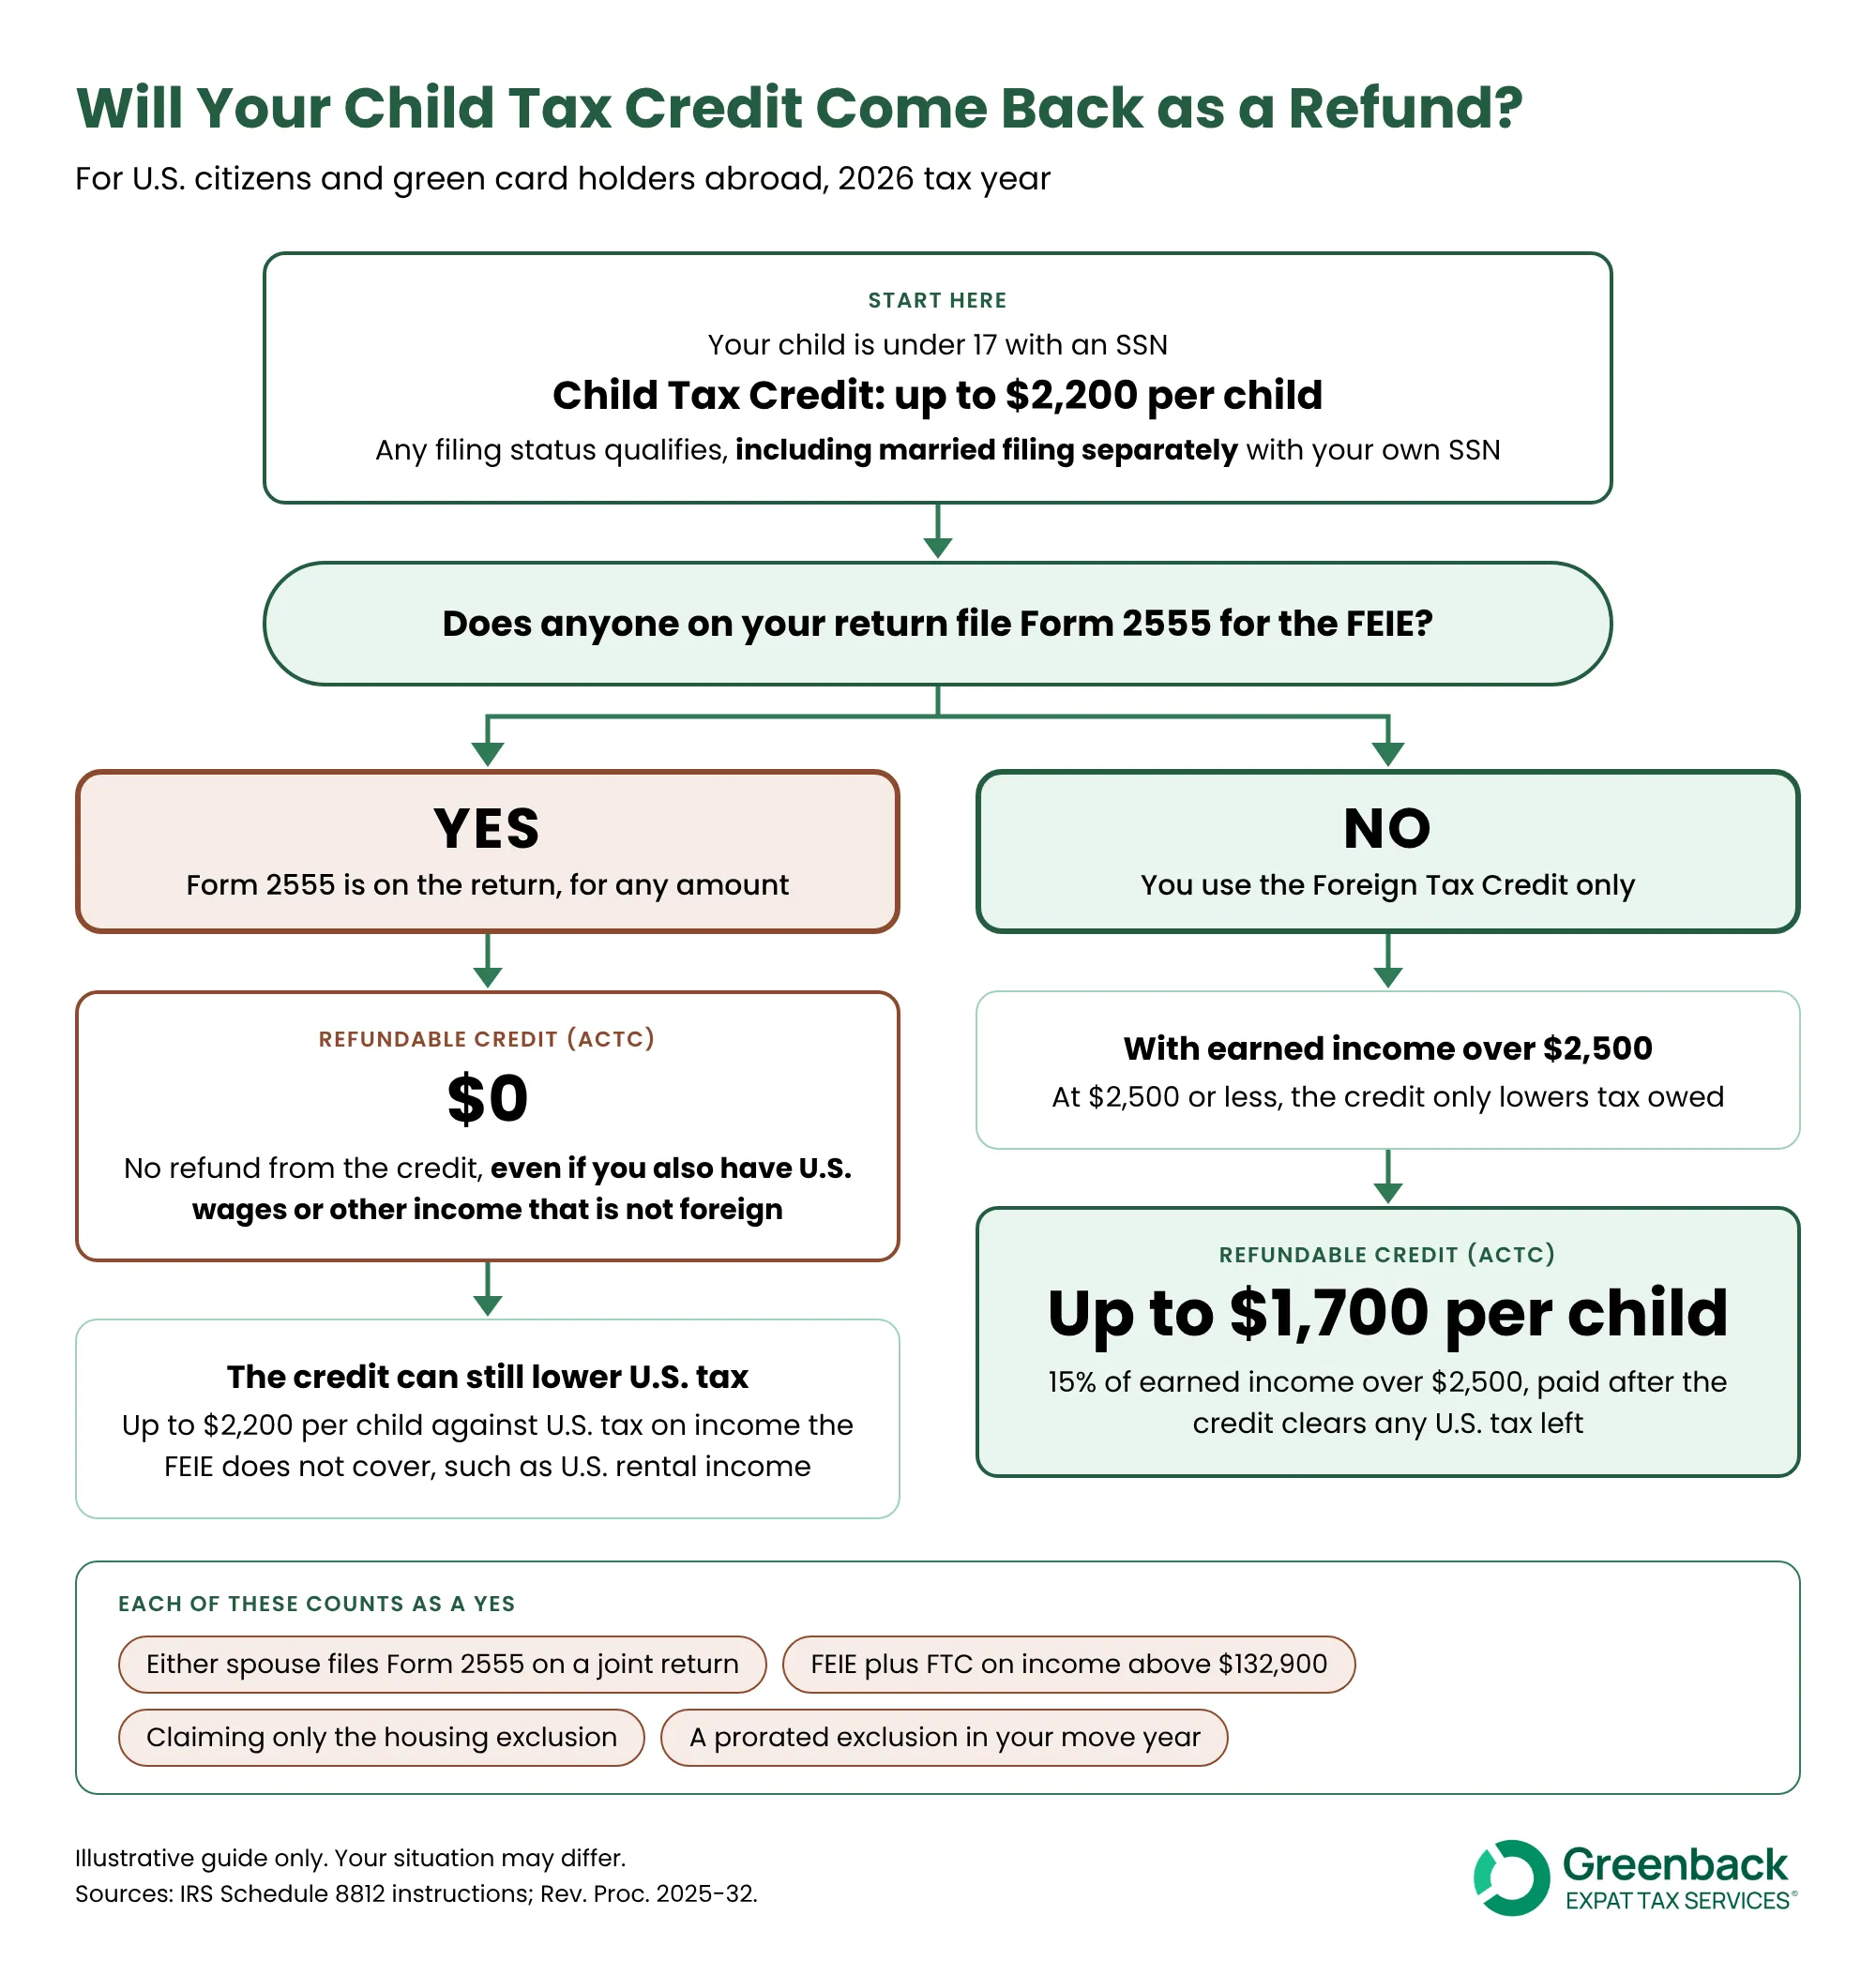
The Child Tax Credit for expats is worth up to $2,200 per qualifying child for the 2026 tax year, and U.S. citizens and green card holders living abroad claim it on the same terms as taxpayers in the United States. Up to $1,700 per child is refundable as the Additional Child Tax Credit (ACTC), paid to you even when you owe no U.S. tax, as long as no one on your return files Form 2555 for the Foreign Earned Income Exclusion (FEIE). You claim the credit on Schedule 8812 with your Form 1040.
The Foreign Tax Credit (FTC) is the route that keeps that refund, and it often comes out ahead even where local tax is lower than U.S. tax. Weighing the FEIE vs. the Foreign Tax Credit matters most if you pay little local tax. Any refund also needs more than $2,500 of earned income.
We’ve helped over 27,000 expats file more than 90,000 returns in 218 countries, and we know how Form 2555 changes the Child Tax Credit for families abroad. By the end of this guide, you’ll know whether your child qualifies, how much you can get back, and which filing method keeps the refund in your family.
Can U.S. Expats Claim the Child Tax Credit?
Yes, U.S. citizens and green card holders living abroad can claim the Child Tax Credit if they meet all eligibility requirements. Your physical location doesn’t disqualify you from this benefit. Your child must be under 17 on December 31 and have a Social Security Number (SSN). Above $200,000 of MAGI ($400,000 joint), the IRS phaseout reduces the credit.
The Child Tax Credit comes in two parts. The credit, up to $2,200 per child, lowers the U.S. tax you owe. The refund, up to $1,700 of that $2,200 per child, is the Additional Child Tax Credit (ACTC), which the IRS pays you when the credit is bigger than your U.S. tax. How you handle foreign income decides which part you can use:
| Your method | The credit (up to $2,200 per child) | The refund (ACTC, up to $1,700 per child) |
|---|---|---|
| Foreign Earned Income Exclusion (Form 2555) | Yes, against any U.S. tax you still owe | No |
| Foreign Tax Credit only (Form 1116) | Yes | Yes, with earned income over $2,500 |
With the FEIE, your U.S. tax is often already zero, so the credit may have nothing left to reduce. With the Foreign Tax Credit alone, the unused credit comes back as a refund.
1. Your Child Must Pass Every Qualifying-Child Test
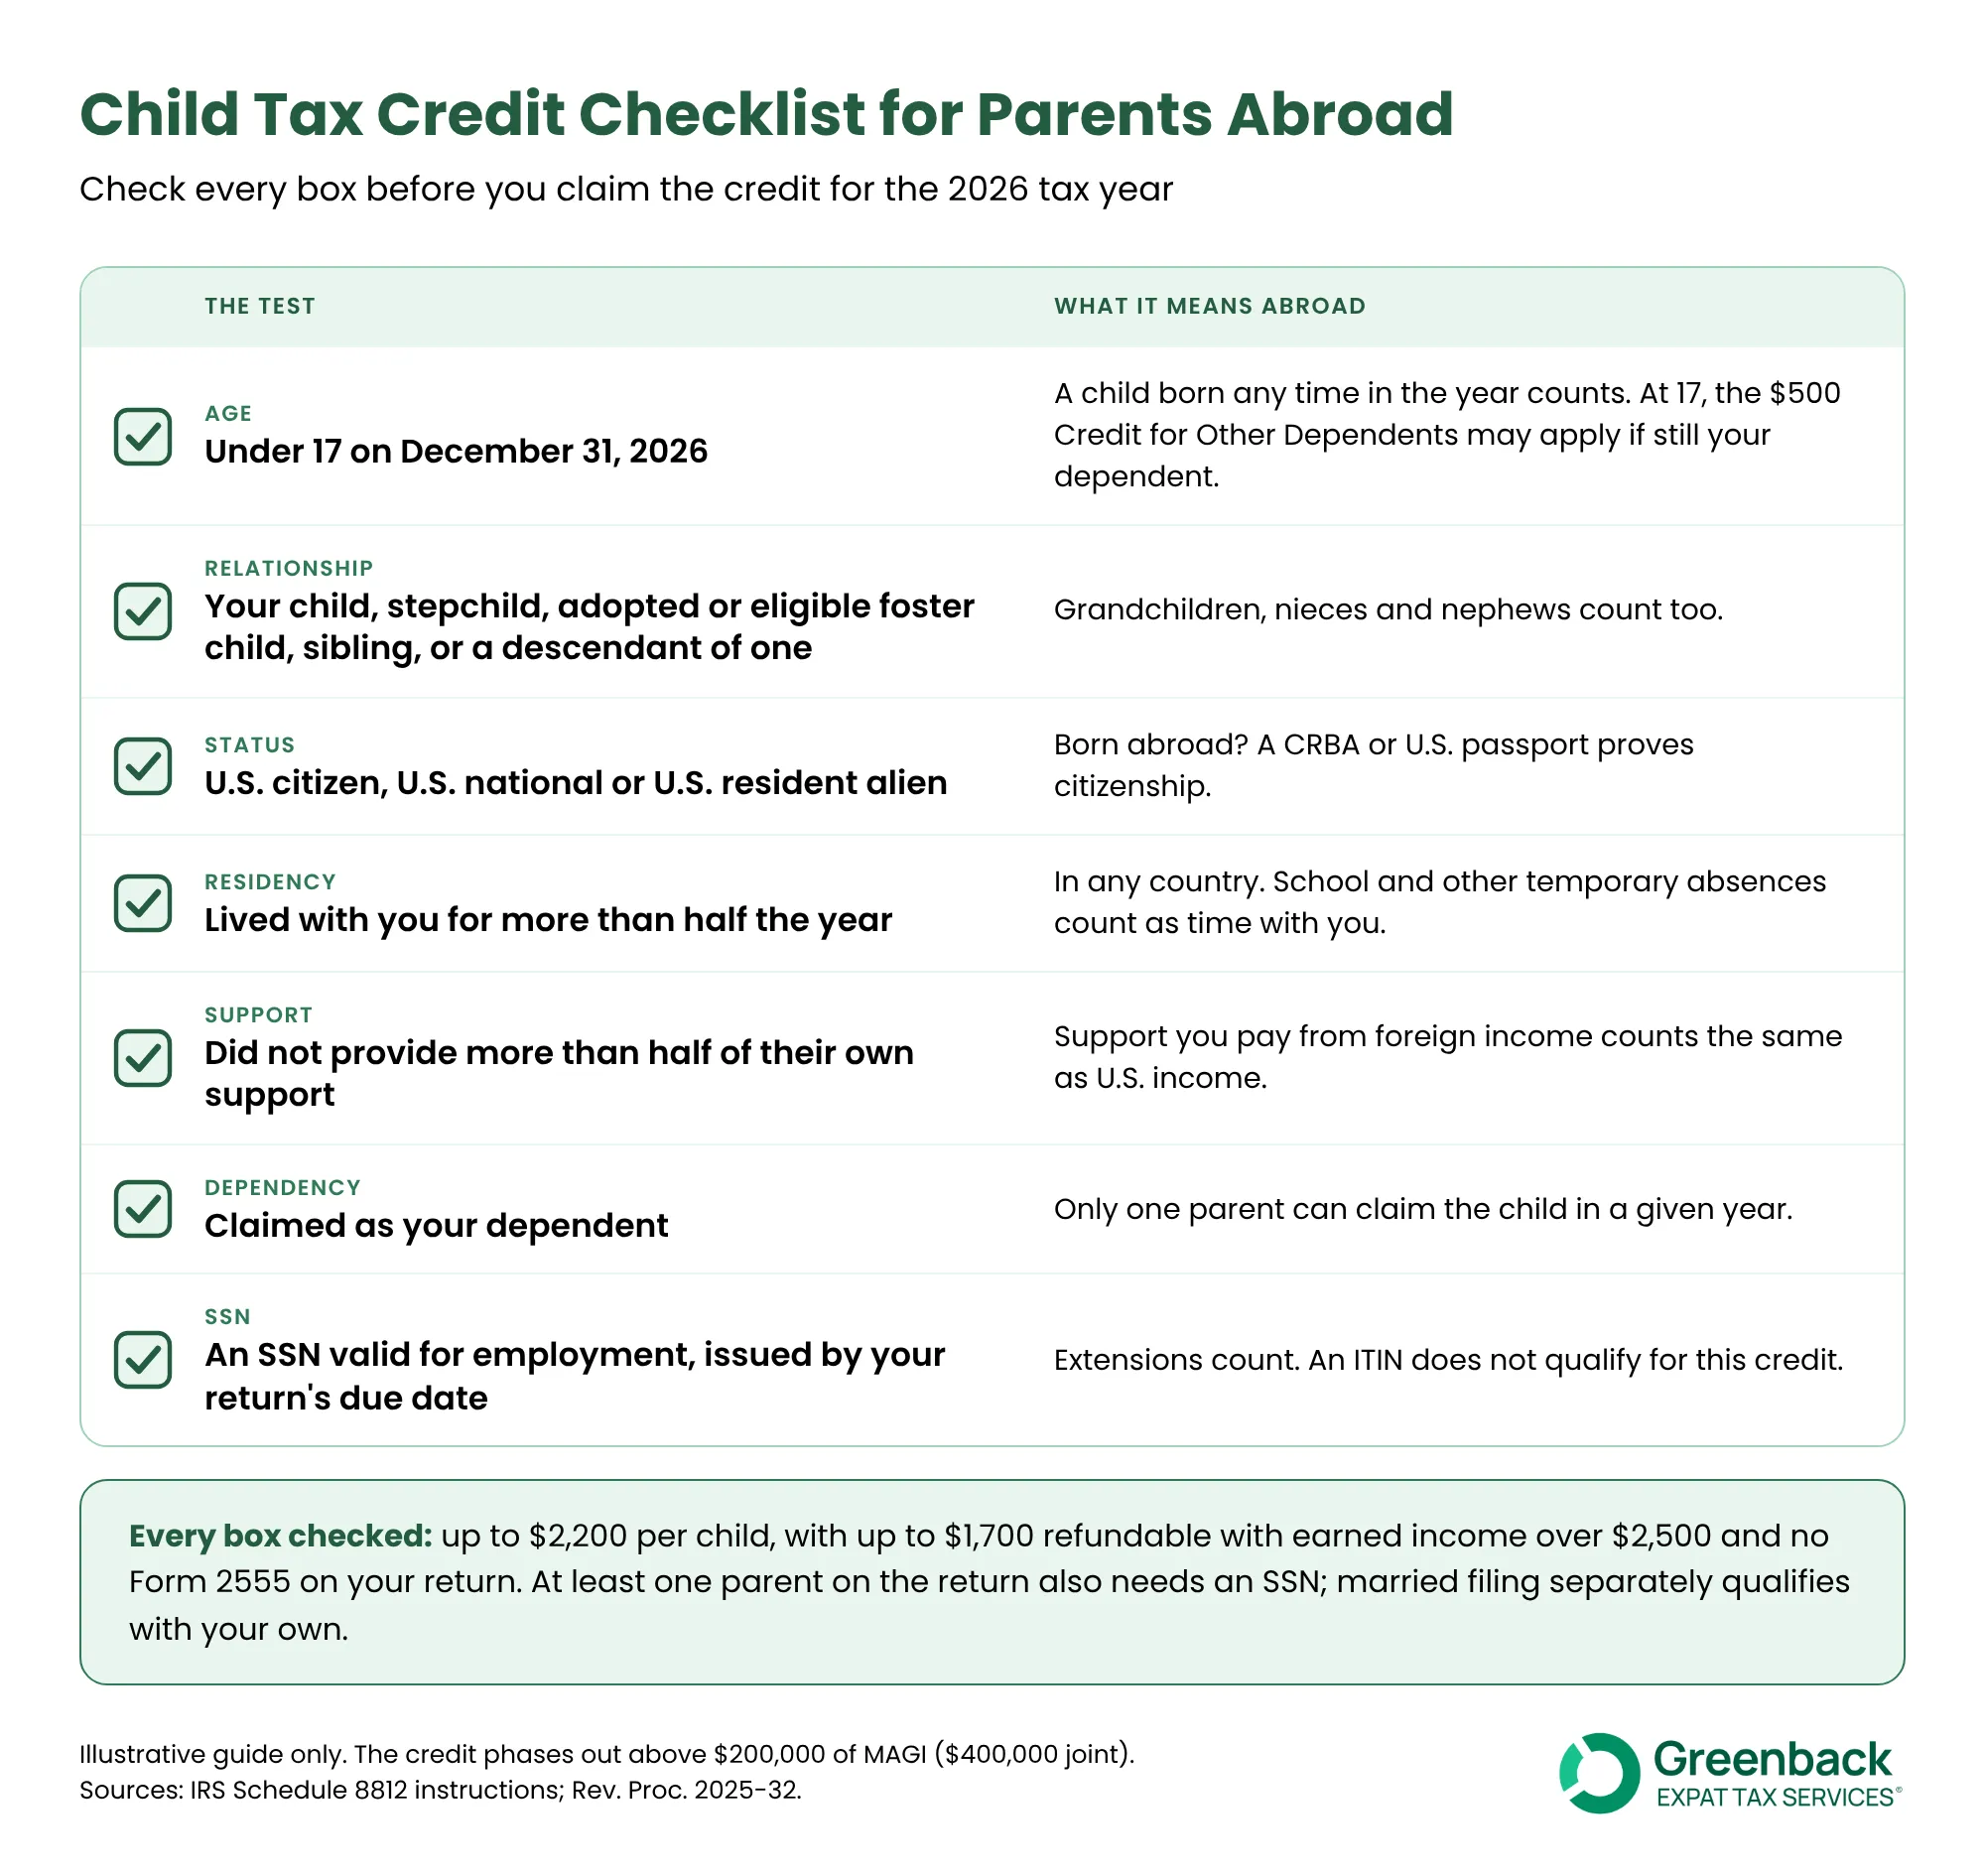
A qualifying child for the 2026 tax year meets all of these tests:
- Age: Under 17 on December 31, 2026. A child born at any point in the year, even December 31, is treated as having lived with you all year.
- Relationship: Your son, daughter, stepchild, adopted child, eligible foster child, brother, sister, half-sibling or step-sibling, or a descendant of one of them, such as a grandchild, niece, or nephew.
- Status: A U.S. citizen, U.S. national, or U.S. resident alien.
- Residency: Lived with you for more than half the year. Temporary absences for school, medical care, or vacation count as time lived with you.
- Support: Did not provide more than half of their own support.
- Dependency: Claimed as your dependent on your return.
- SSN: Valid for employment and issued by the due date of your return, including extensions. An Individual Taxpayer Identification Number (ITIN) does not qualify.
These requirements apply whether you file from Toronto or Tokyo.
2. One Parent Needs an SSN, and Married Filing Separately Still Qualifies
The One Big Beautiful Bill Act (OBBBA) added an SSN rule for parents. On a joint return, only one spouse needs an SSN valid for employment, and the other can file with an ITIN. Married filing separately (MFS) does not disqualify you: a separate filer with their own SSN can claim the full credit, and the phaseout starts at $200,000 of modified adjusted gross income (MAGI). Our guide to TINs, SSNs, and ITINs explains what each number does on a return.
3. A Child Born Abroad Needs Proof of Citizenship and an SSN
A child born abroad is not automatically a U.S. citizen. Citizenship depends on the U.S. parents’ prior physical presence in the United States, which most families document with a Consular Report of Birth Abroad (CRBA). The CRBA or a U.S. passport then supports the SSN application from abroad. If a newborn’s SSN will not arrive in time, extending your return also extends the deadline for the number. A child with only an ITIN can still bring the $500 Credit for Other Dependents (more on qualifying with an ITIN).
How Much Is the Child Tax Credit Worth?
The Child Tax Credit is worth up to $2,200 per qualifying child for the 2026 tax year. Up to $1,700 per child is refundable, paid at 15% of your earned income above $2,500. The credit shrinks by $50 for every $1,000 of MAGI above $200,000, or $400,000 on a joint return.
1. The Phaseout Starts at $200,000, or $400,000 for Joint Filers
| Item | 2026 tax year |
|---|---|
| Maximum credit per qualifying child | $2,200 |
| Refundable portion per child (ACTC) | Up to $1,700 |
| Earned income needed for any refund | More than $2,500 |
| Phaseout begins (married filing jointly) | $400,000 MAGI |
| Phaseout begins (all other statuses, including MFS) | $200,000 MAGI |
2. The Refund Equals 15% of Earned Income Over $2,500
The refundable credit equals (earned income minus $2,500) multiplied by 15%, capped at $1,700 per child. A part-time teacher in Lisbon with one child, $9,000 of wages, and no Form 2555 receives $975: $6,500 over the floor, times 15%. A parent of one child reaches the full $1,700 at $13,834 of earned income.
Earned income means wages, salaries, tips, and net self-employment earnings. Interest, dividends, rent, pensions, and Social Security benefits do not count. Families with three or more children can also use a formula based on U.S. Social Security and Medicare taxes paid. However, a parent paid by a foreign employer usually pays neither.
3. Excluded Foreign Income Still Counts Toward the Phaseout
For this credit, MAGI adds back any foreign earned income and housing amounts excluded on Form 2555, so the FEIE does not keep you under the $200,000 or $400,000 threshold. Sarah, a single parent in Germany earning $230,000 with two children, is $30,000 over the limit. Her $4,400 credit falls by $1,500 to $2,900, whether or not she excludes any income.
Does the FEIE Disqualify You From the Additional Child Tax Credit?
Yes, a taxpayer who files Form 2555 to exclude foreign-earned income is not eligible to claim the Additional Child Tax Credit (ACTC). That holds whatever other income you report, including U.S. wages. The nonrefundable part still reduces U.S. tax on income that the exclusion does not reach, such as U.S. rental income or wages above the $132,900 limit.
1. Any Form 2555 on the Return Removes the Refund
In the year you move abroad, the FEIE is prorated based on your qualifying days and may cover only part of your salary, yet filing Form 2555 for that portion removes the refundable credit for the whole year. Claiming only the housing exclusion counts too, since it is also made on Form 2555.
2. One Spouse’s Form 2555 Affects the Whole Joint Return
On a joint return, if either spouse files Form 2555, the return cannot claim the refundable credit for any child. A couple where one spouse earns $70,000 and the other earns $25,000 cannot exclude the $25,000 salary and still claim the refundable credit.
3. Using the FEIE and FTC Together Also Blocks the Refund
Many higher earners claim the Foreign Earned Income Exclusion up to the $132,900 limit and the Foreign Tax Credit for income above that amount. That combination includes Form 2555, so it removes the refundable credit. When refundability matters, compare FEIE plus FTC against FTC alone.
Should You Use the FEIE or the Foreign Tax Credit?
Filing with the Foreign Tax Credit alone usually beats the FEIE when your foreign income tax exceeds your U.S. tax minus your full Child Tax Credit, which is $4,400 for two children. With no local income tax, as in Saudi Arabia, the FEIE usually wins once your U.S. tax tops the full credit.
1. The FTC Can Win Even Where Local Tax Is Low
These three families file jointly with two children, using 2026 brackets and the $32,200 standard deduction.
| Family | U.S. tax before credits | Local income tax | FEIE result | FTC-only result |
|---|---|---|---|---|
| Bristol, UK, $108,000 | $8,600 | About $27,000 | $0 | $3,400 refund |
| Singapore, $100,000 | $7,640 | About $6,000 | $0 | $2,760 refund |
| Riyadh, Saudi Arabia, $88,000 | $6,200 | $0 | $0 | $1,800 owed |
The Singapore family pays less local tax than the U.S. would charge, and the FTC still wins by $2,760. Their $6,000 credit leaves $1,640 of U.S. tax; the Child Tax Credit absorbs it, and the remaining $2,760 comes back as a refund. In Bristol, unused UK tax of about $18,400 can be carried forward for up to 10 years. In Riyadh, U.S. tax absorbs the full $4,400 credit, so the FEIE saves $1,800.
2. Self-Employed Parents Still Owe Self-Employment Tax
A freelance designer in Berlin, filing jointly with a spouse who has no income, with $80,000 of net self-employment income and two children, owes $11,304 of U.S. self-employment tax under either method. Neither the FEIE nor the FTC reduces self-employment tax. With the FEIE, she owes the full $11,304; with the FTC alone, German tax offsets $4,562 of U.S. income tax, and the $3,400 refundable credit reduces what she owes to $7,904. A Certificate of Coverage under the U.S.-Germany totalization agreement can remove the self-employment tax itself.
3. Switching Off the FEIE Has a Five-Year Cost
If you have claimed the FEIE before and switch to the FTC, you generally cannot claim the exclusion again for five tax years without IRS approval. A family planning a move from London to Dubai in two years should run that future year too. If you still file a state return, state tax rules can shift the comparison. See FEIE Revocation rules.
Can You Claim the Credit If Your Child Lives Abroad?
You can claim the Child Tax Credit for a child who lives abroad with you, since the residency test only asks whether your child lived with you for more than half the year. A child living in another country, apart from you, usually fails that test unless the time apart is a temporary absence, such as school.
1. A Child Abroad With You Qualifies
A child living with you in Madrid qualifies the same way a child living with you in Ohio does. The child still needs a U.S. citizen, national, or resident alien status and an SSN.
2. A Child Abroad Without You Usually Does Not
When your child lives in another country without you, the Child Tax Credit is generally unavailable. The exception is a divorced or separated parent: if your child lives abroad with the other parent, that parent can release the claim to you on Form 8332. Boarding school, university, medical care, and vacation still count as time with you. See whether studying abroad affects the Child Tax Credit.
How Do You Claim the Child Tax Credit From Abroad?
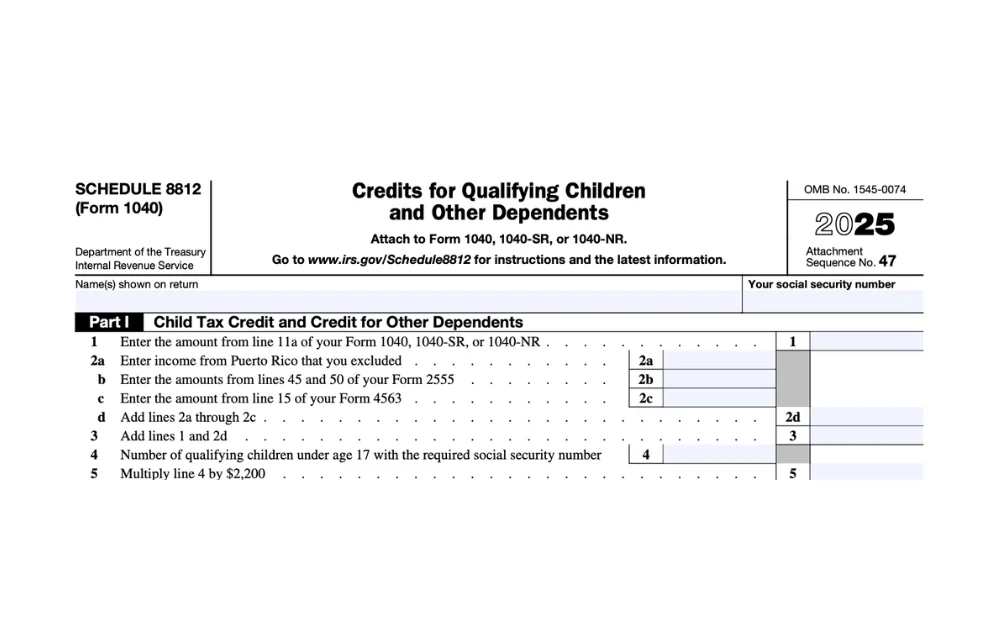
You claim the Child Tax Credit on Schedule 8812, attached to your Form 1040 alongside either Form 2555 or Form 1116. Schedule 8812 adds back any excluded income to find MAGI, applies the phaseout, and calculates both the nonrefundable and refundable parts.
Schedule 8812 Comes Last, After Your Foreign Income Forms
- Confirm each child’s SSN: It must be issued by the due date of your return, including extensions.
- Choose your method for foreign income: Compare the FEIE with the FTC alone before you file.
- Prepare Form 1040: Report your worldwide income.
- Attach the form for your method: Form 2555 for the exclusion, which flows to Schedule 1, or Form 1116 for the credit.
- Complete Schedule 8812: List each child’s name, SSN, and relationship to you. Our Form 8812 guide walks through it line by line.
- File by your deadline: Expats get an automatic extension to file (see expat tax deadlines). You can e-file a return that claims the credit, though by law the IRS cannot issue a refund that includes the ACTC before mid-February.
Can You Claim the Child Tax Credit for Past Years?
You can generally claim a missed Child Tax Credit by filing an amended return within three years of the date you filed the original, or two years from when you paid the tax, whichever is later. Form 1040-X can be filed electronically for tax years 2022 and later.
1. Amended Returns Reach Back About Three Years
The window covers a credit you missed entirely, a refundable part you never claimed, and a child whose SSN arrived after you filed, but by the due date. File an amended tax return with Schedule 8812 for each year.
2. Dropping Form 2555 on an Amendment Can Revoke the FEIE
A missed refund often appears when you rerun a prior year with the FTC in place of the FEIE. An amended return that drops Form 2555 to claim the refundable credit can be treated as a revocation of the exclusion, which starts the five-year wait. Run every affected year before filing the first amendment.
3. Unfiled Years Go Through Streamlined Filing
If you are behind on filing, the Streamlined Filing Compliance Procedures let expats catch up on three years of returns and six years of FBARs without penalties, and those returns can claim the Child Tax Credit for children with an SSN by each year’s due date.
What Did the One Big Beautiful Bill Act Change?
The One Big Beautiful Bill Act, signed July 4, 2025, raised the credit to $2,200, made it permanent, indexed it for inflation, and added the parent SSN rule. The 2026 adjustment left the amounts at $2,200 and $1,700. Our news analysis of the OBBBA Child Tax Credit rules covers what it means for expat families.
The FEIE Restriction Carried Over Unchanged
The Form 2555 restriction on the refundable credit stayed, along with the $2,500 earned income floor, the under-17 age limit, and the child SSN rule.
Frequently Asked Questions about Child Tax Credit
A child who lives with you in another country can be your dependent, and claiming the Child Tax Credit for that child also takes U.S. citizen, national, or resident alien status and an SSN. For a child living abroad without you, see claiming a child as a dependent while they study abroad.
The Child Tax Credit is lost when the child has no SSN by the return’s due date, is 17 or older on December 31, or did not live with you for more than half the year, or when MAGI phases the credit out. For expats, filing Form 2555 removes the refundable part.
The former $2,000 Child Tax Credit is now $2,200 per child. You qualify with a child under 17 who has a valid SSN, an SSN for at least one parent on the return, and MAGI low enough that the phaseout, which starts at $200,000 ($400,000 joint), leaves part of the credit.
You can claim the Child Tax Credit with a nonresident spouse by filing married filing separately with your own SSN, as head of household if you qualify, or jointly after electing to treat your spouse as a U.S. resident. Married filing separately keeps your spouse’s foreign income off your return.
Only one parent can claim the Child Tax Credit for a child in a given year, usually the parent with whom the child lived for more than half the year. That parent can release the claim to the other by signing Form 8332.
The Child Tax Credit stops in the year your child turns 17. If the child is still your dependent, you may claim the nonrefundable $500 Credit for Other Dependents instead.
Greenback Helps American Families Living Abroad File with Confidence
If your foreign income tax comes anywhere near your U.S. bill, the Foreign Tax Credit can clear what you owe and still pay up to $1,700 per child. If you live in a country with no income tax, the exclusion usually leaves you better off.
Greenback’s accountants can run your return both ways before you file, so you see the dollar difference for your family and your plans for the next few years. If you missed the refundable credit before, Greenback can tell you which years are still open.

See What Each Method Means for Your Family
This article is general guidance, not legal or tax advice. Figures reflect the 2026 tax year per IRS Rev. Proc. 2025-32; credit mechanics follow the current Schedule 8812 instructions. Scenarios are rounded, with approximate local tax. Consult a tax professional with expertise in U.S. expat taxes before acting.
Featured In