U.S. Exit Tax (Expatriation Tax): Who Pays It and How It Works

- What Is the U.S. Exit Tax?
- Who Is a Covered Expatriate?
- Which Green Card Holders Owe the Exit Tax?
- How Is the U.S. Exit Tax Calculated?
- How Are IRAs, 401(k)s and Pensions Treated?
- What Do You File When You Expatriate?
- How Can You Reduce or Avoid the Exit Tax?
- Frequently Asked Questions about the U.S. Exit Tax
- Your Status on Your Expatriation Date Decides the Exit Tax
The U.S. exit tax (expatriation tax) applies when you renounce U.S. citizenship or end a green card you held in at least 8 of the last 15 tax years, but only if you are a covered expatriate. You are a covered expatriate if your net worth is $2 million or more, your average annual net income tax for the prior five years is more than $211,000 (for 2026 expatriations), or you can’t certify five years of tax compliance on Form 8854. Our guide to renouncing U.S. citizenship covers the renunciation process itself.
A covered expatriate is taxed as if they sold everything they own the day before expatriating. Gains above $910,000 for 2026 are taxed, retirement accounts and pensions follow their own rules, and everyone who expatriates files Form 8854, covered or not.
If you arrived here looking for “expatriate tax,” the everyday tax rules that apply while you live abroad, that is a different subject. This guide covers the U.S. exit tax, which applies when someone gives up citizenship or long-term green card status. For annual filing from abroad, start with our U.S. expat taxes guide, or read how the two terms differ.
What Is the U.S. Exit Tax?
The U.S. exit tax is a one-time tax on the unrealized gains in your worldwide assets, charged when a covered expatriate gives up U.S. citizenship or long-term green card status. It applies only to U.S. citizens and long-term residents, so H-1B, L-1, F-1, and other visa holders who have never held a green card are excluded.
You don’t have to sell anything. The tax treats your property as sold at its fair market value on the day before your expatriation date, and taxes the profit that has built up while you owned it.
A Deemed Sale Taxes Gains You Haven’t Cashed In
These terms decide the size of that profit:
- Fair market value: the price a willing buyer would pay for the asset on the day before you expatriate, such as an appraisal for a home or the closing price for listed shares.
- Basis: usually what you paid, plus improvements. A home bought for $500,000 with $100,000 of renovations has a basis of $600,000.
- Unrealized gain: fair market value minus basis. It is profit that exists on paper, which the U.S. normally taxes only when you sell. The exit tax is the exception.

Thinking About Renouncing or Giving Up Your Green Card?
Who Is a Covered Expatriate?
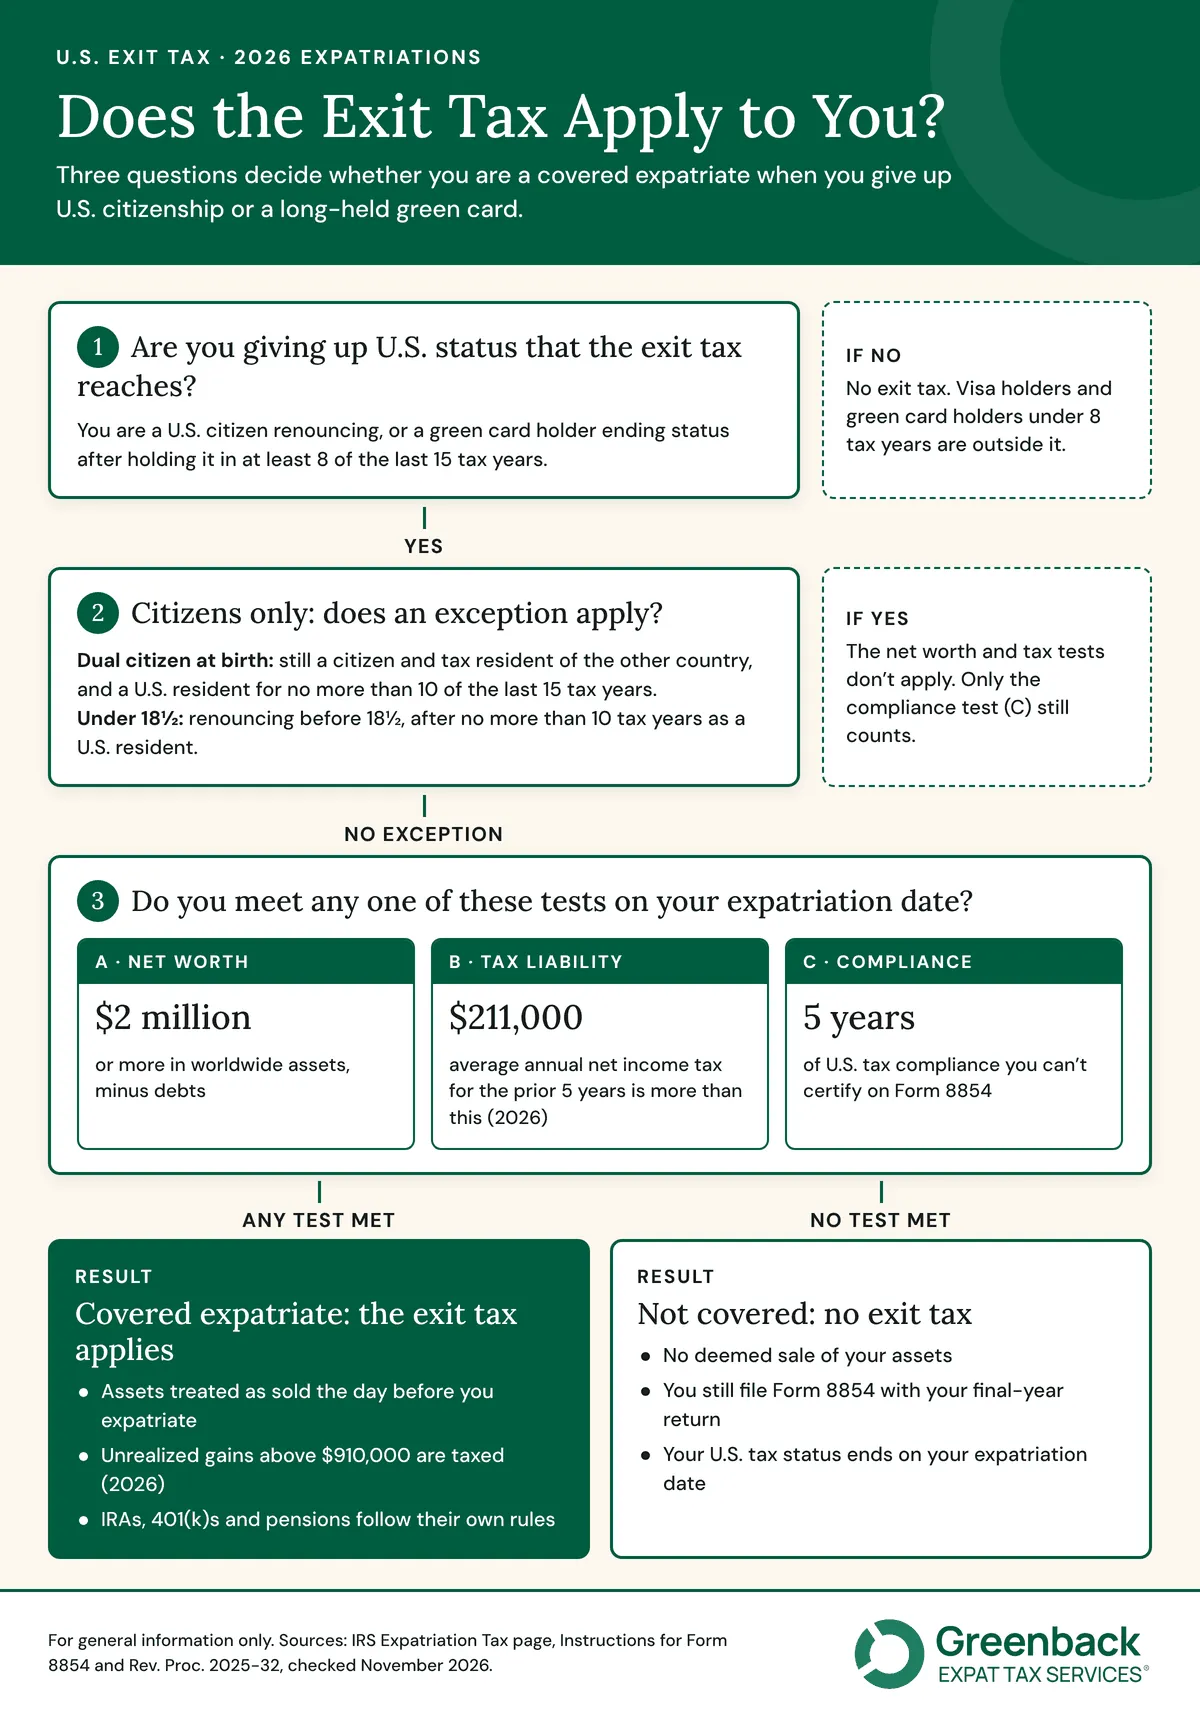
A covered expatriate is a U.S. citizen or long-term resident who, on the expatriation date, meets at least one of three tests: net worth of $2 million or more, average annual net income tax above $211,000 for the five prior tax years (2026 figure), or failure to certify five years of U.S. tax compliance on Form 8854. Meeting one test is enough.
Net Worth Test
You meet this test if your net worth is $2 million or more on the date of your expatriation. Net worth counts your worldwide assets, including homes, investments, business interests, and retirement accounts, minus your debts, such as a mortgage. The $2 million figure is not adjusted for inflation.
Tax Liability Test
You meet this test if your average annual net income tax for the five tax years before your expatriation year is more than $211,000 for 2026 expatriations. The IRS adjusts this figure each year. Net income tax is the U.S. income tax left after credits, so many Americans abroad who use the Foreign Earned Income Exclusion (FEIE) or the Foreign Tax Credit (FTC) have a U.S. net income tax far below the threshold, even on a high salary.
Compliance Test
You meet this test if you can’t certify on Form 8854 that you complied with all U.S. federal tax obligations for the five tax years before your expatriation year. It applies regardless of your wealth. The certification covers your returns and information returns for those years, and many people also bring foreign account reports, such as the FBAR, up to date before they certify.
You can catch up before your expatriation date, and former citizens have a path afterward.
Two IRS programs help:
- Streamlined Filing Compliance Procedures: for non-willful filers who are behind on returns and FBARs. Our Streamlined filing guide covers who qualifies.
- Relief Procedures for Certain Former Citizens: for people who renounced after March 18, 2010, have no U.S. filing history, have a net worth under $2 million, didn’t exceed the tax liability threshold, and had $25,000 or less in total net tax liability for the five years before expatriation plus the expatriation year. The conduct must be non-willful, and the program is open to former citizens only. Our FAQ on renouncing without filing back taxes explains how it works.
If you’re behind on U.S. returns or FBARs, Greenback prepares catch-up filings through the Streamlined Filing Procedures for Americans who want to bring their filings current before they expatriate.
Exceptions for Dual Citizens at Birth and Minors
Two exceptions apply only to U.S. citizens. They switch off the net worth and tax liability tests, but you still have to certify five years of compliance on Form 8854.
- Dual citizens at birth: you became a U.S. citizen and a citizen of another country at birth, you are still a citizen of that country and taxed as its resident on your expatriation date, and you were a U.S. resident for no more than 10 of the last 15 tax years. Our guides to taxes for dual citizens and accidental Americans cover the yearly filing side.
- Minors: you renounce before age 18½ and were a U.S. resident for no more than 10 tax years before renouncing.
Which Green Card Holders Owe the Exit Tax?
Green card holders face the U.S. exit tax only as long-term residents: lawful permanent residents in at least 8 of the last 15 tax years ending with the year they end their status. Years in which you were treated as a resident of another country under a tax treaty, without waiving its benefits, don’t count toward the 8. A long-term resident who meets one of the three covered tests is a covered expatriate on the same terms as a citizen.
Ending Your Green Card Status
Letting a green card expire does not end your U.S. tax residency. You end it by formally abandoning your status, usually with USCIS Form I-407, or by having your status revoked or ruled abandoned. Long-term residents also file Form 8854. Our guide to abandoning a green card walks through the steps.
A treaty position can also end long-term residency. If you begin to be treated as a resident of another country under a tax treaty, don’t waive the treaty’s benefits, and notify the IRS; that date can become your expatriation date, with the exit tax rules attached.
Leaving Before Your 8th Year
The “7-year rule” people search for comes from this count: ending your status before you reach 8 tax years as a green card holder keeps you outside the exit tax entirely. The count is based on tax year, so it can differ from the anniversary on your card. Confirm your number with a tax preparer before you set a date. Our FAQ on surrendering a green card before 8 years covers the timing.
How Is the U.S. Exit Tax Calculated?
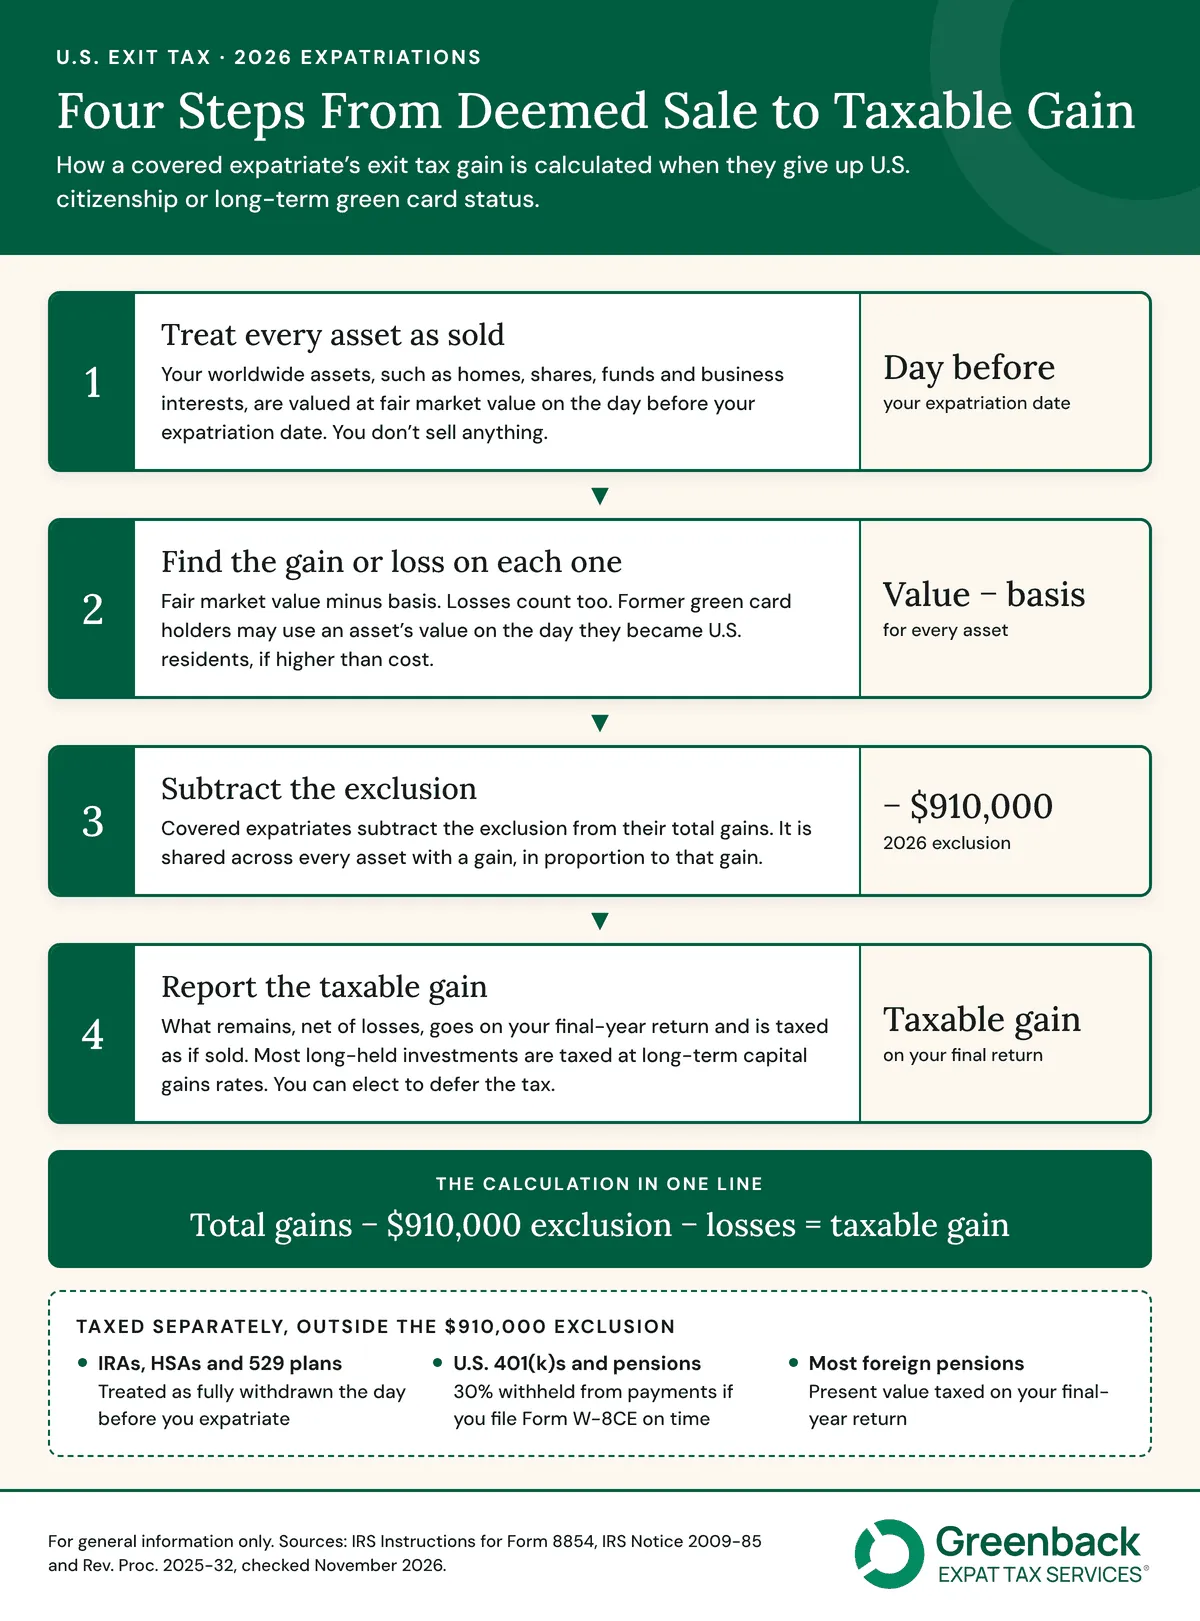
There is no separate exit tax rate. Each asset you own is treated as sold at fair market value on the day before your expatriation date, and the gain is taxed as if you had sold it, so most long-held investments are taxed at long-term capital gains rates. Covered expatriates subtract an exclusion of $910,000 for 2026 from their total gains first.
The calculation runs in four steps:
- List your worldwide assets on the day before your expatriation date, including homes, shares, funds, business interests, and foreign capital assets.
- Find the gain or loss on each one: fair market value minus basis.
- Subtract the exclusion from your total gains ($910,000 for 2026).
- Report what remains, net of any losses, as gain on your final-year return, taxed under the normal rules for each type of asset.
For example, say your shares carry a gain of $1,200,000 and your home a gain of $300,000, for a total of $1,500,000. After the $910,000 exclusion, $590,000 of gain is taxable. Retirement accounts are excluded from this calculation and taxed under their own rules, as covered in the next section. Our FAQ on how the exit tax exclusion amount is calculated explains how the figure is set each year.
The Exclusion Is Shared Across All Your Gains
You can’t choose which assets get the exclusion. IRS Notice 2009-85 spreads it across every asset with a gain, in proportion to that gain. In the example above, the shares absorb $728,000 of the exclusion and the home $182,000, leaving $472,000 and $118,000 taxable.
Losses count too. An asset worth less than its basis produces a loss in the same deemed sale, and the wash sale rule does not apply to it. If the same person also held a fund with a $100,000 loss, the taxable result would fall to $490,000, without selling anything before leaving. Foreign homes and land are treated as deemed sales like any other asset; our FAQ on the exit tax and foreign real estate covers them.
Basis Step-Up for Former Green Card Holders
Long-term residents can measure the gain on assets they owned before moving to the U.S. from their value on the day they first became a U.S. resident. If that value is higher than their cost, it serves as the basis for the exit tax calculation only. U.S. real property doesn’t qualify, and you can elect out on a per-asset basis on Form 8854.
For example, a green card holder who bought shares abroad for $200,000, saw them worth $500,000 on the day they became a U.S. resident, and holds them at $900,000 on the day before expatriating has a $400,000 gain for the exit tax, instead of $700,000.
Deferring the Tax
You can elect to defer the tax on the deemed sale of each asset until you sell it. The election is irrevocable and is made asset by asset. You must provide adequate security, such as a bond, pay interest for the deferral period, and waive any treaty right that would block the IRS from collecting. Our FAQ on the exit tax deferral election explains the process.
How Are IRAs, 401(k)s and Pensions Treated?
Retirement accounts sit outside the $910,000 exclusion and fall into two groups: IRA-type accounts, taxed as if fully withdrawn the day before you expatriate, and U.S. employer plans and pensions, which can be taxed as you receive payments if you file Form W-8CE on time. Which group an account falls into determines when the tax is due.
| Account | How it is treated | What you do |
|---|---|---|
| Traditional and Roth IRAs, HSAs, 529 plans, ABLE accounts, Coverdell accounts, Archer MSAs | Treated as if you withdrew the whole balance the day before your expatriation date, taxed under that account’s usual rules, with no early distribution penalty | Report the deemed distribution on your final-year return |
| U.S. 401(k)s, 403(b)s and pensions, with Form W-8CE | Taxed as you receive payments; the plan withholds 30% of each taxable payment | File Form W-8CE with the plan on time and give up treaty rate reductions |
| Plans without a timely Form W-8CE, and most foreign pensions | The present value of your accrued benefit is taxed as if received the day before your expatriation date | Report it on your final-year return |
SEP and SIMPLE IRAs follow the employer-plan rows. The taxable part of distributions from a nongrantor trust you benefit from is also subject to 30% withholding. Our guides to IRAs for expats, 401(k)s for expats and foreign pensions cover how each account is taxed day-to-day.
Filing Form W-8CE on Time
Form W-8CE is due by the earlier of the day before your first distribution after expatriating or 30 days after your expatriation date. Miss it, and the plan moves to the third row: the present value of the benefit is taxed on your final-year return.
Most foreign pensions automatically fall into that third row because the payer is not a U.S. person. The part of a benefit earned from work outside the U.S. while you were not a U.S. citizen or resident is left out of these rules. Our article on renouncing and your 401(k) walks through the choices for U.S. plans.
Choosing Between Withholding and Paying Now
Filing Form W-8CE trades one tax bill now for 30% withheld from each future payment, with no treaty relief. Letting the benefit be taxed at expatriation means paying at your own rates on the present value in one year. Which costs less depends on the size of the benefit, when you expect to draw it, and your tax rates in each year, so it is worth comparing both before the deadline.
What Do You File When You Expatriate?
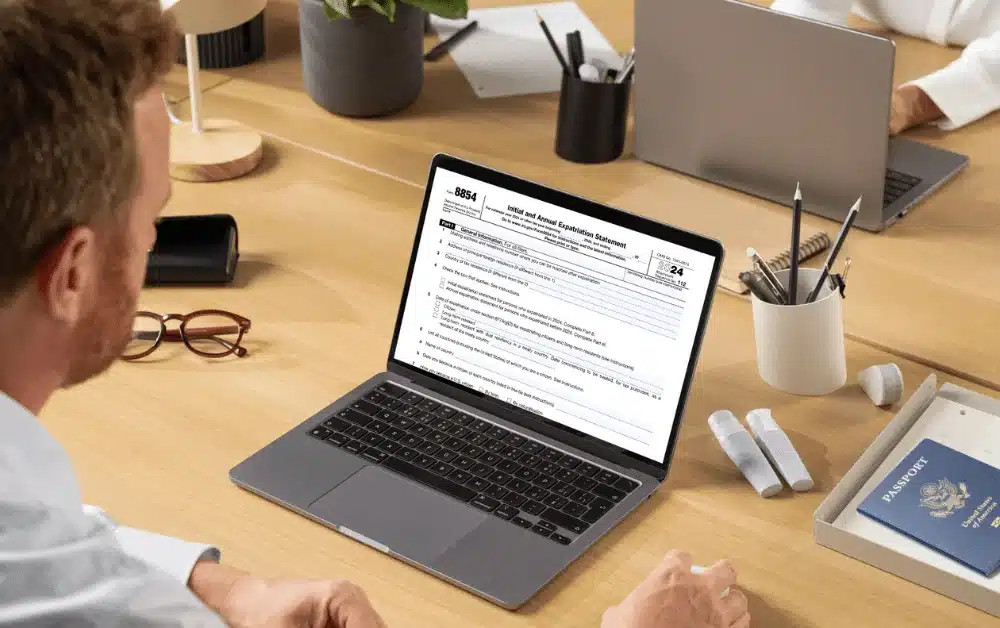
In the year you expatriate, you file a final U.S. income tax return and attach your initial Form 8854 by the return’s due date, including any extensions. The year is usually split into a resident and a nonresident part, so many expatriates file a dual-status return. The IRS can impose a $10,000 penalty for failing to file Form 8854 when required.
A few details matter on that return:
- Expatriation date for citizens: the day you renounce before a U.S. consular officer, provided the State Department later confirms it with a Certificate of Loss of Nationality.
- Expatriation date for long-term residents: usually the day you abandon your status with Form I-407, or the treaty date described above.
- Annual Form 8854: required in later years if you deferred tax, hold an eligible deferred compensation item, or hold an interest in a nongrantor trust.
Your state return follows that state’s own residency rules, so expatriating doesn’t by itself end your state residency. Our article on the California exit tax covers one state’s example.
Our Form 8854 guide covers the form part by part, and our FAQ on tax obligations after renouncing U.S. citizenship covers what you may still file afterward. Greenback’s accountants prepare final-year returns and Form 8854 for Americans renouncing and green card holders ending their status, and an expat tax consultation can help you plan the year before you set a date.
How Can You Reduce or Avoid the Exit Tax?
You can reduce or avoid the U.S. exit tax primarily by taking steps before your expatriation date, because your covered status and the values in the deemed sale are fixed on that day. The main levers are:
- Compliance: catching up on returns and FBARs, so the compliance test doesn’t make you covered (see the Compliance Test above).
- Timing: for green card holders, the 8-year count; for everyone, which five years fall in the tax liability test.
- Retirement accounts: deciding on Form W-8CE before the deadline (see the retirement section above).
- Gifts: completed gifts made before you expatriate, with their own rules below.
Our guide to renouncing and retiring with ease covers Social Security and retirement planning around the move.
Gifts Before You Expatriate
Assets you give away in completed, irrevocable gifts before your expatriation date are no longer yours on that date, so they leave your net worth and your deemed sale. U.S. gift tax rules still apply:
- A spouse who is a U.S. citizen: gifts generally qualify for the unlimited marital deduction.
- A spouse who is not a U.S. citizen: up to $194,000 for 2026 is excluded each year.
- Anyone else: up to $19,000 per recipient for 2026 is excluded; larger gifts are reported on Form 709 and count against your lifetime exemption.
Gifts before expatriation are a planning decision with estate, family and legal consequences, so get advice from your tax and legal advisors before you act. Our foreign gift tax guide covers the gift side in more detail.
Gifts and Bequests After You Expatriate
Once you are a covered expatriate, gifts and bequests you later make to U.S. citizens or residents can trigger the Section 2801 tax, which the recipient pays at 40% on the amount above the annual exclusion ($19,000 for 2026) and reports on Form 708. Our FAQ on the Section 2801 tax on gifts from covered expatriates explains who is responsible for filing it.
Frequently Asked Questions about the U.S. Exit Tax
Do Any U.S. States Have an Exit Tax?
States do not apply the U.S. exit tax, which is a federal tax tied to U.S. citizenship and long-term green card status. State income tax depends on state residency, which ends under each state’s own rules. Some states may keep treating you as a resident after you move abroad if you keep a home, a driver’s license, or voter registration there, so ending state residency is a separate step from renouncing.
Does the U.S. Exit Tax Apply to H-1B and Other Visa Holders?
The U.S. exit tax does not apply to H-1B, L-1, F-1, J-1, or other visa holders who never held a green card. It applies only to U.S. citizens and long-term residents, meaning lawful permanent residents who have been in the U.S. for at least 8 of the last 15 tax years. A visa holder who leaves the U.S. may still file a final-year return as a resident or dual-status filer.
Does the U.S. Exit Tax Apply to Foreign Real Estate?
The U.S. exit tax applies to foreign real estate owned by a covered expatriate in the same way as other assets. The property is treated as sold at fair market value on the day before the expatriation date, and its gain shares in the $910,000 exclusion for 2026. Former green card holders may measure gain from the property’s value on the day they first became U.S. residents.
What Are the Tax Implications of Abandoning a Green Card?
Abandoning a green card ends U.S. tax residency from the expatriation date, after which a former green card holder is generally taxed as a nonresident alien on U.S.-source income only. The year of the change is usually reported on a dual-status return with Form 8854 attached. A long-term resident who meets a covered test is also a covered expatriate for that year.
Your Status on Your Expatriation Date Decides the Exit Tax
Covered status, the exceptions, and the value of each asset are all fixed on your expatriation date, so most decisions that change your result happen before it: getting compliant, checking your green card count, and valuing your assets. The Form W-8CE decision follows within 30 days, and the deferral and step-up elections are made on your return. The IRS expatriation tax page lists the inflation-adjusted figures by year.
If you’re a dual citizen deciding whether to renounce, a specialist can confirm whether an exception applies to you before you book a consular appointment. Learn more about how we help dual citizens. If you’re a green card holder leaving the U.S. midyear, your final return will likely be a dual-status return. Learn more about how we help dual-status filers.

Exit Tax Questions Are Easier With an Expert
This article provides general information about the U.S. exit tax for 2026 expatriations. Exit tax outcomes depend on your full financial picture, so speak with a qualified tax professional before renouncing U.S. citizenship or ending green card status.
Featured In


