FEIE vs. FTC: How to Choose Between the Exclusion and the Credit

- What Is the Difference Between the FEIE and the FTC?
- How Do the FEIE and FTC Compare on the Same Income?
- Which Is Better for You, the FEIE or the FTC?
- Can You Use the FEIE and FTC Together?
- Can You Switch Between the FEIE and FTC?
- Frequently Asked Questions about FEIE vs. FTC
- Your Foreign Tax Rate and Family Decide Between the Exclusion and the Credit
For Americans living abroad, the FEIE and the FTC are the two main ways to avoid being taxed twice on the same income. The Foreign Earned Income Exclusion (FEIE) excludes up to $132,900 of foreign earned income from your 2026 tax return, filed in 2027. The Foreign Tax Credit (FTC) subtracts the income tax you paid to another country from your U.S. tax, dollar for dollar, up to the U.S. tax on that foreign income. The FEIE often fits countries with little or no income tax. The FTC often fits countries with tax rates close to or above U.S. rates. Neither one is better for everyone, because children, income above the exclusion limit, IRA contributions, and investment income can each change the answer.
You can use both on the same return, but not on the same income. The FEIE is claimed on Form 2555 and the FTC on Form 1116. Filing Form 2555 rules out the refundable child tax credit, worth up to $1,700 per child for 2026, and excludes wages from counting as compensation for IRA contributions. Unused foreign tax credit carries back 1 year and forward up to 10 years, while an unused exclusion is lost. If you revoke the FEIE, you need IRS approval to choose it again within 5 tax years. This guide runs the same income through both options, shows when each one fits, and explains how to combine them or switch between them.
What Is the Difference Between the FEIE and the FTC?
The FEIE removes qualifying foreign earned income from your taxable income, while the FTC keeps all of your income on the return and credits the foreign income tax you paid against your U.S. tax. The FEIE has a dollar limit and a residency or physical presence test. The FTC has no residency test, but the credit is limited to the U.S. tax on your foreign income.
The Foreign Earned Income Exclusion is claimed on Form 2555 and requires you to meet the physical presence test or the bona fide residence test. The Foreign Tax Credit is claimed on Form 1116 and requires only that you paid or accrued a qualifying foreign income tax.
| FEIE | FTC | |
|---|---|---|
| How it works | Excludes foreign earned income from U.S. taxable income | Credits foreign income tax against U.S. tax |
| 2026 limit | Up to $132,900 of foreign earned income per qualifying person | The U.S. tax on your foreign income |
| Income covered | Earned income only: wages, salary, and self-employment income | Earned and passive income, such as dividends, interest, and rent |
| Who qualifies | Foreign tax home plus the physical presence or bona fide residence test | Anyone who paid or accrued qualifying foreign income tax |
| Form | Form 2555 | Form 1116 |
| Unused benefit | None carries over | Unused credit carries back 1 year and forward up to 10 years |
| Refundable child tax credit | Not available in a year you file Form 2555 | Not blocked; up to $1,700 per child can be refundable |
| IRA contributions | Excluded income does not count as compensation | Foreign wages still count as compensation |
You cannot use both on the same dollar of income.
How Do the FEIE and FTC Compare on the Same Income?
At the same salary, the FEIE usually yields a better result in a country with little or no income tax, and the FTC can match it in a country with higher income tax while keeping other benefits available. These examples use 2026 tax rates and the 2026 standard deduction of $16,100 for single filers and $32,200 for married couples filing jointly. They cover only U.S. federal income tax.
1. In a Country With No Income Tax, the Exclusion Removes the U.S. Tax
Emma is single and earns a $100,000 salary in a country with no personal income tax, such as the United Arab Emirates. She meets the physical presence test.
- With the FEIE: Emma excludes the full $100,000, so no U.S. income tax is due.
- With the FTC: Emma has no foreign tax to credit. Her taxable income is $83,900 after the standard deduction, and her U.S. income tax is $13,170.
2. In a Higher-Tax Country, Both Can Remove the U.S. Income Tax
Now Emma earns the same $100,000 in a country with higher income tax rates and pays $28,000 of foreign income tax.
- With the FEIE: No U.S. income tax is due. The foreign tax on her excluded wages cannot be credited, so nothing carries over, and her excluded wages do not count as compensation for an IRA contribution.
- With the FTC: Her $13,170 of U.S. income tax is fully offset by the credit. The remaining $14,830 of foreign tax becomes a carryover. She can use it in a year when her foreign tax is lower than her U.S. tax on that income, such as after moving to a lower-tax country, before it expires 10 years later. Her wages still count as compensation for an IRA contribution.
3. Above $132,900, the Excess Is Taxed at Your Higher Rates
Emma earns $180,000 in a country with no income tax. The FEIE excludes $132,900, but the remaining income is taxed as if the excluded income were still on the return. This is the stacking rule, and it means the income above the limit starts in a higher bracket.
- With the FEIE: Her U.S. income tax is $7,440: the tax on $163,900 ($31,934) minus the tax on the excluded $132,900 ($24,494). Her $31,000 of taxable income (the $47,100 above the limit minus the $16,100 standard deduction) is taxed at 24%.
- With the FTC alone: With no foreign tax to credit, her U.S. income tax is $31,934.
Our FAQ on the FEIE stacking rule explains the calculation, and our article on when the FEIE costs you more shows other cases where the exclusion leaves you worse off than the credit.
4. In a Higher-Tax Country, Children Can Tip the Choice Toward the Credit
If you file Form 2555 to claim the FEIE, you cannot claim the refundable additional child tax credit for that year. For 2026, the child tax credit is up to $2,200 per qualifying child, and up to $1,700 per child can be refundable when the credit is more than your U.S. tax.
Take a married couple filing jointly with one $100,000 salary, two children with Social Security numbers, and $28,000 of foreign income tax in a higher-tax country:
- With the FEIE: No U.S. income tax is due, so the nonrefundable child tax credit has nothing to reduce, and filing Form 2555 rules out the refundable part. The family receives no child tax credit.
- With the FTC: The foreign tax credit offsets their $7,640 in U.S. income tax, leaving a $20,360 carryover. With no U.S. tax left, $3,400 of the child tax credit is refundable ($1,700 for each child).
The foreign tax credit is applied before the child tax credit on the return, which is why the child credit becomes refundable here. In this case, the FTC leaves the family $3,400 better off. In a country with no income tax, the result reverses: without the FEIE, the same family would owe $3,240 (their $7,640 of U.S. tax minus $4,400 of child tax credit), and with the FEIE, no U.S. income tax is due. At lower incomes, where the child tax credit is larger than the U.S. tax, skipping the FEIE can still come out ahead. Our guide to the Child Tax Credit for expats and our article on Schedule 8812 cover the eligibility rules.
The four cases side by side:
| Situation (2026) | U.S. income tax with the FEIE | U.S. income tax with the FTC | What else changes |
|---|---|---|---|
| Single, $100,000, no foreign income tax | None | $13,170 | FEIE removes the U.S. income tax |
| Single, $100,000, $28,000 foreign tax | None | None (fully offset) | FTC keeps IRA eligibility and builds a $14,830 carryover |
| Single, $180,000, no foreign income tax | $7,440 | $31,934 | Stacking taxes the excess at 24% |
| Married, two children, $100,000, $28,000 foreign tax | None; no child tax credit | None; $3,400 refundable child tax credit | FTC also builds a $20,360 carryover |
Which Is Better for You, the FEIE or the FTC?
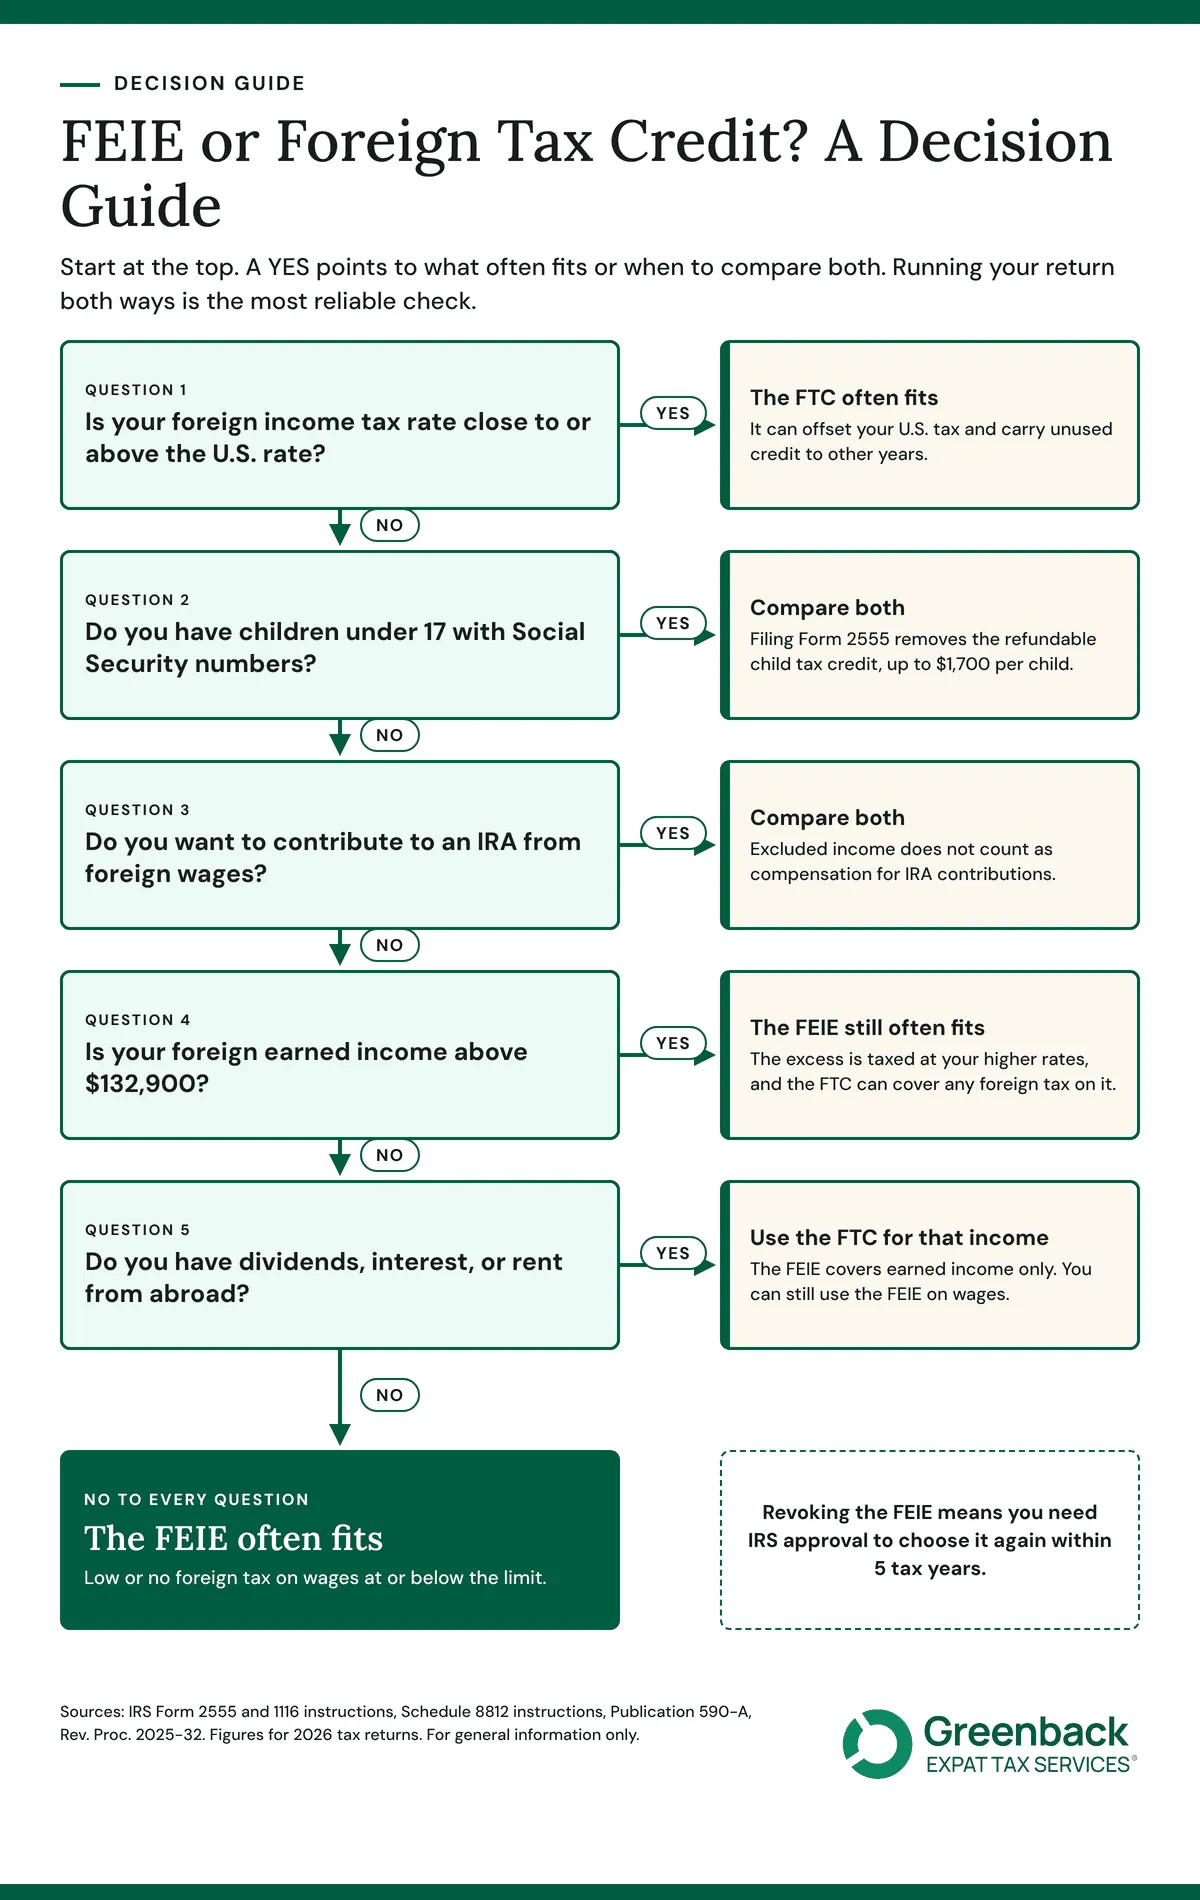
The better choice depends on your foreign tax rate, your income level, your family, and your retirement savings plans, so it is worth calculating your return both ways before you file. The decision guide follows the questions that most often change the answer.
The FEIE Often Fits Low-Tax Countries and Wage Income Under the Limit
The FEIE often gives the lower U.S. tax when you pay little or no foreign income tax, your foreign earned income is at or below $132,900, and, if you have children, your U.S. tax would be more than the child tax credit anyway. You may be able to add the foreign housing exclusion for qualifying housing costs.
The FTC Often Fits Higher-Tax Countries, Especially for Families and IRA Savers
The FTC often gives the better overall result when your foreign income tax rate is close to or above the U.S. rate. It keeps the refundable child tax credit available, keeps your wages counting as IRA compensation, and builds a foreign tax credit carryover that can offset U.S. tax in a later year, for example after a move to a lower-tax country while you stay on the FTC. Our FAQ on contributing to an IRA with the FEIE covers the details, based on IRS Publication 590-A.
Investment Income Uses the Credit in Either Case
The FEIE covers only earned income, so foreign tax on dividends, interest, rent, and capital gains can be credited only through the FTC.
Neither Option Reduces Self-Employment Tax
If you are self-employed, the 15.3% self-employment tax for Social Security and Medicare applies whether you claim the FEIE or the FTC. A totalization agreement can remove it if you pay into your host country’s system, and our guide to self-employment tax for expats explains when it applies.
Can You Use the FEIE and FTC Together?
Yes, you can use the FEIE and the FTC on the same return, as long as each one applies to different income. The IRS does not allow a credit or deduction for foreign tax on income you exclude. A common combination is the FEIE for wages up to $132,900 and the FTC for foreign tax on wages above the limit or on investment income. Our FAQ on claiming both the Foreign Tax Credit and the FEIE explains how the two are reported on a single return.
Can You Switch Between the FEIE and FTC?
You can revoke the FEIE for any tax year, but you then need IRS approval to choose it again within 5 tax years. As the IRS explains, you revoke it by attaching a statement to your return for the first year you no longer want the exclusion. Approval comes through a private letter ruling, which carries a user fee.
This matters most when your situation is likely to change. If you move from a no-tax country to a higher-tax country, switch to the FTC, and then move back within 5 years, the FEIE may not be available to you right away. Before you revoke, it helps to compare your expected tax under both options for the next several years.
The FTC has no similar waiting period. Each year, you choose whether to claim foreign income tax as a credit or as an itemized deduction.
Frequently Asked Questions about FEIE vs. FTC
Neither the FEIE nor the FTC is better for everyone. The FEIE often gives the lower U.S. tax when you pay little or no foreign income tax and earn $132,900 or less in foreign wages for 2026. The FTC often gives the better result when your foreign tax rate is close to or above the U.S. rate, especially when you have children who qualify for the refundable child tax credit or want to contribute to an IRA.
Yes, you can claim both the FEIE and the foreign tax credit on a single return, but not for the same income. You cannot claim a credit for foreign tax on wages you exclude with the FEIE. You can use the FEIE for wages up to the limit and the foreign tax credit for foreign tax on wages above the limit or on investment income.
Yes. If you file Form 2555 to claim the FEIE, you cannot claim the refundable additional child tax credit for that year. The nonrefundable child tax credit can still reduce any remaining U.S. tax. For 2026, up to $1,700 of the child tax credit per qualifying child can be refundable, so families with children often compare both options before choosing.
Contributing to an IRA requires taxable compensation. Foreign earned income you exclude with the FEIE does not count as compensation, so if all of your earned income is excluded, you generally cannot contribute to a traditional or Roth IRA for that year. Using the foreign tax credit instead keeps your foreign wages counting as compensation.
No. Neither the FEIE nor the FTC reduces U.S. self-employment tax, which is 15.3% for Social Security and Medicare. A totalization agreement between the United States and your host country may exempt you from U.S. self-employment tax if you pay into that country’s system.
Your Foreign Tax Rate and Family Decide Between the Exclusion and the Credit
The FEIE and the FTC both prevent double taxation, but they yield different results when children, IRA contributions, carryovers, or income above $132,900 come into play. Because revoking the FEIE means you need IRS approval to claim it again within 5 tax years, and FTC carryovers last 10 years, the better choice looks ahead as well as this year.
Greenback’s U.S. expat tax accountants have deep expertise in comparing the FEIE and FTC as part of our federal tax return preparation, and an expat tax consultation can help you plan before a move or a change in income. If you’re one of the U.S. citizens living abroad weighing these two options, we can help you choose with confidence. If you’re a corporate expat, one of the self-employed expats, or a digital nomad, learn more about how we help people in your situation.

Choose Your Expat Tax Strategy With Confidence
This article is for general information and does not cover every situation. Tax rules change, and the right approach depends on your income, residency, and family. Speak with a qualified tax professional with expertise in U.S. expat taxes before making decisions about your return.
Featured In


