IRS Streamlined Filing Compliance Procedures: Who Qualifies and How to File

- What Are the Streamlined Filing Compliance Procedures?
- Who Qualifies for the Streamlined Procedures?
- What Counts as Non-Willful Conduct?
- What If You Don't Qualify for the Streamlined Procedures?
- What Does Streamlined Filing Cost?
- How Do You File Under the Streamlined Procedures?
- What Happens After You Submit?
- Frequently Asked Questions about the Streamlined Procedures
- Your Residency and Your Reasons Decide Which Path Fits
The IRS Streamlined Filing Compliance Procedures are an IRS program that lets U.S. taxpayers who non-willfully failed to report income from foreign accounts or assets catch up by filing 3 years of tax returns and 6 years of FBARs (Reports of Foreign Bank and Financial Accounts). The Streamlined Foreign Offshore Procedures (SFOP) are for people who meet a non-residency test, usually Americans living abroad. Eligible filers pay the tax and interest they owe, and the IRS waives the main penalties for the missed filings, including FBAR penalties. The Streamlined Domestic Offshore Procedures (SDOP) are for people who don’t meet that test and add one 5% miscellaneous offshore penalty.
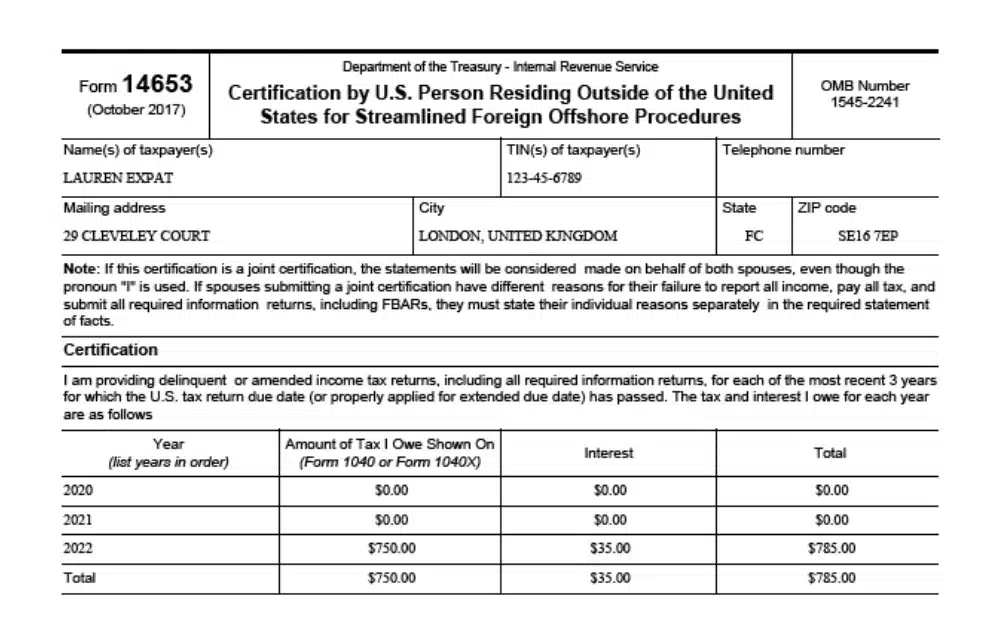
Both versions require a signed certification that your failure to report was non-willful: Form 14653 for SFOP and Form 14654 for SDOP. Streamlined is built for honest mistakes. If your conduct was willful, the IRS Voluntary Disclosure Practice, covered in our guide to the Voluntary Disclosure Program, is the route designed for that situation.
What Are the Streamlined Filing Compliance Procedures?
The Streamlined Filing Compliance Procedures, often called the Streamlined program, are an IRS process for catching up when you non-willfully failed to report foreign financial assets and pay tax on their income. You file the missing or corrected returns and FBARs, certify your conduct, and pay the tax and interest. In return, the IRS doesn’t charge most of the penalties those missed filings could carry. Which version you use depends on where you lived: SFOP is for taxpayers who meet a non-residency test, and SDOP is for those who don’t.
Streamlined Is Often Called an IRS Amnesty Program
Streamlined is often referred to as the IRS streamlined amnesty program or an offshore amnesty program, though its official name is the Streamlined Filing Compliance Procedures. You still pay any tax and interest you owe, and the relief covers specific penalties for eligible filers. Streamlined is one of several IRS amnesty programs, each built for a different situation. It’s also separate from the IRS Fresh Start Program, which helps people pay tax debt they already owe. Our Late Filing & IRS Amnesty FAQs answer the most common questions about Streamlined.
Streamlined Covers Only Your Federal Filings
A Streamlined submission covers your federal income tax returns, the international information returns that go with them, and your FBARs. State tax returns are separate, and whether you owe them depends on your ties to each state. Our FAQ on state returns under the Streamlined Procedures covers that question.
Who Qualifies for the Streamlined Procedures?
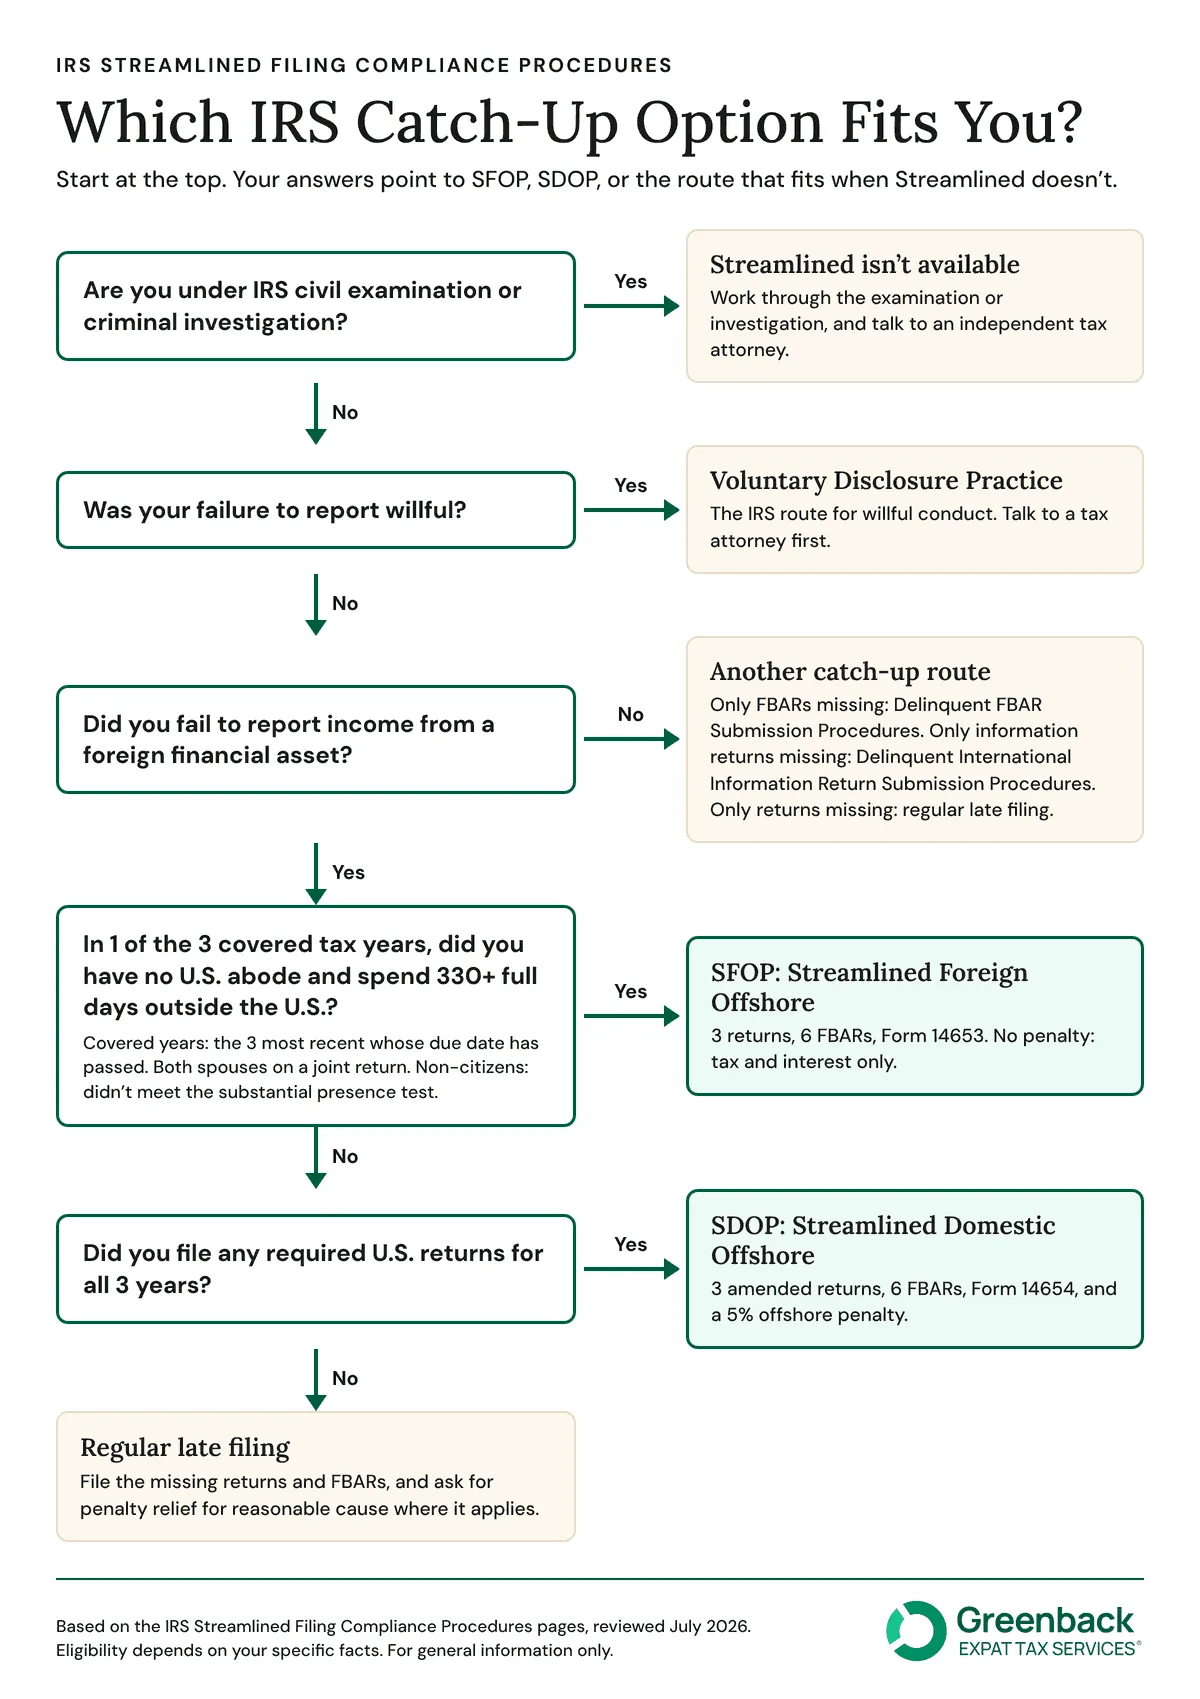
You qualify for the Streamlined Procedures if you’re an individual or an estate with a valid taxpayer identification number, you non-willfully failed to report income from a foreign financial asset, and you aren’t under IRS examination or criminal investigation. Your residency then decides whether you use SFOP or SDOP.
Every Streamlined Filer Must Meet These Rules
- Who can file: individuals, including married couples filing jointly, and estates of individuals. Businesses catch up separately, as our guide to filing late business tax returns explains.
- A valid taxpayer identification number: U.S. citizens and green card holders need a Social Security number (SSN). Someone who isn’t eligible for an SSN can use an ITIN or include an ITIN application with the package.
- Non-willful conduct: the failure came from negligence, inadvertence, mistake, or a good-faith misunderstanding of the rules.
- No open examination or investigation: a civil examination of any tax year, even one unrelated to foreign assets, or a criminal investigation rules you out. If you’ve received an IRS letter, confirm whether it opened an examination before you rely on Streamlined.
Streamlined Is for Unreported Income From Foreign Assets
The IRS describes Streamlined filers as taxpayers who failed to report income from a foreign financial asset and pay the tax on it, and who may also have missed FBARs or information returns. Unreported interest on a foreign bank account is the common case, and even a small amount of unreported foreign-asset income can keep you on the Streamlined path. Our FAQ on Streamlined and unreported cryptocurrency covers digital assets. If all of your income was reported and only paperwork is missing, a different approach makes sense.
SFOP and SDOP Have Different Residency Rules
For SFOP, U.S. citizens and green card holders must have had no U.S. abode and been physically outside the United States for at least 330 full days in any one of the three most recent tax years, whose due dates, including any properly requested extensions, have passed. Other non-citizens qualify for SFOP if they didn’t meet the substantial presence test in any one of those years.
| SFOP (non-residency test met) | SDOP (test not met) | |
|---|---|---|
| Residency test | Citizens and green card holders: no U.S. abode and 330 full days outside the U.S. in 1 of the 3 years. Others: didn’t meet the substantial presence test in 1 of the 3 years | Doesn’t meet the SFOP test |
| Returns already filed? | Not required | Required for each of the 3 years, if you had to file |
| Offshore penalty | None | 5% of the highest year-end total of covered foreign assets |
The 330-day count applies within a single tax year and includes the no-U.S.-abode condition, so it differs from the 12-month physical presence test used for the Foreign Earned Income Exclusion. Our FAQ on Streamlined Foreign vs. Domestic Offshore Procedures walks through borderline cases.
Joint Filers Must Both Meet the Non-Residency Test
On a joint return, both spouses must meet the SFOP non-residency requirement. If one spouse doesn’t, a joint return can’t use SFOP, and SDOP applies only if all required returns for all three years have already been filed.
What Counts as Non-Willful Conduct?
The IRS defines non-willful conduct as conduct due to negligence, inadvertence, mistake, or a good-faith misunderstanding of the law. Not knowing that U.S. citizens abroad file U.S. returns, or that a foreign pension or savings account belonged on an FBAR, can be consistent with non-willful conduct, depending on your other facts. Hiding accounts on purpose or ignoring advice to report them points the other way, and our article on what counts as a willful FBAR violation covers how courts draw that line. If you only recently learned you’re a U.S. citizen, our FAQ on discovering U.S. citizenship and never filing walks through the first steps.
Your Certification Needs Your Own Facts
Form 14653 and Form 14654 ask for a narrative explaining why you didn’t report. The IRS expects specific facts about your situation: why you didn’t know, where the foreign funds came from, how you used the accounts, and whether you relied on an advisor. On a joint return, the narrative covers each spouse’s conduct. Our guide to Form 14653 covers what goes in the narrative.
Unclear Facts Call for Advice Before You Certify
If you aren’t sure your conduct was non-willful, get advice before signing, because the certification is made under penalties of perjury. Our FAQ on whether you need a tax attorney for Streamlined explains when an attorney makes sense.
What If You Don’t Qualify for the Streamlined Procedures?
If you don’t qualify for Streamlined, the right route depends on what’s missing and why, and each situation has its own IRS procedure or filing path.
| Your situation | Route | Where to read more |
|---|---|---|
| You reported and paid tax on all your income but missed FBARs | Delinquent FBAR Submission Procedures | Delinquent FBAR Submission Procedures |
| You reported all your income but missed information returns such as Form 5471 or Form 3520 | Delinquent International Information Return Submission Procedures | Our FAQ on delinquent international information return procedures |
| You have unfiled returns but no unreported foreign-asset income, or you don’t meet the SFOP non-residency test and didn’t file | Regular late filing, with penalty relief for reasonable cause or first-time abatement where it applies | Filing taxes late, never filed taxes, and our FAQ on writing a reasonable cause letter |
| Your conduct may have been willful | IRS Voluntary Disclosure Practice, with an independent tax attorney | Voluntary Disclosure Program |
| You’re under IRS examination or criminal investigation | Work through that process with a tax attorney | Our FAQ on whether you need a tax attorney |
| You already renounced U.S. citizenship | Relief Procedures for Certain Former Citizens, if you’re eligible | Renouncing U.S. citizenship and our FAQ on renouncing without filing back taxes |
The Delinquent FBAR Submission Procedures apply when you aren’t under examination, and the IRS hasn’t contacted you about the missing FBARs. You file the late FBARs through BSA E-Filing with a statement explaining why they’re late. Under the FBAR penalty rules, no penalty applies to a non-willful violation due to reasonable cause if the account balance was properly reported. Our guide to FBAR penalties explains the rules. Our FAQ on the penalty for accidentally missing an FBAR covers the non-willful case.
Quiet Disclosure Leaves Penalties Open
A quiet disclosure means filing amended returns or late FBARs without using a formal procedure. It doesn’t come with the penalty relief Streamlined gives an eligible filer, and penalties can still be assessed on the late filings. Our FAQ on the penalty for not filing taxes as a U.S. citizen abroad lists them.
The OVDP Has Closed, but Streamlined Remains Open
The IRS closed the Offshore Voluntary Disclosure Program (OVDP) on September 28, 2018. Streamlined, first offered on September 1, 2012, and expanded in 2014, remains open. If you already went through the OVDP, our FAQ on using Streamlined after the OVDP explains where you stand.
What Does Streamlined Filing Cost?
The IRS charges no fee to use the Streamlined Procedures. What you pay is any tax and interest owed on the three tax years, the 5% penalty if you use SDOP, and the cost of preparing the package if you hire help.
SFOP Has No Offshore Penalty, and SDOP Has One
Under SFOP, you pay only tax and interest. Under SDOP, the 5% miscellaneous offshore penalty is based on the highest year-end total of your foreign financial assets that should have been reported, measured across the three tax years and six FBAR years. An asset counts if it was missing from an FBAR or Form 8938, or if its income went unreported. Our FAQ on the Streamlined Domestic Offshore 5% penalty shows how the base is calculated.
How Tax Is Calculated on Streamlined Returns
Most tax benefits available on a timely return also apply to Streamlined returns, and the Foreign Earned Income Exclusion has its own late-election rule.
| Item | How it works on Streamlined returns |
|---|---|
| Foreign Earned Income Exclusion (Form 2555) | A late return can still claim it if you owe no tax after the exclusion, or if you file before the IRS discovers you didn’t claim it. Each year uses its own limit |
| Foreign Tax Credit (Form 1116) | Foreign income tax you paid can offset U.S. tax on the same income |
| Self-employment tax | The Foreign Earned Income Exclusion doesn’t reduce it; a totalization agreement can assign your coverage to another country |
| Interest | Runs from each return’s original due date until the tax is paid, at the IRS quarterly interest rates, so a year with no tax due carries none |
| Foreign retirement plans | Where a tax treaty allows deferral, you can request retroactive relief for a missed deferral election with your Streamlined submission |
Our guide to back taxes explains how interest adds up when tax is owed.
Professional Preparation Is a Separate Cost
The work covers three returns, six e-filed FBARs, information returns, and a narrative certification, so many filers use a preparer. Greenback’s Streamlined filing services are a $1,750 flat fee.
How Do You File Under the Streamlined Procedures?
To file under the Streamlined Procedures, you prepare 3 years of returns, e-file 6 years of FBARs, sign Form 14653 or 14654, and mail the package with full payment to the IRS in Austin, Texas. The tax returns go on paper only.
| Item | SFOP | SDOP | How it’s sent, and what’s easy to miss |
|---|---|---|---|
| Tax returns | Form 1040 for unfiled years, Form 1040-X for filed years | Form 1040-X for all 3 years | Paper only. E-filed returns aren’t accepted, as our FAQ on e-filing a late expat return explains |
| Information returns | Forms 8938, 3520, 5471, 8621 and others, as required | Same | Attached to each return |
| Red marking | “Streamlined Foreign Offshore” | “Streamlined Domestic Offshore” | In red at the top of the first page of each return and information return |
| FBARs | 6 years | 6 years | E-filed through BSA E-Filing. Reason for late filing: “Other,” then “Streamlined Filing Compliance Procedures” |
| Certification | Form 14653 | Form 14654 | Signed original in the package, a copy on each return, none on the FBARs |
| Payment | Tax and interest | Tax, interest, and the 5% penalty | The full amount, sent with the package |
If the IRS finds a problem with a submission, our FAQ on what happens if the IRS rejects a Streamlined submission covers the next steps. A streamlined filing service can assemble the package for you.
1. Confirm Your Tax Years and FBAR Years
Your tax years are the three most recent years for which the return due date, including any properly requested extension, has passed. Your FBAR years are the six most recent years for which the FBAR due date has passed. A package mailed before April 15, 2027, covers tax years 2023, 2024, and 2025, as well as FBARs for 2020 through 2025. Once your 2026 return’s due date passes, including a properly requested extension, 2026 replaces 2023, and the FBAR window moves forward when the 2026 FBAR due date passes. Our FAQ on ten years of missed returns covers years before the window.
2. Prepare Your Returns
Prepare an original return for any year you didn’t file and an amended return for any year you did, with the information returns each year requires. Claim the Foreign Earned Income Exclusion (FEIE) or Foreign Tax Credit (FTC) where they apply, following the late-election rule for the FEIE. Our FAQs on amending returns under Streamlined and Form 3520-A in a Streamlined package cover two common details.
3. File Six Years of FBARs Under Streamlined
The Streamlined procedures for FBARs are the same under SFOP and SDOP: file any delinquent FBARs for the six FBAR years electronically on FinCEN Form 114, using the late-filing reason shown in the table. If you only need FBARs, Greenback’s FBAR filing service handles those on their own. FBARs never go in the paper package.
4. Sign Form 14653 or 14654
Write the narrative with the specific facts of your situation, then sign it.
5. Pay and Mail the Package
Pay the full amount due, then mail everything to: Internal Revenue Service, 3651 South I-H 35, Stop 6063 AUSC, Attn: Streamlined Foreign Offshore (or Attn: Streamlined Domestic Offshore), Austin, TX 78741.
What Happens After You Submit?
After you submit, the IRS processes your Streamlined returns like any other return: it doesn’t acknowledge receipt, and there’s no closing agreement. The IRS doesn’t publish a processing time for Streamlined submissions, and our FAQ on Streamlined processing time outlines what filers typically see. Your FBARs generate a BSA E-Filing confirmation when you file them.
Returns Can Be Selected for Examination
Streamlined returns aren’t audited automatically, but they can be selected through the normal process and checked against information from banks and other sources. Our FAQ on Streamlined audit risk covers what draws a closer look.
Streamlined Penalty Relief Has Limits
The relief covers failure-to-file, failure-to-pay, accuracy-related, information return, and FBAR penalties for eligible filers. It doesn’t apply if an examination finds fraud or a willful FBAR violation, as the IRS explains. Penalties the IRS assessed before your submission aren’t reversed.
Frequently Asked Questions about the Streamlined Procedures
Yes, if you’re a U.S. citizen or green card holder. The Streamlined Procedures require a valid taxpayer identification number, and for anyone eligible for a Social Security number, that means an SSN. A person who isn’t eligible for an SSN can use an ITIN or submit an ITIN application with the Streamlined package.
Yes, taxpayers who made a quiet disclosure can still use the Streamlined Filing Compliance Procedures if they meet the eligibility rules. Any penalties the IRS already assessed on those earlier filings aren’t reversed.
No, not on a joint return. For a joint return under the Streamlined Foreign Offshore Procedures, both spouses must meet the non-residency requirement. If one spouse doesn’t, the couple filing jointly can use the Streamlined Domestic Offshore Procedures only if all required returns for all three years have already been filed.
Yes, the Streamlined Filing Compliance Procedures are open to individuals and their estates. The general rules still apply, including a valid taxpayer identification number, non-willful conduct, and no open IRS examination or criminal investigation.
Former U.S. citizens who missed filings may qualify for the IRS Relief Procedures for Certain Former Citizens. They’re open to people who renounced after March 18, 2010, have a net worth under $2 million at renunciation and when they apply, owed $25,000 or less in total tax for the year of renunciation and the five years before it, and whose failures were non-willful. The IRS hasn’t announced an end date for the Relief Procedures for Certain Former Citizens.
Your Residency and Your Reasons Decide Which Path Fits
If you meet the non-residency test and your failure to report income from foreign assets was non-willful, SFOP means three returns, six FBARs, one certification, and relief from the penalties those filings could carry. U.S. residents with returns already on file use SDOP and its 5% penalty, and willful cases belong in voluntary disclosure. Either way, the package is filed the same way.
If you’re a late filer, Greenback can prepare your Streamlined package and file your FBARs. Our FAQ on how Greenback helps with back taxes explains the options. If you’re a dual citizen or an accidental American who just learned about U.S. filing, learn more about our Streamlined filing services.

Start Your Streamlined Filing Today
This article is for general information only. Streamlined eligibility depends on your specific facts, so speak with a tax professional with expertise in U.S. expat taxes before you submit.
Featured In


