Form 1040 vs. Form 1040-NR: Which Tax Return Should You File?

- What Is the Difference Between Form 1040 and Form 1040-NR?
- How Do I Know Whether to File Form 1040 or Form 1040-NR?
- Who Pays More Tax, a Resident or a Nonresident?
- Can a Nonresident Married to a U.S. Citizen File Form 1040 Instead?
- What If I Changed Residency Status During the Year?
- What Happens If I Filed the Wrong Form?
- When Are Form 1040 and Form 1040-NR Due?
- What Does "IRS Form 1040 or 1040-NR" Mean on the FAFSA?
- What Changes for 2027? (Filed in 2028)
- Frequently Asked Questions about Form 1040 vs Form 1040-NR
- Your Tax Residency Decides Which Return You File

Form 1040 is the U.S. tax return for citizens and resident aliens, and Form 1040-NR is the return for nonresident aliens. Form 1040 reports worldwide income. Form 1040-NR reports only U.S.-source income. Tax residency decides which form you file, and a visa alone doesn’t. You are a resident alien if you hold a green card or pass the substantial presence test. Our guides to Form 1040 and Form 1040-NR cover each line of the return, line by line.
A U.S. citizen living abroad always files Form 1040. A green card holder abroad also files Form 1040 until the green card is formally given up or a tax treaty tie-breaker applies. A year in which your residency starts or ends is a dual-status year, and that return combines both forms. Form 1040-NR allows no joint filing, offers no standard deduction for most filers, and taxes passive U.S. income at a flat 30% or a lower treaty rate. Because of those differences, the same salary can result in different tax bills on each form for the 2026 tax year, when filed in 2027.
What Is the Difference Between Form 1040 and Form 1040-NR?
Form 1040 taxes a resident’s worldwide income and allows the full range of filing statuses, deductions, and credits. Form 1040-NR covers only a nonresident’s U.S.-source income and taxes passive U.S. income such as dividends at a flat 30% (or lower treaty rate). The table compares the two returns for the 2026 tax year.
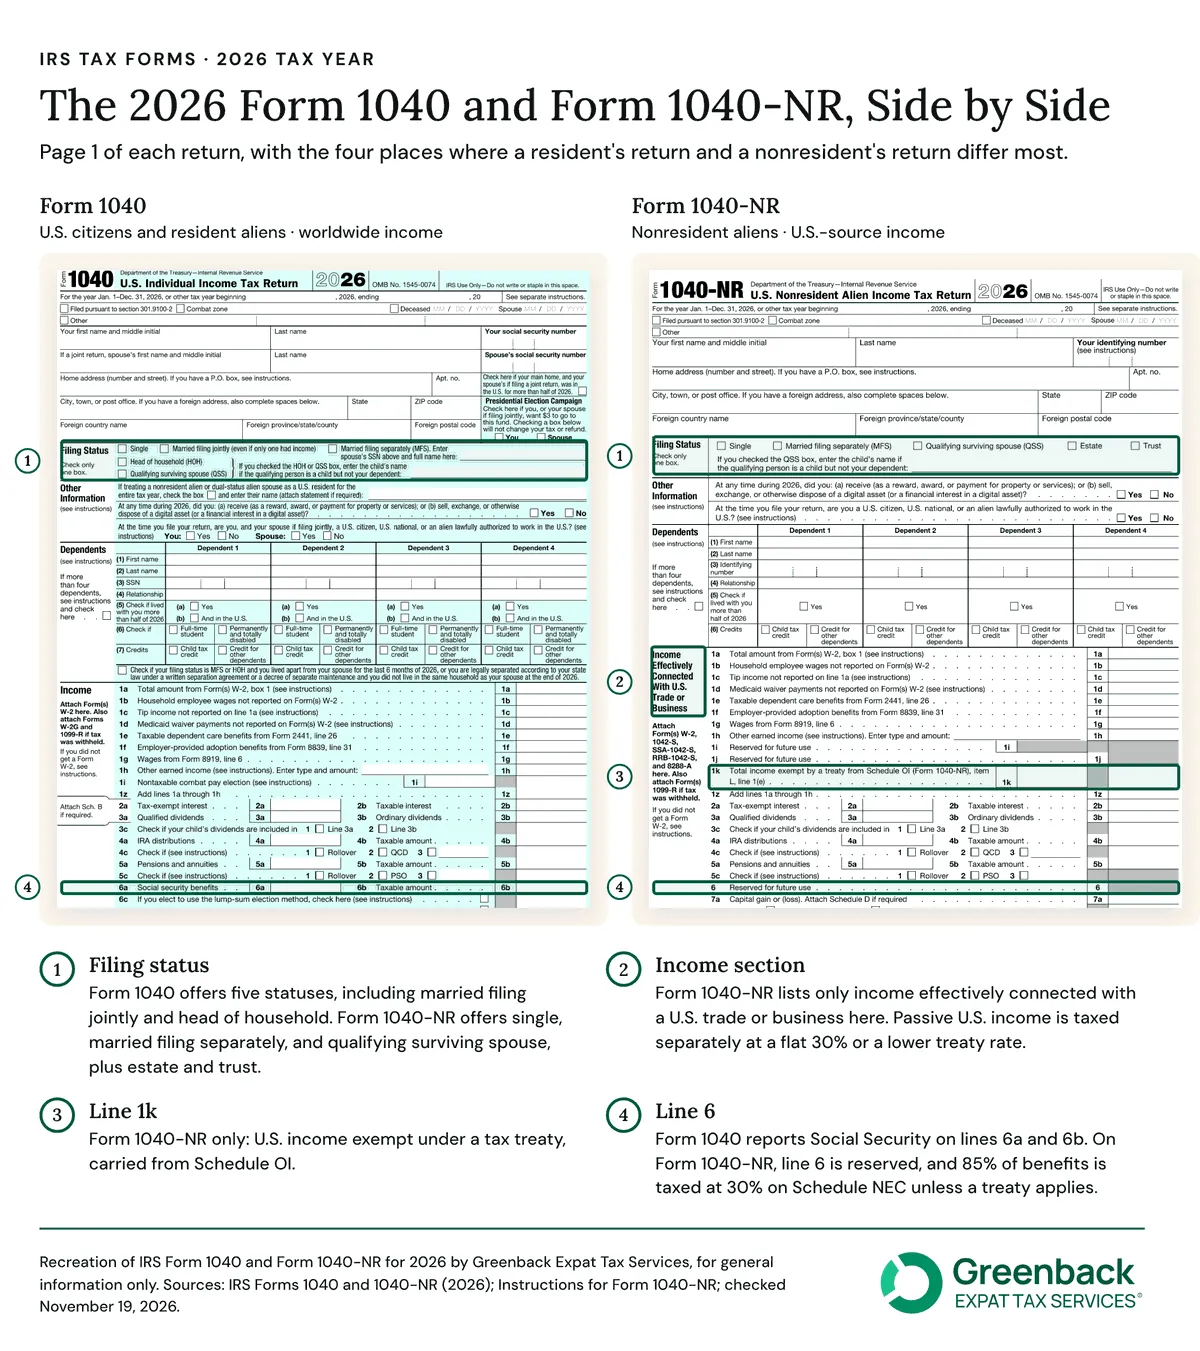
Form 1040 and Form 1040-NR compared:
| Feature | Form 1040 | Form 1040-NR |
|---|---|---|
| Who files | U.S. citizens and resident aliens (green card or substantial presence test) | Nonresident aliens with U.S. income to report, plus estates and trusts of nonresidents |
| Income reported | Worldwide income from every country | U.S.-source income only |
| How income is taxed | Graduated rates on taxable income | Graduated rates on income connected with a U.S. trade or business; a flat 30% (or lower treaty rate) on passive U.S. income, with no deductions |
| Filing statuses | Single, married filing jointly, married filing separately, head of household, qualifying surviving spouse | Single, married filing separately, qualifying surviving spouse (limited), estate, trust |
| Standard deduction (2026) | $16,100 single, $32,200 married filing jointly | None, except students and business apprentices from India under the U.S.–India treaty |
| Dependents | Qualifying children and relatives | Only filers who are U.S. nationals or residents of Canada or Mexico, on the same terms as Form 1040; limited for South Korea residents and India treaty students |
| Tax credits | Full range, including the child tax credit and education credits | Very limited |
| Foreign Earned Income Exclusion and Foreign Tax Credit | FEIE up to $132,900 for 2026; Foreign Tax Credit | Not available for foreign income, which isn’t reported |
| Social Security benefits | Up to 85% taxable at graduated rates | 85% taxed at a flat 30%, unless a treaty exempts or reduces it |
| Tax treaty claims | Limited by each treaty’s saving clause | Common; claimed on Schedule OI and often Form 8833 |
| E-file | Yes | Yes |
| Due date (2026 return) | April 15, 2027 (June 15 if you live abroad) | April 15, 2027 with U.S. wages subject to withholding; June 15, 2027 without |
| FBAR and Form 8938 | FBAR and Form 8938 when thresholds are met | Generally neither (a nonresident spouse who chooses resident treatment files a joint Form 1040 and may need Form 8938) |

Not Sure Which Return Is Yours?
How Do I Know Whether to File Form 1040 or Form 1040-NR?
You file Form 1040 if you are a U.S. citizen, held a green card all year, or passed the substantial presence test with residency for the full year. You file a dual-status return if your residency started or ended during the year, and Form 1040-NR if none of these applies. Our guide to resident and nonresident aliens covers each status in depth.
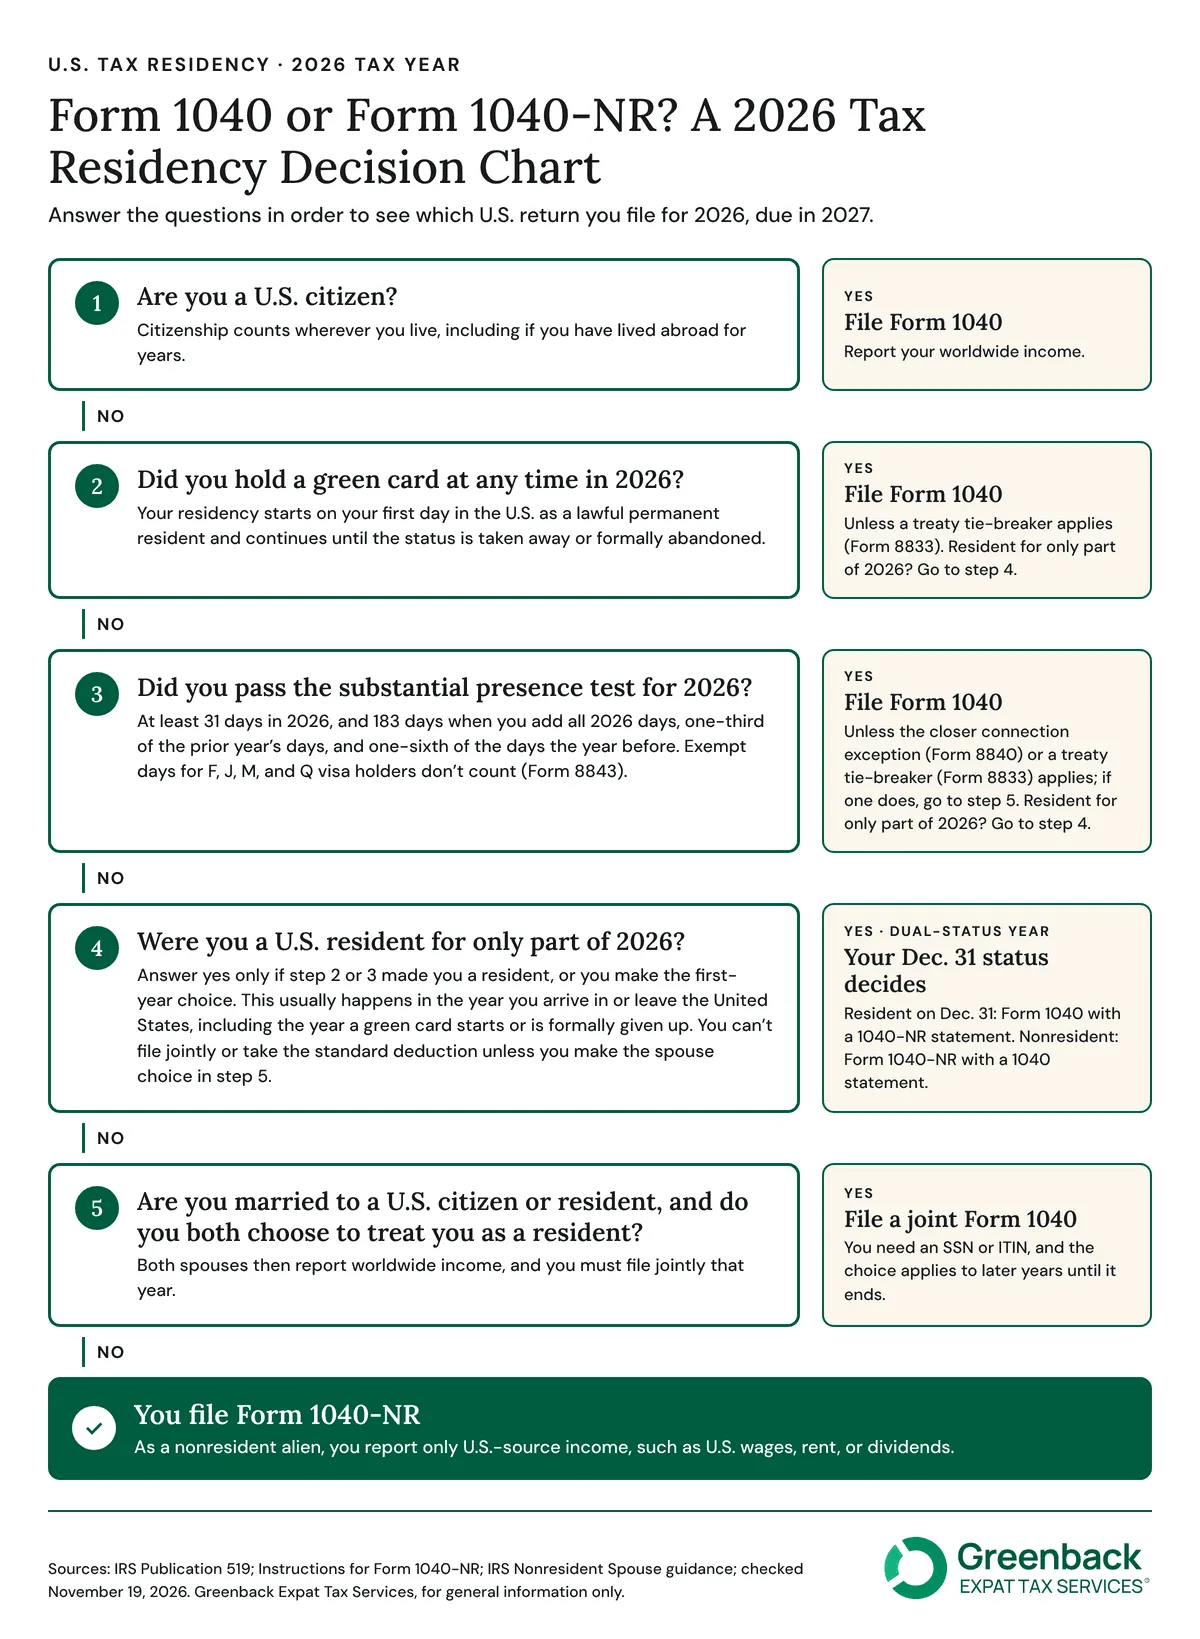
The green card test
Your residency starts on the first day you are in the U.S. as a lawful permanent resident. It continues until the status is taken away or formally abandoned, for example by filing Form I-407, even if you live abroad. A green card that expires on its face doesn’t end your residency. If a tax treaty treats you as a resident of another country under its tie-breaker rule, you can be taxed as a nonresident and file Form 1040-NR with Form 8833. Long-term green card holders should seek advice before claiming it, as it can trigger the expatriation tax rules.
The substantial presence test
You pass the substantial presence test if you were in the U.S. at least 31 days during the year and 183 days over three years, counting all days in the current year, one-third of the prior year’s days, and one-sixth of the days from the year before that. Someone present 120 days in each of the three years counts 120 + 40 + 20 = 180 days, which falls short, so they file Form 1040-NR. Our FAQ on how many U.S. days you can spend without becoming a resident walks through the limits, and our substantial presence test guide covers the day count.
Some days don’t count. Students on F, J, M, or Q visas are generally exempt for their first five calendar years, and teachers and trainees on J or Q visas are exempt unless they were exempt in any part of two of the prior six calendar years. You record those days on Form 8843. If you were present fewer than 183 days in the current year and have a tax home and closer connection to another country, you can stay a nonresident by filing Form 8840.
Which form you file in common situations:
| Your situation | Return for 2026 |
|---|---|
| U.S. citizen living in the U.S. or abroad | Form 1040 |
| Green card holder, in the U.S. or abroad | Form 1040 (dual-status in the year it starts or ends) |
| H-1B worker past 183 weighted days | Form 1040 (dual-status in the arrival year) |
| F-1 or J-1 student within the first five calendar years | Form 1040-NR (plus Form 8843) |
| J-1 teacher or researcher in an exempt year | Form 1040-NR (plus Form 8843) |
| Became or stopped being a U.S. resident during 2026 | Dual-status return |
| Nonresident married to a U.S. citizen, both choosing resident treatment | Joint Form 1040 |
Who Pays More Tax, a Resident or a Nonresident?
On the same U.S. salary, a nonresident usually pays more income tax because Form 1040-NR has no standard deduction. A resident can also pay more income tax when foreign income is added, because Form 1040 taxes worldwide income. These examples use only 2026 federal income tax rates.
The same $60,000 salary on each form
Two single coworkers each earn $60,000 in U.S. wages in 2026. One is a resident alien, and the other is an F-1 student on Optional Practical Training (OPT) who is still a nonresident. Neither has state income tax.
| Resident on Form 1040 | Nonresident on Form 1040-NR | |
|---|---|---|
| U.S. wages | $60,000 | $60,000 |
| Standard deduction | $16,100 | $0 |
| Taxable income | $43,900 | $60,000 |
| Federal income tax | $5,020 | $7,912 |
If the resident also earns $20,000 of foreign income, such as net rent from a home abroad, the Form 1040 tax rises to $8,770 before any Foreign Tax Credit. The nonresident wouldn’t report that income at all.
These figures cover income tax only. As a nonresident F-1 student on practical training, the OPT worker also generally has no Social Security or Medicare tax withheld, about $4,590 on $60,000, so the nonresident’s total federal tax is lower ($7,912 against $9,610).
Can a Nonresident Married to a U.S. Citizen File Form 1040 Instead?
Yes, if you and your spouse both choose to treat you as a U.S. resident for the whole year. You must file a joint Form 1040 for the first year, and both of you report worldwide income. In later years, you can file jointly or separately, and once the choice ends, neither spouse can make it again. The 2026 Form 1040 has a checkbox for this choice, and you attach a statement signed by both spouses. Your spouse needs a Social Security number or an ITIN. Our FAQ on the Section 6013(g) election covers how to make it.
Without the choice, or if your foreign spouse lacks an SSN or ITIN, the U.S. citizen files as married filing separately, or as head of household with a qualifying person other than the spouse. Our FAQ on a non-citizen spouse’s tax return explains each option.
One couple filed separately and jointly
A U.S. citizen earns $70,000, and their spouse, an F-1 student on OPT and still a nonresident, earns $40,000 in U.S. wages. They have no children and no state income tax.
| 2026 federal income tax | Separate returns | Joint Form 1040 |
|---|---|---|
| U.S. citizen (Form 1040, married filing separately) | $6,570 | |
| Spouse (Form 1040-NR, no standard deduction) | $4,552 | |
| Joint return ($32,200 standard deduction) | $8,840 | |
| Total | $11,122 | $8,840 |
The joint return saves $2,282 here. If the spouse also had $25,000 of foreign income, such as interest or rent from abroad, the joint return would rise to $12,040, $918 more than filing separately, before any Foreign Tax Credit for tax paid abroad.
What If I Changed Residency Status During the Year?
If you were a resident for part of the year and a nonresident for the rest, you are a dual-status taxpayer, and your status on December 31 decides the main return. A resident on December 31 files Form 1040 and attaches a Form 1040-NR, marked “Dual-Status Statement,” that reports the part of the year spent as a nonresident. A nonresident on December 31 does the reverse: Form 1040-NR is the main return, and the attached statement is a Form 1040 that reports the part of the year spent as a resident.
Dual-status filers can’t take the standard deduction, can’t use head of household, and can’t file jointly unless they make the spouse choice above. Dual-status returns have to be filed on paper, so check the current Form 1040-NR instructions before filing. Someone who arrives late in the year and passes the substantial presence test the following year may be able to make the first-year choice to be treated as a resident for part of the arrival year. Our guide to dual-status returns covers both forms in detail.
What Happens If I Filed the Wrong Form?
If you filed Form 1040 instead of Form 1040-NR, or the reverse, you fix it by amending on Form 1040-X and attaching the correct return. A resident who filed Form 1040-NR attaches a Form 1040 that adds worldwide income. A nonresident who filed Form 1040 attaches a Form 1040-NR, which usually removes the standard deduction and credits claimed on Form 1040. Our guide to amended tax returns explains the timing and steps.
When Are Form 1040 and Form 1040-NR Due?
For the 2026 tax year, Form 1040 is due April 15, 2027. Form 1040-NR is due April 15, 2027, if you had U.S. wages subject to withholding, and June 15, 2027, if you didn’t. U.S. citizens and resident aliens living abroad receive an automatic extension to June 15, but interest runs from April 15 on any tax not paid by then.
Due dates and extensions by return:
| Return | Original due date | Tax due | With Form 4868 |
|---|---|---|---|
| Form 1040 | April 15, 2027 | April 15, 2027 | October 15, 2027 |
| Form 1040, living abroad | June 15, 2027 | April 15, 2027 | October 15, 2027 |
| Form 1040-NR with U.S. wages subject to withholding | April 15, 2027 | April 15, 2027 | October 15, 2027 |
| Form 1040-NR without such wages | June 15, 2027 | June 15, 2027 | December 15, 2027 |
Form 4868 extends the time to file, not the time to pay. Our guide to IRS mailing addresses lists where paper returns go.
What Does “IRS Form 1040 or 1040-NR” Mean on the FAFSA?
On the FAFSA, “IRS Form 1040 or 1040-NR” means a U.S. federal income tax return. Federal Student Aid explains that most U.S. citizens and permanent residents use Form 1040, and U.S. taxpayers who aren’t citizens or permanent residents use Form 1040-NR. The FAFSA asks about the tax return from two years before the school year starts.
You answer “Yes” if you filed or will file either form. A U.S. citizen abroad who filed Form 1040 answers “Yes.” A student or parent who filed a tax return only with a foreign country answers “No.” Our guide to the FAFSA for U.S. expats covers how foreign income and taxes are reported, and our FAQ on reporting the Foreign Earned Income Exclusion on the FAFSA covers the excluded amount.
What Changes for 2027? (Filed in 2028)
No changes to the residency tests have been announced for the 2027 tax year, which will be filed in 2028. The standard deduction on Form 1040 rises to $16,600 for single filers and $33,200 for married couples filing jointly, and the Foreign Earned Income Exclusion rises to $137,300. Form 1040-NR still has no standard deduction for most filers. Our standard deduction and tax brackets guide lists every 2027 amount.
Frequently Asked Questions about Form 1040 vs Form 1040-NR
A nonresident alien generally can’t file Form 1040. The main exception is a nonresident married to a U.S. citizen or resident who, together with their spouse, chooses to be treated as a U.S. resident for the whole year and files a joint Form 1040. Someone who arrives late in the year may also qualify for the first-year choice.
U.S. citizens and green card holders living abroad file Form 1040 and report their worldwide income. Form 1040-NR is for nonresident aliens, such as foreign nationals who earn U.S. income without living in the United States long enough to become residents.
Nonresident aliens generally don’t file an FBAR because it applies to U.S. persons, such as citizens and resident aliens, as well as U.S. entities. A resident alien files an FBAR when the combined value of foreign financial accounts exceeds $10,000 at any time during the year.
Form 1040-NR-EZ was discontinued starting with the 2020 tax year. Nonresident aliens who used it now file the redesigned Form 1040-NR.
Form 1040 isn’t the same as a W-2. A W-2 is the wage statement an employer sends you, while Form 1040 and Form 1040-NR are the tax returns you file. The wages from your W-2 go on line 1a of either return.
Your Tax Residency Decides Which Return You File
Citizenship, a green card, or enough days in the U.S. puts you on Form 1040, and everyone else with U.S. income files Form 1040-NR. The year you arrive, leave, or marry a U.S. citizen is when the choice gets harder, and the two returns can produce very different results. Checking your status before you file helps you avoid having to amend later.
If you’re a visa or green card holder, our accountants can confirm your residency and handle your U.S. tax return preparation. If your status changed during the year, see how we help dual-status filers. If you’re a U.S. citizen abroad, see our support for Americans living abroad.

Residents, Nonresidents, and Everyone In Between
This article is for general information only and does not constitute tax or legal advice. Tax rules change, and every situation is different, so consult a qualified tax professional about your own return.
Featured In


