Resident Alien Taxes: Filing Rules, Foreign Income & Assets

- What Changes the Moment You Become a Resident Alien?
- Do I Report Income from Before I Moved to the U.S.?
- How Do I Avoid Paying Taxes Twice on the Same Income?
- What About My Foreign Bank Accounts and Assets?
- What Forms Will I Need to File?
- When Do I Need to File?
- Can I Contribute to Retirement Accounts?
- Common First-Year Mistakes to Avoid
- What Should I Do Right Now?
- Getting Professional Help with Your First-Year Filing
- Related Resources
If you are a resident alien for U.S. tax purposes, your obligations go well beyond the income you earn inside the country. Like U.S. citizens, resident aliens are taxed by the Internal Revenue Service (IRS) on their worldwide income. This includes foreign wages, investments, rental properties, and retirement distributions.
You may also need to report foreign financial accounts, file international disclosures, and pay federal or state taxes, even if you already paid tax in another country. However, resident aliens also qualify for the standard deduction, family tax credits, and treaty positions that can significantly lower U.S. tax liability.
Here is what resident aliens need to know about U.S. income taxes, reporting foreign assets, and preparing for the 2026 and 2027 tax filing seasons.
Key Takeaways
- Worldwide Income: Resident aliens generally must report global income to the IRS, including foreign wages, overseas bank interest, rental revenue, and investment gains.
- Form 1040 Filing: Resident aliens generally file Form 1040 when required and may qualify for the standard deduction and tax credits, subject to eligibility rules.
- Foreign Account Disclosures: Foreign financial accounts with an aggregate value exceeding $10,000 may trigger an annual FBAR (FinCEN Form 114). Other foreign assets may require Form 8938 or additional disclosures.
- Double-Tax Protection: The Foreign Tax Credit (Form 1116) and applicable tax treaty provisions may help reduce U.S. tax on income already taxed abroad.
- First-Year Rules: Becoming a U.S. tax resident partway through the year can affect which income is taxable, which deductions you can claim, and how you file your first return.
What Taxes Do Resident Aliens Pay?
Resident aliens typically follow the same federal income tax rules as U.S. citizens. This means the IRS taxes your worldwide income, regardless of where you earned it or where you keep the money.
Your U.S. tax responsibilities generally fall into three categories:
- Income Tax: Your Form 1040 must reflect taxable income from U.S. and foreign sources, even if you don’t transfer the money into the United States. Graduated federal income tax rates apply, with additional rules for certain types of income.
- Tax Return Filing: You generally file Form 1040 when required. Eligible resident aliens can claim the standard deduction and applicable credits, although special restrictions apply in dual-status tax years.
- International Reporting: Foreign bank accounts, pensions, business interests, and investment funds may trigger additional information returns, sometimes even when no additional U.S. tax is owed.
Depending on your circumstances, you may also owe self-employment tax, additional taxes on certain investment income, or state income taxes.

Your immigration status doesn’t necessarily determine when these responsibilities began. Some foreign nationals become U.S. tax residents through the substantial presence test years before receiving a green card.
If you’re unsure whether the IRS considers you a resident alien, use our Resident Alien vs. Nonresident Alien guide to verify your classification.
What Income Do Resident Aliens Have to Report?
Resident aliens declare their worldwide taxable income on Form 1040, regardless of where the income was earned, where it was deposited, or which currency was used.
| Income Type | General U.S. Tax Treatment |
| U.S. Employment & Contracting | Generally taxable and reported on Form 1040 |
| Foreign Employment & Freelancing | Generally taxable, even if paid into an overseas account |
| Self-Employment & Business Income | Generally reportable; may trigger self-employment tax |
| Foreign Bank Interest & Dividends | Generally taxable when recognized under applicable rules |
| Rental Income from Foreign Property | Generally reportable, with allowable expenses and depreciation |
| Capital Gains from U.S. & Foreign Assets | Generally reportable when gains are realized |
| Foreign Pensions & Retirement Plans | Tax treatment depends on the arrangement and applicable treaty provisions |
| Personal Account Transfers | Moving your own money between accounts generally isn’t taxable by itself |
For example, if you live in the U.S. but rent out a condo in London, you generally must report that rental income on your federal return, even if you already paid tax to the UK government on the same earnings.
Similarly, interest earned in an overseas savings account may be taxable each year, even if the money remains in that foreign bank.
However, reporting foreign income doesn’t necessarily mean you will pay additional U.S. tax on all of it. Tax credits, exclusions, and applicable treaty provisions may help reduce double taxation.
Do You Pay U.S. Tax on Money Transferred From Abroad?
Transferring money you already own between personal bank accounts generally isn’t taxable.
If you wire $50,000 of existing personal savings from a bank in Germany to your checking account in New York, the transfer itself doesn’t create $50,000 of taxable income.
However, transactions connected to the money can trigger tax consequences:
- Underlying income: Interest, dividends, or salary earned during your U.S. residency generally remain taxable, even if deposited in a foreign account.
- Capital gains: If you sold foreign real estate or investments to generate the funds, the sale may create reportable gains.
- Foreign currency gains: Exchange-rate changes between acquiring and disposing of foreign currency can create taxable gains under certain circumstances.
- Foreign account reporting: Holding money in a foreign account may trigger FBAR or Form 8938 reporting, regardless of whether you transfer the funds to the U.S.
The big difference is between moving money you already own and earning or recognizing taxable income.
What about the new 1% remittance tax?
The tax introduced under the One Big Beautiful Bill Act in January 2026 applies to certain cash-funded transfers sent from the U.S. to recipients abroad. It doesn’t apply to money transferred into the United States. Most qualifying electronic bank transfers are excluded. For more information, see our guide to international money transfers or read about the IRS’s proposed regulations for the 1% remittance tax.

Relocating to the U.S. This Year?
How Resident Aliens File U.S. Taxes
Resident aliens file Form 1040 (U.S. Individual Income Tax Return) by the annual April tax deadline.
Whether you must file depends on your gross income, filing status, age, and certain special circumstances. Even if your income is below the usual filing threshold, self-employment income or other filing requirements may still require you to file a return.
You may also need supporting schedules:
- Schedule B: For reporting domestic and foreign interest and dividends, and answering required questions about foreign accounts.
- Schedule D: For capital gains and losses on investments.
- Schedule E: For rental real estate income and royalties.
Income from foreign employers or financial institutions may not appear on a U.S. W-2 or Form 1099. You’re still responsible for reporting taxable amounts when required.
Standard Deduction and Tax Credits
Resident aliens treated as full-year U.S. residents can usually claim the standard deduction and applicable tax credits when they meet the eligibility requirements.
These may include the Child Tax Credit, certain education credits, and other provisions available to qualifying taxpayers.
For the 2026 tax year, filed in spring 2027, the standard deduction amounts are:
| Filing Status | 2026 Standard Deduction |
| Single | $16,100 |
| Married Filing Jointly | $32,200 |
| Head of Household | $24,150 |
| Married Filing Separately | $16,100 |
These are the basic standard deduction amounts. Additional amounts may apply to eligible taxpayers who are age 65 or blind.
Taxpayers filing as dual-status aliens generally cannot claim the standard deduction under the default IRS rules. Certain elections may change their filing treatment.
For detailed rules, see our Dual-Status Alien Tax Filing guide.
If you are living in the U.S. on a work visa or recently transitioned to permanent residency, your tax rules depend on your exact travel history, visa background, and foreign assets. Explore our specialized services to see how we help international professionals navigate residency transitions, foreign accounts, and treaty benefits. Learn How Greenback Helps Foreign Nationals.
Do Resident Aliens Pay State Income Taxes?
They may. State tax residency doesn’t always align with federal tax residency. Some states use domicile, physical presence, and other statutory tests to determine whether you’re a resident.
Depending on where you live and work, you may need to file a full-year, part-year, or nonresident state return. State treatment of foreign income and tax treaties may also differ from federal rules.
This is especially important if you’ve recently moved to the United States, work remotely, or earn income in multiple states.
How Resident Aliens Avoid Double Taxation
Because resident aliens report worldwide income, that income can be taxed in two countries at once. The U.S. tax code provides three ways to offset this:
1. Foreign Tax Credit (Form 1116)
Rather than deducting foreign earnings from your U.S. gross income, the Foreign Tax Credit provides a credit against your final U.S. tax bill for income taxes you paid to another government.
For resident aliens maintaining financial ties abroad, three rules are particularly important:
- Income categories: Foreign income is separated into categories, often called baskets. Passive income, such as certain dividends and interest, is generally calculated separately from income in other categories. Foreign taxes in one category ordinarily cannot offset U.S. tax attributable to another category without an applicable exception.
- Credit limits: Your credit can’t exceed the U.S. tax rate on that specific foreign income. If your home country taxed your rental profit at 15% and the U.S. tax rate on that profit is 22%, the credit covers the initial 15%, leaving you to pay the 7% difference to the IRS. Unused excess credits generally carry forward for up to 10 years.
- Unused credits: Some unused qualifying foreign tax credits may be carried to other tax years, subject to the applicable rules and limitations.
For example, if you own rental property overseas and pay income tax to that country, you may qualify for a Foreign Tax Credit that reduces the U.S. tax on that income.
However, the actual credit depends on the income’s source, applicable category, deductible expenses, foreign taxes, and U.S. tax limitation.
2. Bilateral Tax Treaties (Form 8833)
The United States maintains tax treaties with dozens of countries to decide which nation gets primary taxing rights. Depending on the treaty, provisions may affect foreign pensions, employment income, dividends, interest, or capital gains. Treaties may also provide special rules when both countries consider someone a tax resident.
However, benefits aren’t automatic, and not every treaty provision applies to every resident alien. Certain treaty-based return positions also require disclosure using Form 8833.
If you have income in multiple countries, review the specific treaty provisions before assuming foreign taxes or withholding are reduced.
3. Foreign Earned Income Exclusion (Form 2555)
Resident aliens who live and work abroad may qualify for the Foreign Earned Income Exclusion when they meet the relevant requirements.
However, the exclusion generally requires a foreign tax home and qualification under the applicable physical presence or bona fide residence test. Additional restrictions apply to resident aliens using the bona fide residence test. It also applies to qualifying earned income, not investment returns or rental profits.
For resident aliens living and working inside the United States, the Foreign Tax Credit and applicable treaties are generally more relevant to ongoing foreign income.
Foreign Account Reporting: FBAR and Form 8938
Resident aliens may have to disclose overseas bank accounts, brokerage accounts, and other foreign financial assets, even if those accounts generate little or no taxable income.
These are informational filings, separate from calculating the income tax you owe, and they can carry sizable penalties if you don’t file them.
FBAR: Foreign Bank Account Reporting
You must file an FBAR electronically with FinCEN if:
- You are a U.S. person for tax purposes.
- The combined value of your reportable foreign financial accounts exceeded $10,000 at any time during the calendar year.
Foreign financial accounts may include overseas checking, savings, brokerage, and certain pension accounts.
The threshold applies to the aggregate value of reportable accounts, not a separate $10,000 allowance for each account. The reporting calculation generally uses each account’s maximum value during the year, subject to the applicable valuation rules.
The FBAR’s regular due date is April 15, with an automatic extension to October 15.
For detailed filing steps, see our complete FBAR filing guide.
Form 8938 (FATCA Asset Reporting)
Under the Foreign Account Tax Compliance Act (FATCA), certain resident aliens must attach Form 8938 to their federal income tax return if their specified foreign financial assets exceed the applicable thresholds.
For taxpayers living in the United States, the general thresholds include:
| Filing Status | Value at Year-End | Value at Any Time During Year |
| Single or Married Filing Separately | More than $50,000 | More than $75,000 |
| Married Filing Jointly | More than $100,000 | More than $150,000 |
Different thresholds apply to qualifying taxpayers living abroad, and special rules may affect certain individuals.
Specified foreign financial assets can include foreign bank accounts, certain foreign stocks, interests in foreign entities, and other qualifying assets.
Foreign Mutual Funds and Business Holdings
Holding foreign investment funds or operating companies can trigger complex U.S. anti-deferral tax rules. These rules are especially important for resident aliens who maintain investment portfolios or businesses established before moving to the United States.
Foreign Mutual Funds and ETFs (PFICs)
Some foreign mutual funds, ETFs, unit trusts, and investment-linked insurance arrangements may be classified as Passive Foreign Investment Companies (PFICs) under U.S. tax law.
PFIC investments can create two practical hurdles:
- Additional reporting: Certain PFIC interests require Form 8621. Annual reporting requirements depend on the investment, transactions, elections, and applicable exceptions.
- Unfavorable tax treatment: Under the default excess-distribution regime, certain distributions and disposition gains can trigger tax allocations to earlier years and an interest charge, potentially producing a much higher tax cost than ordinary long-term capital gains treatment.
Depending on the investment and eligibility requirements, a Qualified Electing Fund (QEF) or mark-to-market election may change the tax treatment.
These elections aren’t available or appropriate for every fund, and their timing can significantly affect the result.
If you hold foreign investment funds, review their U.S. classification and reporting requirements before making an election, selling shares, or restructuring your portfolio.
Foreign Company Ownership (CFCs)
If you own shares in an operating company, consultancy, or other business registered outside the United States, becoming a U.S. tax resident can create additional reporting and tax obligations.
Under the general rules, a U.S. shareholder owns at least 10% of a foreign corporation’s voting power or value, taking applicable ownership attribution rules into account.
A foreign corporation is generally a Controlled Foreign Corporation (CFC) when qualifying U.S. shareholders collectively own more than 50% of its voting power or value. However, 10% ownership alone doesn’t automatically make a foreign company a CFC.
Depending on your ownership and the company’s classification, you may face:
- Current U.S. taxation: Certain foreign business earnings may be taxable to qualifying U.S. shareholders under Subpart F or net CFC tested income rules, even when the company hasn’t distributed those profits.
- Information reporting: Form 5471 may be required under applicable ownership, control, acquisition, or other reporting categories.
Other foreign entities, including partnerships and disregarded entities, may have different reporting requirements.
Before filing, inventory your foreign business interests and review whether any tax elections or restructuring decisions warrant professional consideration. These decisions can create consequences in both countries.

Have Foreign Accounts, Mutual Funds, or Business Shares?
Foreign Pensions and U.S. Retirement Accounts
Many resident aliens maintain retirement accounts established in another country.
The U.S. doesn’t automatically recognize the same tax treatment that a foreign pension receives in its home country.
- Foreign Pensions: Canadian RRSPs, UK pensions, Australian superannuation arrangements, and other foreign retirement plans may have different U.S. tax treatment depending on their structure and applicable treaty provisions. You’ll need to evaluate contributions, investment growth, distributions, and reporting requirements.
- U.S. retirement plans: Eligible resident aliens can generally participate in employer-sponsored retirement plans and contribute to individual retirement accounts, subject to the applicable income, employment, and contribution rules.
For tax year 2026, the regular employee 401(k) deferral limit is $24,500, while the IRA contribution limit is $7,500. Additional catch-up contributions may be available to eligible individuals.
Traditional and Roth accounts have different tax treatment, and IRA deductions or Roth contribution eligibility can depend on income and filing status.
The 2026 limits apply to 2026 contributions. Limits for the 2027 tax year should be checked separately against official IRS guidance.
What to consider: If you have a foreign pension, don’t assume you should transfer or withdraw it after becoming a U.S. tax resident. Review the U.S. and foreign-country consequences first.
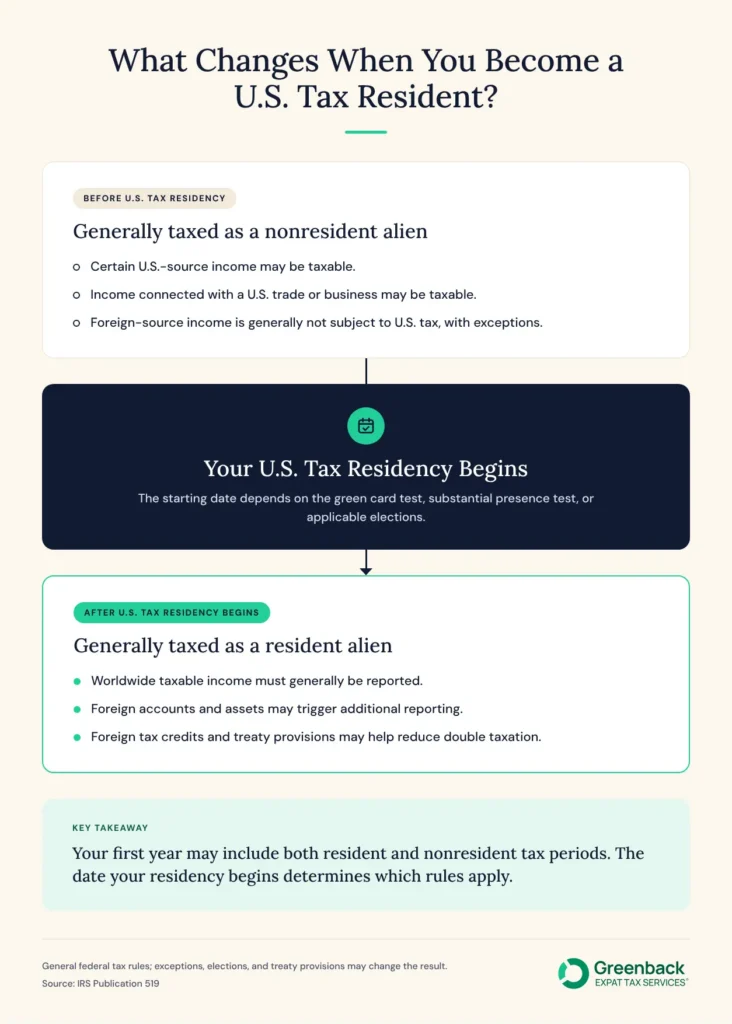
What Changes in Your First Year as a Resident Alien?
Your first year transitioning into U.S. tax residency may require additional planning, particularly if you earned income or accumulated investments abroad before becoming a resident.
The most important steps are establishing your residency start date and determining how the IRS treats your pre-residency income and assets.
Do You Report Income Earned Before Becoming a Resident Alien?
For the most part, foreign-source income received during your nonresident period isn’t subject to U.S. federal income tax unless a special rule applies. However, certain U.S.-source or effectively connected income may still be taxable, and income timing, sourcing, and applicable elections can change the result.
Example: Raj moved from India to the U.S. in July 2026 as a permanent resident. Before moving, he received $40,000 working for an Indian employer in Mumbai. After arriving, he earned $45,000 with an American company.
Assuming Raj wasn’t already a U.S. tax resident and no special election or other rule changes the treatment, his $40,000 Indian salary received during his nonresident period generally wouldn’t be subject to U.S. income tax. His post-arrival U.S. earnings would generally be reportable.
If Raj had U.S.-source income before moving, or received compensation after moving for work performed earlier, additional rules could affect his return.
Do You Need to File a Dual-Status Return?
If you were a nonresident alien for part of the year and a resident alien for the remainder, you may have a dual-status tax year.
Different rules apply to income, deductions, and filing status during each period. Dual-status taxpayers generally cannot claim the standard deduction under the default rules.
Certain married couples may qualify to elect to be treated as full-year residents, although that generally requires reporting worldwide income for the full year and meeting the applicable election requirements.
For detailed filing instructions and elections, read our Dual-Status Alien Tax Filing guide and our guide to mid-year taxes and move-date planning.
What Happens to Investments Purchased Before Moving?
One of the biggest financial surprises for new residents involves capital gains on investments or property purchased before moving to America.
The United States generally doesn’t automatically increase the tax basis of your assets to fair market value on the day you become a resident.
If you sell foreign stock or real estate after becoming a U.S. tax resident, your taxable gain may include appreciation that occurred before your move.
Example: You bought shares in an overseas company years ago for $20,000. On the day your U.S. residency begins, they’re worth $50,000. You sell them a year later for $60,000.
Under general basis rules, the gain would be $40,000 rather than simply the $10,000 increase that occurred after residency began, assuming no other adjustments or special rules apply.
Actual tax treatment depends on the asset, basis calculations, exchange rates, and applicable provisions.
Before selling appreciated foreign assets, review whether the transaction could create tax consequences in both countries.
For more information, see our guide on the tax impact of selling foreign property.
Tax Forms Resident Aliens May Need
Not every resident alien needs every international tax form. Your requirements depend on your income, residency period, foreign assets, ownership interests, and applicable elections.
| Form Number | Official Purpose | When You Need It |
| Form 1040 | U.S. Individual Income Tax Return | Filing your annual federal return as a full-year resident or primary dual-status return |
| Form 1040-NR | U.S. Nonresident Alien Return | Informational statement attached to a dual-status return |
| Schedule B | Interest and Ordinary Dividends | Declaring foreign bank interest and checking foreign account boxes |
| Schedule E | Supplemental Income and Loss | Reporting rental income from domestic or overseas properties |
| Form 1116 | Foreign Tax Credit | Claiming credits for income taxes paid to a foreign government |
| Form 8833 | Treaty-Based Position Disclosure | Claiming reduced tax rates or exemptions under an income tax treaty |
| FinCEN Form 114 | FBAR | Total foreign account balances exceeded $10,000 at any point in the year |
| Form 8938 | FATCA Asset Statement | Specified foreign financial assets exceed statutory thresholds |
| Form 8621 | PFIC Information Return | Holding or selling shares in foreign mutual funds or ETFs |
| Form 5471 | Information Return for U.S. Persons with CFCs | Holding an ownership stake in a foreign corporation |
| Form 3520 | Foreign Trust & Large Gift Reporting | Beneficiary of a foreign trust or receiving gifts over $100,000 from a nonresident |
Other forms, including Form 8865 for certain foreign partnership interests and Form 8858 for certain foreign entities or branches, may also apply.
The best starting point is a complete inventory of your worldwide income and financial assets, rather than assuming your U.S. return is limited to domestic wages.
Key Tax Numbers for the 2027 Filing Season
If you’re preparing a 2026 federal income tax return in 2027, the applicable standard deductions and contribution limits are based on the 2026 tax year.
If you become a resident alien during calendar year 2027, you’ll generally use 2027 tax-year rules for the return ordinarily filed in 2028.
Here are several confirmed figures relevant to 2026 returns:
| Tax Rule or Account | 2026 Amount | What It Means |
| Standard Deduction: Single / MFS | $16,100 | Basic deduction for eligible filers |
| Standard Deduction: Married Filing Jointly | $32,200 | Basic deduction for eligible joint filers |
| Standard Deduction: Head of Household | $24,150 | Basic deduction for qualifying filers |
| 401(k) Employee Deferral Limit | $24,500 | Regular employee contribution limit, before eligible catch-up contributions |
| IRA Contribution Limit | $7,500 | Regular annual contribution limit, subject to eligibility |
| FBAR Aggregate Account Threshold | More than $10,000 | Determines whether reportable foreign financial accounts may trigger FBAR filing |
| Form 8938: Single Taxpayer Living in the U.S. | More than $50,000 year-end / $75,000 at any time | General specified foreign financial asset thresholds |
The standard deduction amounts generally don’t apply to taxpayers using the default dual-status filing rules.
How to Use These Numbers for Your Timeline
- If you were a U.S. tax resident during 2026: Your federal return is generally due April 15, 2027, unless a different deadline, extension, or postponement applies.
- If you’re becoming a U.S. tax resident in 2027: Your first resident or dual-status return would ordinarily be filed in 2028. Review the official 2027 tax-year limits rather than assuming the 2026 amounts will remain unchanged.
- If you maintain foreign accounts: Remember that foreign account and asset reporting thresholds have separate rules and aren’t necessarily increased alongside income tax brackets.
For someone planning a 2027 move, the most important financial decisions may involve appreciated investments, foreign retirement accounts, business ownership, and when U.S. worldwide income taxation begins.
Resident Alien Tax Filing Mistakes to Avoid
Once you are classified as a resident alien, many filing mistakes involve foreign assets, cross-border income, and reporting requirements rather than domestic wages.
1. Failing to Plan for Pre-Move Capital Gains
Because the U.S. generally doesn’t reset the tax basis of existing assets to fair market value on your residency start date, selling appreciated foreign investments after becoming a resident may create unexpected U.S. taxable gains.
The fix: Review appreciated assets before establishing residency or selling them. Evaluate both U.S. and foreign-country tax consequences before making changes.
2. Treating Foreign Mutual Funds Like U.S. Index Funds
Certain foreign mutual funds and ETFs may fall under PFIC rules, creating additional reporting and potentially unfavorable tax treatment.
The fix: Review whether your holdings are PFICs, whether Form 8621 applies, and whether an available election would be appropriate for your circumstances.
3. Missing the FBAR Reporting Threshold
The $10,000 FBAR threshold applies to the aggregate value of reportable foreign financial accounts, not individually to each account.
The fix: Review all reportable accounts, determine their maximum values using the applicable rules, and assess whether an FBAR is required.
4. Attempting to E-File a Dual-Status Return
First-year residents often prepare a dual-status return using commercial tax software, only to have the IRS reject the e-file transmission. Dual-status returns combine Form 1040 and Form 1040-NR and must be filed on paper.
The fix: Prepare the dual-status return with proper statement headers and mail the physical paperwork to the dedicated IRS processing campus.
5. Overlooking State Tax Residency Rules
State residency doesn’t always align with federal IRS rules. You may have state filing requirements even if your federal residency or filing treatment is different.
The fix: Check the specific domicile and statutory residency rules for your state, particularly if you relocated midyear or work remotely.
Resident Alien Tax Filing Checklist
Before preparing your resident alien return, work through these steps:
- Confirm your tax residency status and whether your classification changed during the year.
- Determine the appropriate tax return, including any special dual-status filing requirements.
- Gather worldwide income records, including foreign employment, investments, rental income, and pensions.
- Identify foreign financial accounts, investments, and business interests that may require additional reporting.
- Review foreign taxes paid and possible tax credits or treaty relief.
- Confirm applicable deductions, credits, and filing elections.
- Check federal and state tax obligations, including withholding and estimated tax payments.
- Review the relevant filing deadlines and extension requirements.
- If you recently became a U.S. resident, establish your residency starting date and review pre-residency income and appreciated assets.
Completing this review early can help you avoid missed forms, unexpected taxes, and corrections later.

File Your Tax Return with Confidence
Frequently Asked Questions
Yes. Resident aliens are generally taxed on worldwide income, including foreign wages, interest, dividends, rental income, and other taxable amounts. Qualifying foreign tax credits, exclusions, or treaty provisions may help reduce double taxation, but receiving income through a foreign employer or bank doesn’t automatically exclude it from U.S. taxation.
Not necessarily. Foreign-source income received during your nonresident period generally isn’t subject to U.S. income tax unless special rules apply. However, U.S.-source or effectively connected income may still be taxable, and the timing of income recognition, applicable elections, and other circumstances can change the result.
You may have a dual-status tax year, with different rules for the resident and nonresident portions. Your income, deductions, and return filing procedures depend on your residency start date and circumstances. Some taxpayers may qualify for elections that change their treatment. See our Dual-Status Alien Tax Filing guide.
Not always. If you were already a U.S. tax resident under the substantial presence test, receiving a green card may not create a new period of worldwide income taxation. If you weren’t previously a resident, lawful permanent resident status can establish U.S. tax residency under the applicable starting-date rules.
Possibly. FBAR reporting is generally based on U.S.-person status and the aggregate value of reportable foreign financial accounts, not whether the accounts earn interest. Form 8938 has separate definitions and thresholds. An account may be reportable even if it didn’t generate taxable income.
Transferring money you already own between bank accounts isn’t itself taxable income. However, the source of the funds and related transactions may have tax consequences. Foreign account reporting can also apply even if you’ve moved the funds to the United States.
Possibly. Becoming a U.S. tax resident generally doesn’t automatically increase the basis of previously owned investments. If you sell appreciated assets after becoming a resident, the U.S. tax calculation may include gains that accumulated before your move, subject to applicable basis, currency, and special tax rules.
They can be. Certain foreign mutual funds and exchange-traded funds may be treated as Passive Foreign Investment Companies (PFICs), which can trigger special tax calculations and Form 8621 reporting. The result depends on the investment, holding period, elections, and applicable transition rules.
Possibly. Foreign retirement arrangements may generate taxable income or information-reporting requirements depending on their structure and applicable treaty provisions. Tax-deferred treatment in your previous country of residence doesn’t necessarily carry over to the United States.
Resident aliens treated as full-year residents may generally claim the standard deduction and eligible credits, subject to the requirements for each benefit. Dual-status taxpayers generally cannot claim the standard deduction under the default rules, and some credits have additional residency, income, or identification requirements.
Possibly, but the income and tax timing matter. A Foreign Tax Credit generally depends on qualifying foreign taxes and income subject to U.S. tax, along with applicable limitations. Taxes paid on income that isn’t subject to U.S. taxation don’t automatically generate a usable credit.
Some couples may qualify to elect resident treatment for a nonresident spouse and file jointly. The election can affect both spouses’ worldwide income reporting and other tax obligations, so compare the consequences with the available alternatives before filing.
They may. States use their own residency and income-sourcing rules, which don’t always match federal tax residency. Depending on where you live and work, you may need to file a resident, part-year resident, or nonresident state return.
Possibly. If you have income without sufficient U.S. withholding, such as self-employment income, foreign investment income, or rental income, estimated tax payments may be necessary. The requirement depends on expected tax liability, withholding, and applicable exceptions.
You may need to review or correct prior tax returns and related international information reporting. For example, filing Form 1040-NR after becoming a resident alien could mean you omitted worldwide income or required foreign asset disclosures. The right corrective action depends on your filing history, the years involved, and the applicable rules.

Featured In


